

The Fed’s July minutes landed Wednesday and they were the hawkish version. Three regional presidents dissented in favour of a quarter-point raise, several participants favoured that raise at the meeting itself, and many said tightening would likely become necessary if inflation didn’t decline. That’s a committee arguing about when to tighten, in a year most people spent waiting for cuts.
The bond market’s relief came from somewhere else. The Treasury will lift its own buying of ten-to-thirty year debt to at least four billion dollars per operation between September 9th and November 4th. The thirty-year touched 5.33% Tuesday, a nineteen-year high, then sat near 5.19% Wednesday with the long-bond fund up 1.7%. That buying is small against long-end supply and funded elsewhere on the curve, so it’s a floor under liquidity and not new demand. Health care ran 3.5% Wednesday on one late-stage drug result while semiconductor equipment lost between three and a half and six and a half percent. The semiconductor side is the one that trades against a 5.19% long bond.
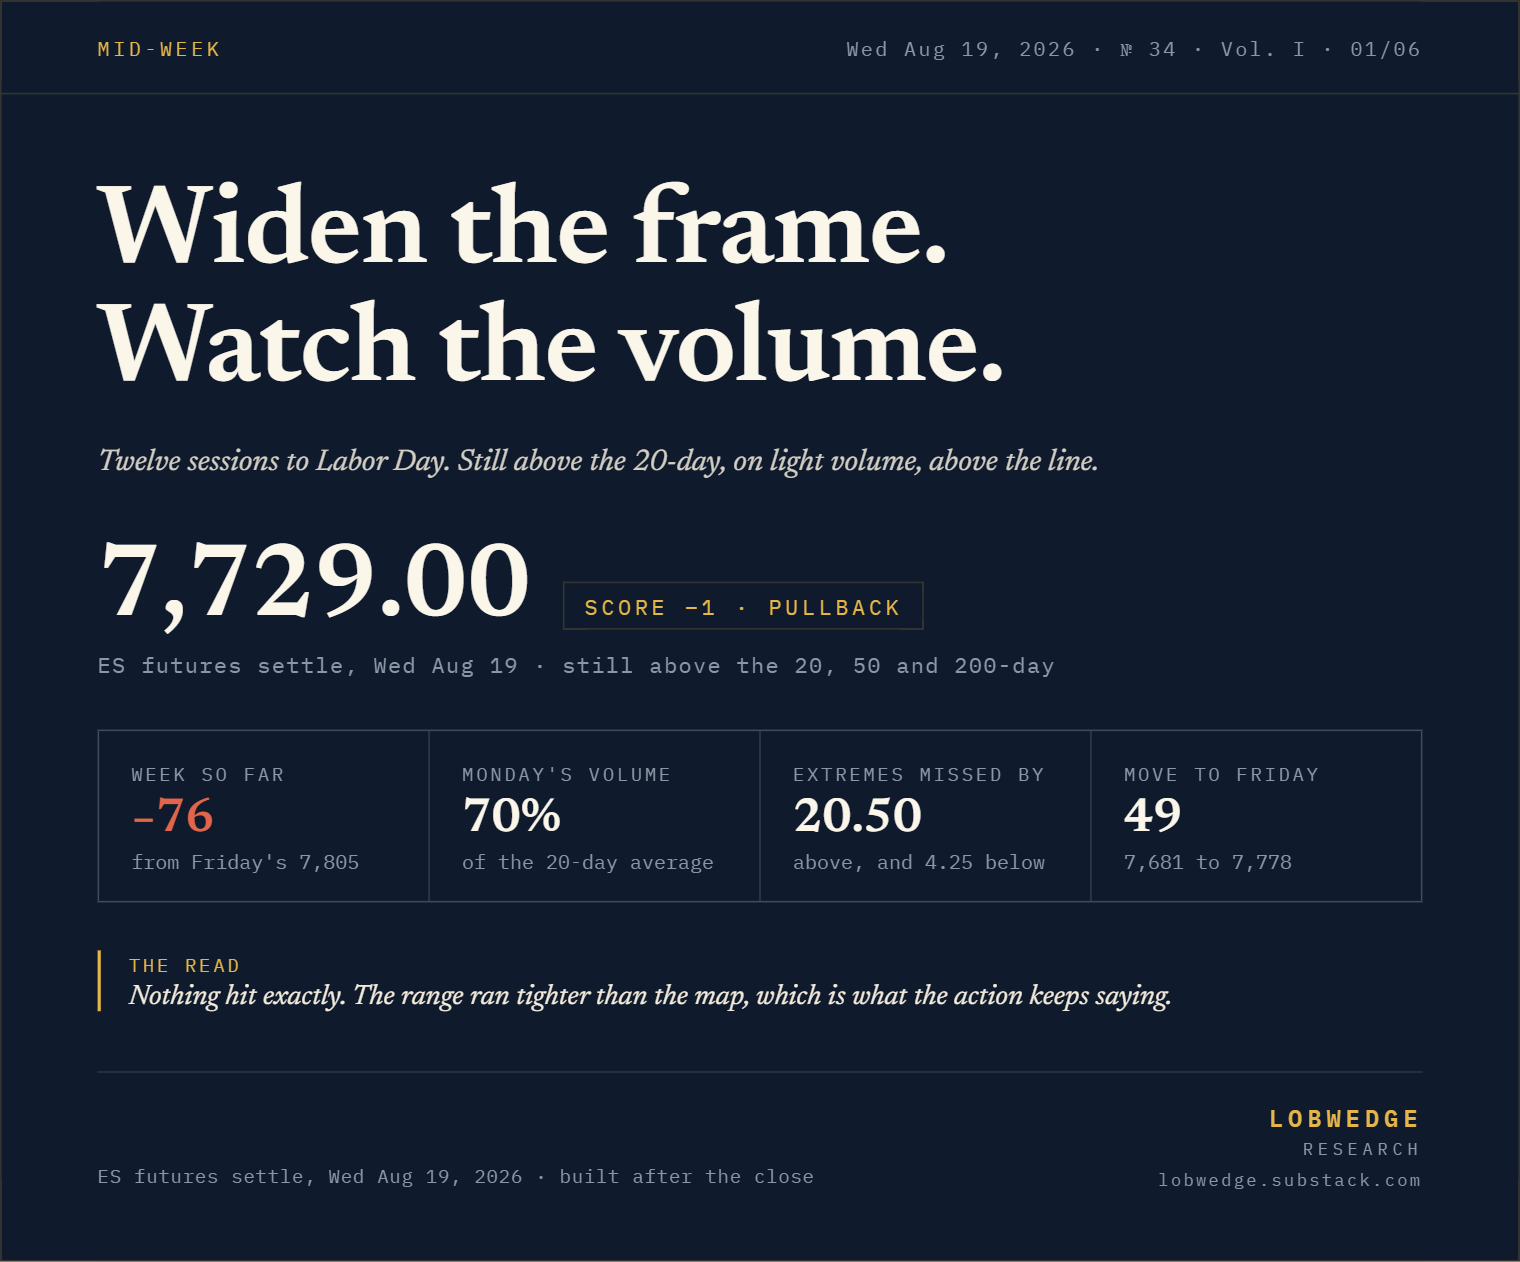
Below: the grade against Sunday’s five prices, the score, the re-struck map, the setups, and a quick word on every open position.
