

Weekly Trading Plan: September 30 - October 4, 2024
Market Overview
This week, the market's direction will be influenced by two major factors: China’s new economic stimulus measures and Friday’s U.S. jobs report. China's aggressive efforts to boost its economy have triggered rallies in global markets, especially in industries tied to commodities and manufacturing. Meanwhile, U.S. markets, which are at all-time highs, remain cautious ahead of the jobs data that could swing sentiment either way.
Expect early-week calm, maybe just after monday, then perhaps traders hold back for Friday’s labor report, which will give clues about the U.S. economy's health and whether the Federal Reserve's plan for a “soft landing” is on track.
Global Macro View: What’s Driving the Market
China’s Stimulus Boost:
China recently announced both monetary and fiscal support to jumpstart its sluggish economy. This has sparked a 15% surge in Chinese stocks and lifted global industries tied to China, like industrials and commodities (think copper, steel, and luxury goods). The big question is whether this rally will have staying power or if it’s a short-term reaction.U.S. Jobs Report (Friday):
The most anticipated event this week is Friday’s nonfarm payroll report, which will reveal how many jobs were added in September and whether wages are still rising. Economists expect 140,000 new jobs and unemployment to remain at 4.2%. The stock market has dropped sharply after the last two jobs reports, so this one is a key event to watch. A strong report could push the market higher, but if the numbers disappoint, it could trigger a sell-off.Japan’s Political Shift:
A political shake-up in Japan, with the election of a new prime minister, has led to a drop in Japanese stocks. The new leader is seen as more likely to support tighter monetary policies, which could slow growth. Keep an eye on how this plays out in the broader Asian market.
Overall Sentiment:
We start the week cautiously optimistic due to China’s stimulus, but the looming U.S. jobs report adds an element of uncertainty. Traders are likely to tread carefully until Friday’s data provides more clarity.
Market Indicators & Trends
Put/Call Ratio: The current ratio of 0.76 suggests a slightly bullish market, though there’s noticeable hedging in place, showing some nervousness ahead of Friday’s jobs data. Watch for spikes above .88 for better opps.
Seasonal Trends: Historically, October begins with positive market moves as stocks rebound from the typical September weakness. However, the jobs report could disrupt this pattern.
S&P 500 Insights: 30-Day Trading Patterns
Midday Strength (12-1 PM): There’s a 61% chance of positive returns in this hour, based on the last 30 days.
Opening Gap (First Hour): 65% chance of gains at the open, with an average return of +0.20%.
End-of-Day Strength (3-4 PM): The final trading hour has a 65% chance of gains.
Takeaway:
These patterns suggest midday and end-of-day trading provide the best opportunities for gains. Early in the week, focus on these periods for potential short-term trades. Expect a quieter midweek. First with gamma roll off monday and then with volatility increasing as Friday’s report approaches.
Key Events and Strategies
Economic Reports:
Tuesday, Oct. 1: ISM Manufacturing Index, JOLTS (Job Openings)
Focus: Strong manufacturing data could signal that sectors like industrials and materials remain in demand, especially those connected to China.
Friday, Oct. 4: Nonfarm Payrolls, Unemployment Rate
Focus: This report will heavily influence market sentiment. If the labor market shows strength, it could boost stocks; if it shows signs of weakness, expect some selling pressure. Consider reducing exposure or hedging your portfolio ahead of this event.
Earnings Reports:
Monday, Sep. 30: Carnival (CCL)
Focus: Carnival’s results will provide insights into consumer spending on travel and leisure. Look for commentary on how fuel costs and travel demand are affecting margins.
Tuesday, Oct. 1: Nike (NKE)
Focus: Nike faces headwinds in North America, and analysts are divided on its outlook. A key indicator will be how Nike is performing in China, which is a major growth market for the company.
Thursday, Oct. 3: Constellation Brands (STZ)
Focus: As a defensive consumer stock, STZ could offer some stability if markets get volatile. Watch for their outlook on consumer spending trends.
Technical Analysis: Dow Futures (YM) for Tells?
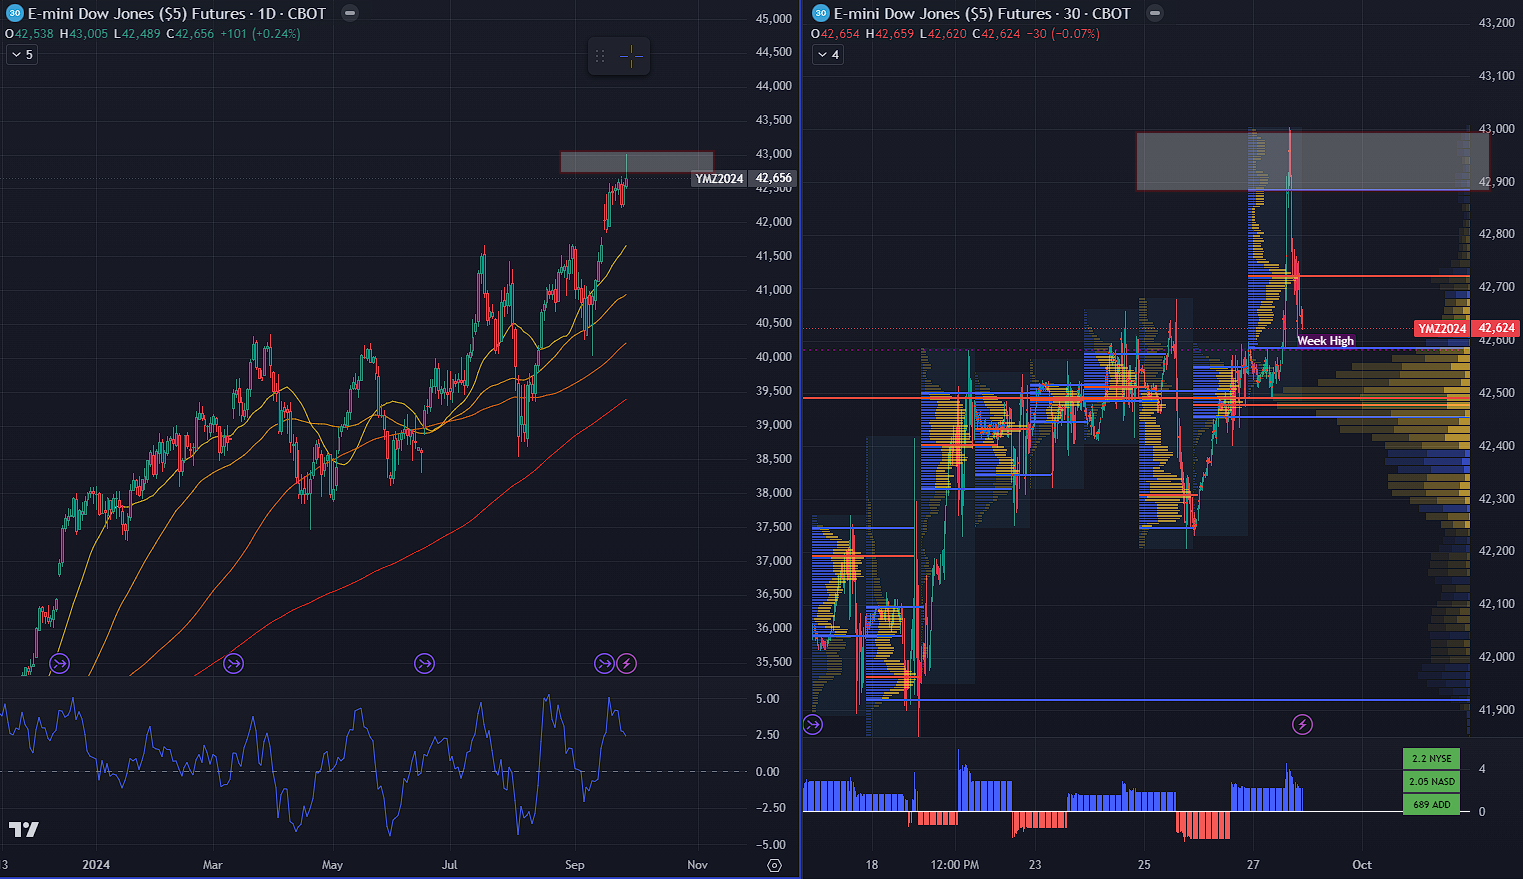
Dow Futures (YM): Last week’s high of 43,000 serves as a critical resistance point. A breakout above this level would signal broader strength in the market and suggest that industrial stocks could lead the next leg higher. Until then, it's not an ideal time to chase the rally in the Dow, especially with other sectors already showing strength.
Strategy:
Watch 43,000 closely. If the Dow breaks through, it could be a signal to rotate into lagging sectors like industrials. If it stays below this level, it’s better to focus on sectors with clearer momentum, such as tech or commodities.
Investment Themes & Opportunities
Growth vs. Value:
Growth stocks, especially in tech, continue to outperform. But with the jobs report on the horizon, defensive value stocks like utilities or consumer staples could come into favor if labor market data disappoints.Sector Rotation:
Industrials and materials have rallied on the back of China’s stimulus. Companies like Freeport-McMoRan (FCX) and Rio Tinto (RIO) could extend gains as long as demand from China remains strong. Keep an eye on these sectors for signs of continued strength.Global Markets:
Emerging markets, particularly those with exposure to China, are benefiting from the stimulus package. Chinese ETFs or companies with significant China exposure could offer attractive but risky opportunities.
Risk Management
Primary Risk:
The biggest risk this week is the U.S. jobs report on Friday. If the labor market shows significant weakness, it could prompt a sell-off, especially in sectors sensitive to economic growth like consumer discretionary and financials. Traders may want to reduce exposure to high-beta stocks or consider hedging strategies such as buying protective puts ahead of the report.Secondary Risks:
A potential East Coast port strike is looming, which could disrupt supply chains and push up inflation, especially for goods-related sectors like retail and transportation. This would add pressure to consumer goods companies and logistics stocks. Pay attention to shipping costs and logistics reports for early warning signs.
Conclusion
This week offers a mix of optimism from China’s stimulus and uncertainty surrounding the U.S. labor market. Early in the week, focus on sectors benefiting from Chinese growth, like industrials and commodities, but be cautious of any exuberance. Friday’s jobs report is the major inflection point—prepare for heightened volatility.
Key levels to watch include 43,000 in Dow Futures (YM), as a break above could signal renewed strength in cyclicals. In the meantime, stick to sectors with momentum, such as tech and materials, and keep a close eye on U.S. economic data as it unfolds.
Keep risk management tight, especially as Friday approaches. Whether the jobs report delivers good or bad news, be prepared to react quickly and adjust positions accordingly. Stay nimble and aware of potential catalysts that could shift sentiment in either direction.