

Market Overview
Last week’s trading was dominated by a hawkish FOMC meeting that triggered a midweek sell-off, followed by a sharp rebound spurred by cooler-than-expected Personal Consumption Expenditures (PCE) data and dovish commentary from Fed officials. The S&P 500 ended the week recovering key technical levels, supported by optimism about the year-end rally, a phenomenon often referred to as the “Santa Claus Rally.”
The upcoming holiday-shortened week will likely see lighter trading volumes, with minimal economic data releases and no major earnings reports. The backdrop of lower yields and resilient consumer data creates a moderately bullish setup.
Macro Pulse
Economic Indicators:
Durable Goods Orders (expected: -0.4%) and New Home Sales (expected: 650K) will provide insights into the strength of the manufacturing and housing sectors.
Japan's Consumer Price Index (CPI) for October, projected at -2.5%, could influence global risk sentiment.
Inflation and Fed Policy: The Fed’s downward revision of 2025 rate cut expectations has tempered bullish sentiment, but softening inflation data keeps the door open for future easing. The 10-year yield remains below the psychologically significant 5% level, providing a tailwind for equities.
Key Themes
Seasonality: December typically favors equities due to performance-chasing and lighter trading activity, which can amplify momentum trends.
Technical Resilience: Indices such as the S&P 500 and Nasdaq 100 are holding above key support levels, signaling potential for further gains.
Technical Analysis
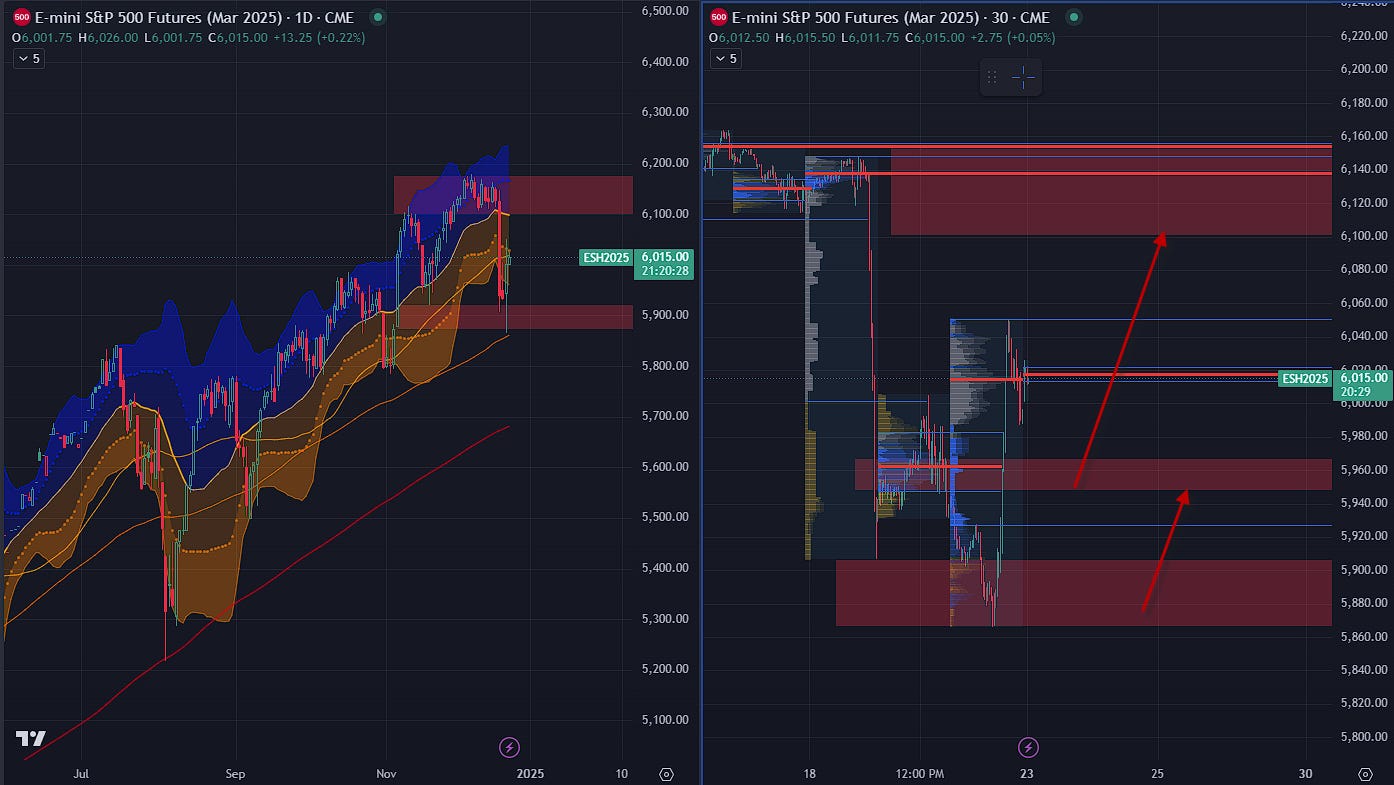
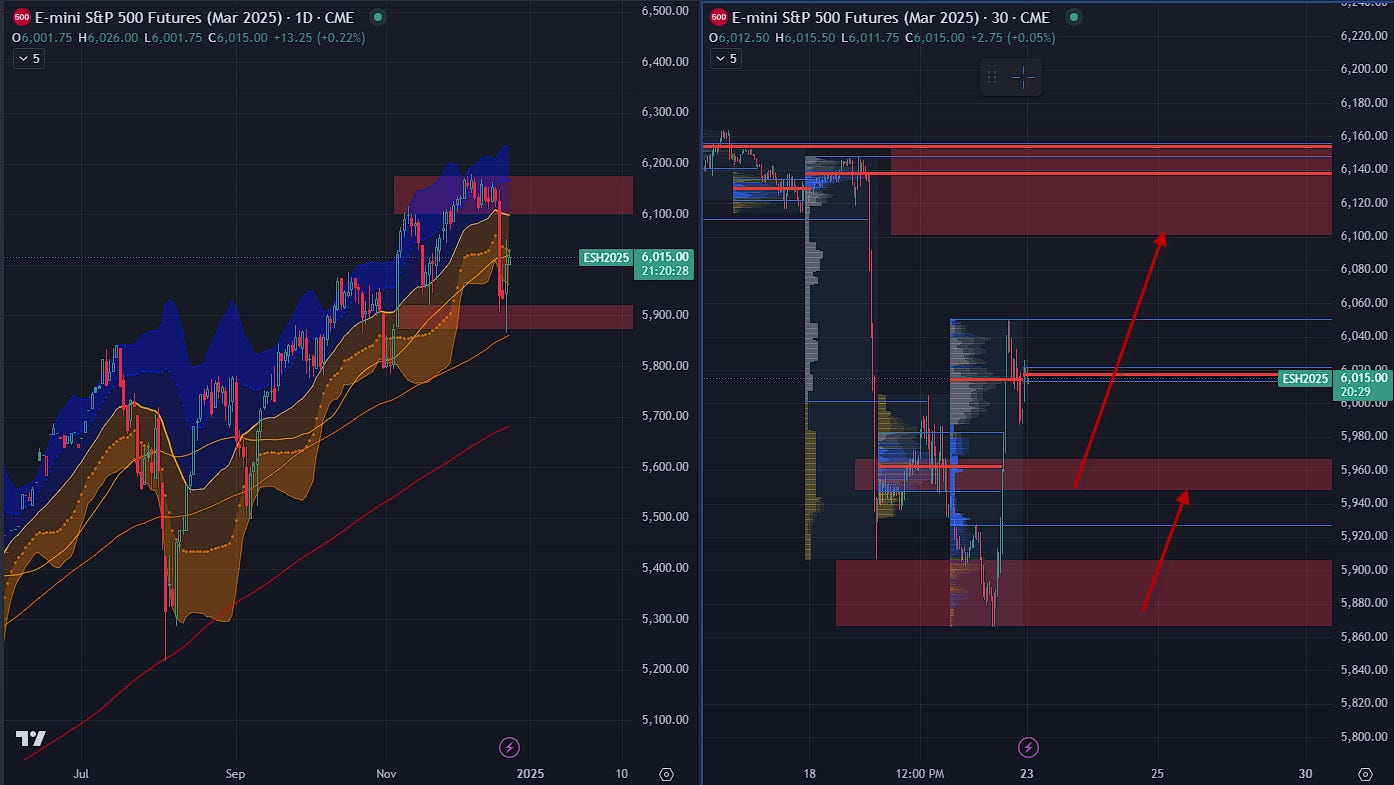
S&P 500 (SPX): Closed at 5,962, reclaiming its 50-day simple moving average (SMA). The bullish engulfing pattern suggests upward momentum with near-term resistance at 6,000.
Nasdaq 100 (NDX): Continued leadership from the tech sector kept the index above its 50-day SMA. Watch for a breakout above 21,600 to confirm strength.
Market Breadth: Participation remains fragile, with fewer stocks above their 200-day SMA compared to recent weeks. Broader strength is necessary to sustain upward trends.
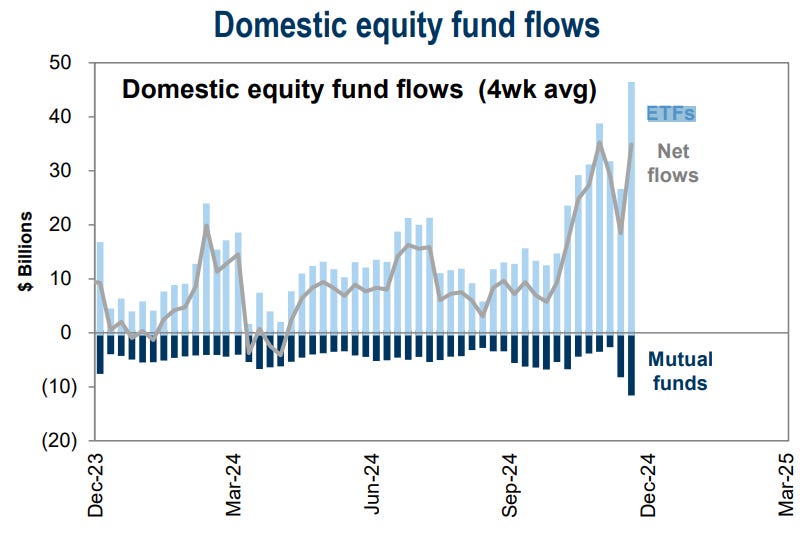
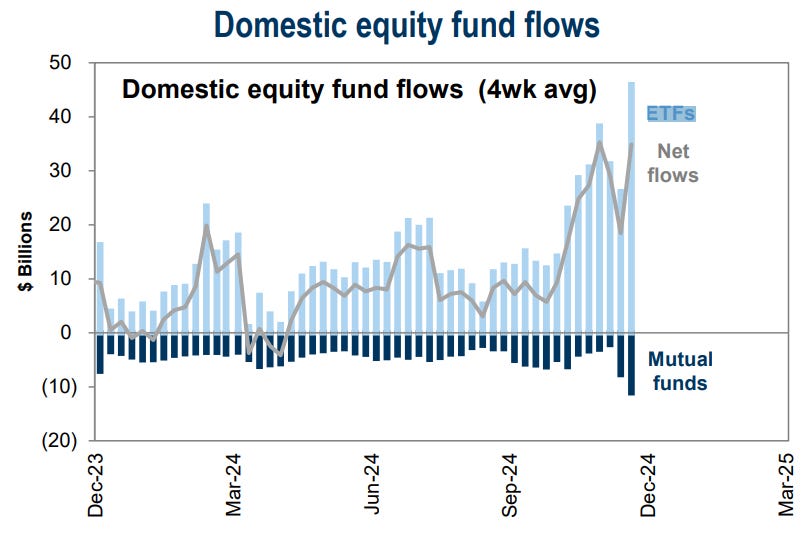
ES
Key Events
Economic Data:
Tuesday (12/24): Durable Goods Orders, New Home Sales
Thursday (12/26): Initial and Continuing Jobless Claims, Crude Oil Inventories
Friday (12/27): Advanced International Trade in Goods, Retail Inventories
Dividend Watch: Companies with upcoming ex-dividend dates include Broadcom (AVGO), Southwest Airlines (LUV), General Electric (GE), Philip Morris (PM), and Altria (MO).
Strategic Focus
Moderately Bullish Bias: Favor sectors with strong relative performance, such as technology and consumer discretionary, while remaining cautious of rising yields or unexpected geopolitical developments.
Risk Management
Yield Sensitivity: Monitor the 10-year Treasury yield closely. A rise above 5% could pressure equities.
Profit-Taking: Be prepared for consolidation after last week’s rally.
Liquidity: Thin trading volumes can amplify price swings; adjust position sizes accordingly.
Trade IDEA:
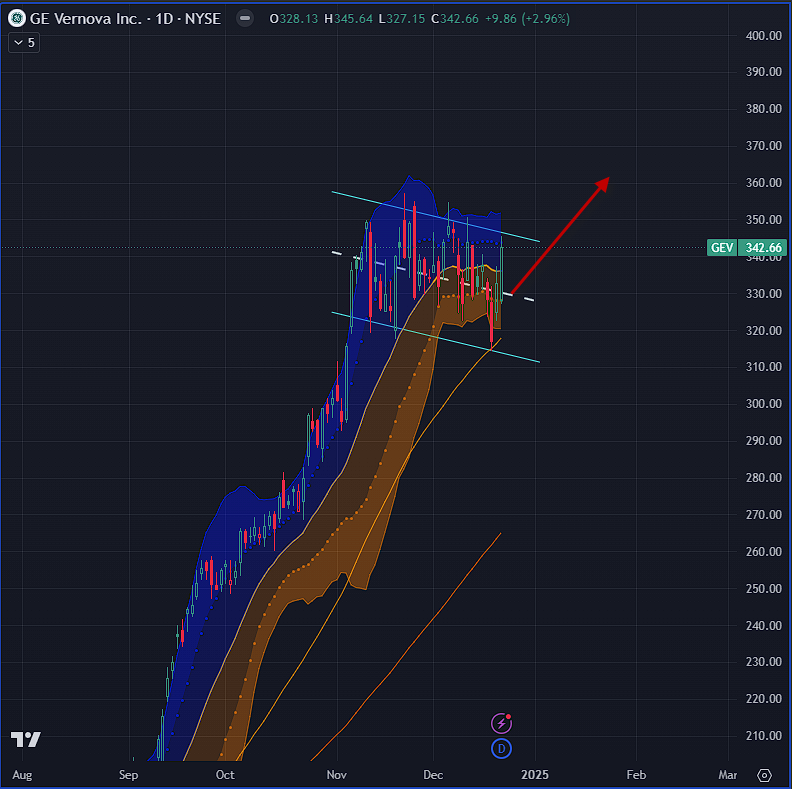
GEV into year end.. 355 ignites the herds, and under 330 wrong.
Why GE Vernova (GEV)?
GE Vernova is positioned for strong growth in 2025, fueled by rising energy demand from artificial intelligence and data center investments. The company’s advanced natural gas turbines and expansion into nuclear energy make it a key player in the energy sector. Since spinning out from General Electric, GEV’s stock has surged over 200%. Recent initiatives include a $1 annual dividend, a $6 billion share buyback, and improved revenue and cash flow forecasts. Additionally, GE Vernova is advancing in the nuclear field with small modular reactors in the U.K., further strengthening its long-term growth prospects.
Conclusion
The upcoming week’s light calendar and favorable seasonal trends support a moderately bullish stance. Focus on high-conviction trades in resilient sectors and manage risks by scaling down positions in anticipation of heightened holiday-week volatility. The technical outlook remains constructive as long as key indices hold above their 50-day SMA.