

Market Overview
As we close out 2024, it’s been a remarkable year for equities. The S&P 500 is up 25%, the Nasdaq has surged 31%, and the Dow has gained 14%. Despite these gains, the historical nature of markets suggests 2025 is unlikely to follow a smooth or “average” trajectory.
Markets rarely deliver “average” returns. Since 1926, annual S&P 500 returns have fallen within a narrow range only 17% of the time. Instead, returns tend to cluster at extremes, shaped by macroeconomic shocks, valuation adjustments, and investor sentiment. This sets up a compelling framework for extreme scenarios in 2025:
📉 A pullback below 5500.
📈 A rally above 7100.
The return of political disruption, shifting Federal Reserve policy, and heightened economic uncertainty all signal a year of volatility. For traders, this presents both challenges and opportunities.
Macro Pulse
Key Themes for 2025
Markets Don't Do "Average":
Consensus targets (e.g., S&P 500 at 6040, +10%) often fail to capture the outsized moves that dominate market history. Expect greater deviations driven by earnings surprises, unexpected policy shifts, and valuation dynamics.
The Trump Presidency Redux:
President Trump’s return heralds potential disruption in trade, immigration, and foreign policy.
Expect tariff-driven trade adjustments, stricter immigration controls, and reduced U.S. involvement in global conflicts to create volatility, particularly in sectors like manufacturing, defense, and energy.
With two years before midterms, Trump’s policy changes are likely to be front-loaded, creating significant market turbulence early in his term.
Fed Policy and Rates:
Markets currently expect just two rate cuts in 2025. However, political and economic disruptions could drive additional easing, especially if growth slows or labor markets weaken.
Rate cuts tied to economic fragility could temper equity gains, as lower rates would signal deeper systemic concerns.
Crypto Resurgence:
Bitcoin’s 112% YTD return underscores its role as both a macroeconomic hedge and speculative asset.
Key drivers for 2025 include regulatory clarity, institutional adoption, and the rise of DeFi innovations such as tokenized real-world assets and AI-integrated decentralized finance.
Blockchain infrastructure plays, such as Globalstar (GSAT) and Ethereum Layer-2 protocols, also merit attention as they support Web3 growth.
Sector and Thematic Insights
High-Volatility Growth Sectors
Quantum Computing: Companies like Rigetti Computing (RGTI) and Quantum Computing (QUBT) have demonstrated explosive growth, reflecting heightened interest in breakthrough technologies.
AI Leaders: Palantir (PLTR) and Soundhound AI (SOUN) stand out, with strong performance tied to enterprise adoption of AI solutions.
Crypto Ecosystem Expansion
Bitcoin: Sustained institutional interest positions BTC as a leading hedge and speculative asset.
DeFi and Web3: Tokenized real-world assets and AI-driven decentralized finance are poised to attract both institutional and retail capital.
Sustainability and Clean Energy
Energy Storage: Eos Energy Enterprises (EOSE) reflects the growing demand for scalable clean energy solutions.
Sustainable Aviation: Archer Aviation (ACHR) exemplifies the intersection of electrification and innovation in transportation.
Technical Analysis for the Week
ES
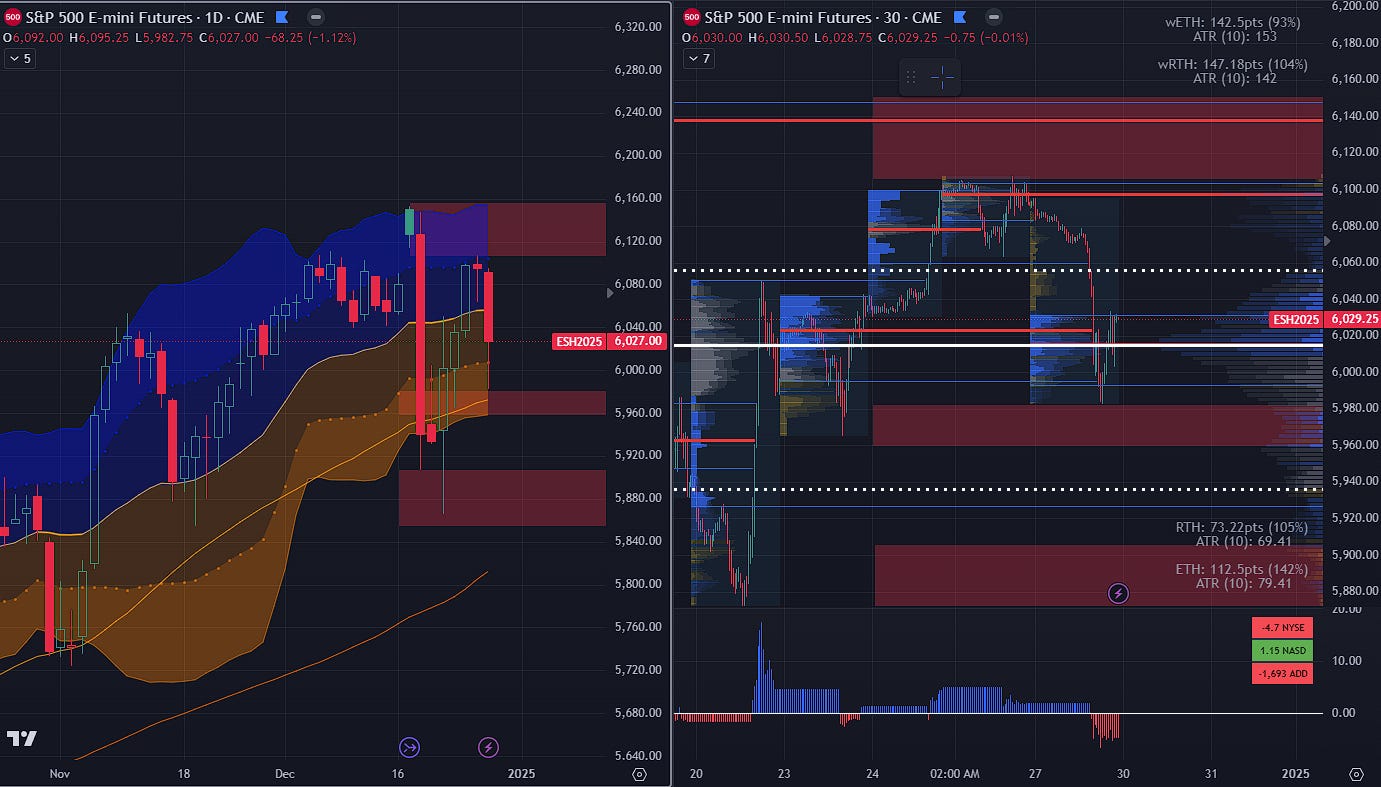
Monday, December 30
Chicago PMI: Forecasted at 42.7, indicating continued contraction in manufacturing activity. A stronger reading could boost sentiment in industrial sectors.
Pending Home Sales: Expected to rise by 0.9%, providing insight into housing market demand and its resilience against rising rates.
Tuesday, December 31
S&P Case-Shiller Home Price Index: Anticipated to show a 4.2% YoY increase, reflecting moderate growth in housing prices amid affordability constraints.
Earnings:
No major earnings reports scheduled.
Thursday, January 2
Jobless Claims: A key indicator of labor market strength. Stable claims would align with expectations for gradual cooling in employment.
Construction Spending: Expected to rise by 0.25%, with implications for housing, infrastructure, and materials stocks.
Earnings:
No major earnings reports scheduled.
Friday, January 3
ISM Manufacturing Index: Forecasted at 48.5, staying below the expansion threshold of 50. A weaker result could increase concerns over manufacturing sector contraction.
Earnings:
No major earnings reports scheduled.
Ex-Dividend Dates
Tuesday, December 31:
Deere (DE): Payout Date: February 10, 2025.
Mondelez (MDLZ): Payout Date: January 14, 2025.
Thursday, January 3:
Cisco (CSCO): Payout Date: January 22, 2025.
American Express (AXP): Payout Date: February 10, 2025.
Other Key Events
Bond Market: Closing early on New Year’s Eve (2:00 PM ET).
Market Closures: U.S. markets closed on Wednesday, January 1, in observance of New Year’s Day.
Risk Management
Volatility Hedging:
Expect amplified price swings, especially in crypto and high-beta equities. Maintain disciplined position sizing.Yield Monitoring:
Rising Treasury yields above 5% could pressure equity valuations, particularly in growth-sensitive sectors.Regulatory and Political Risks:
Stay attuned to developments in crypto regulations and policy shifts under Trump’s administration, as they could have sector-specific impacts.
Conclusion
2024 ends on a high, but 2025 brings a landscape of heightened volatility and transformational opportunities. Markets rarely move in averages—prepare for the extremes and trade strategically.
Happy New Year! Stay safe, and see you in 2025 for more insights and strategies. Let’s tackle the challenges and seize the opportunities of the new year together!
"Volatility isn’t a threat—it’s where the edge lies. Stay prepared, stay disciplined, and embrace the extremes."
no trading plan for next week?