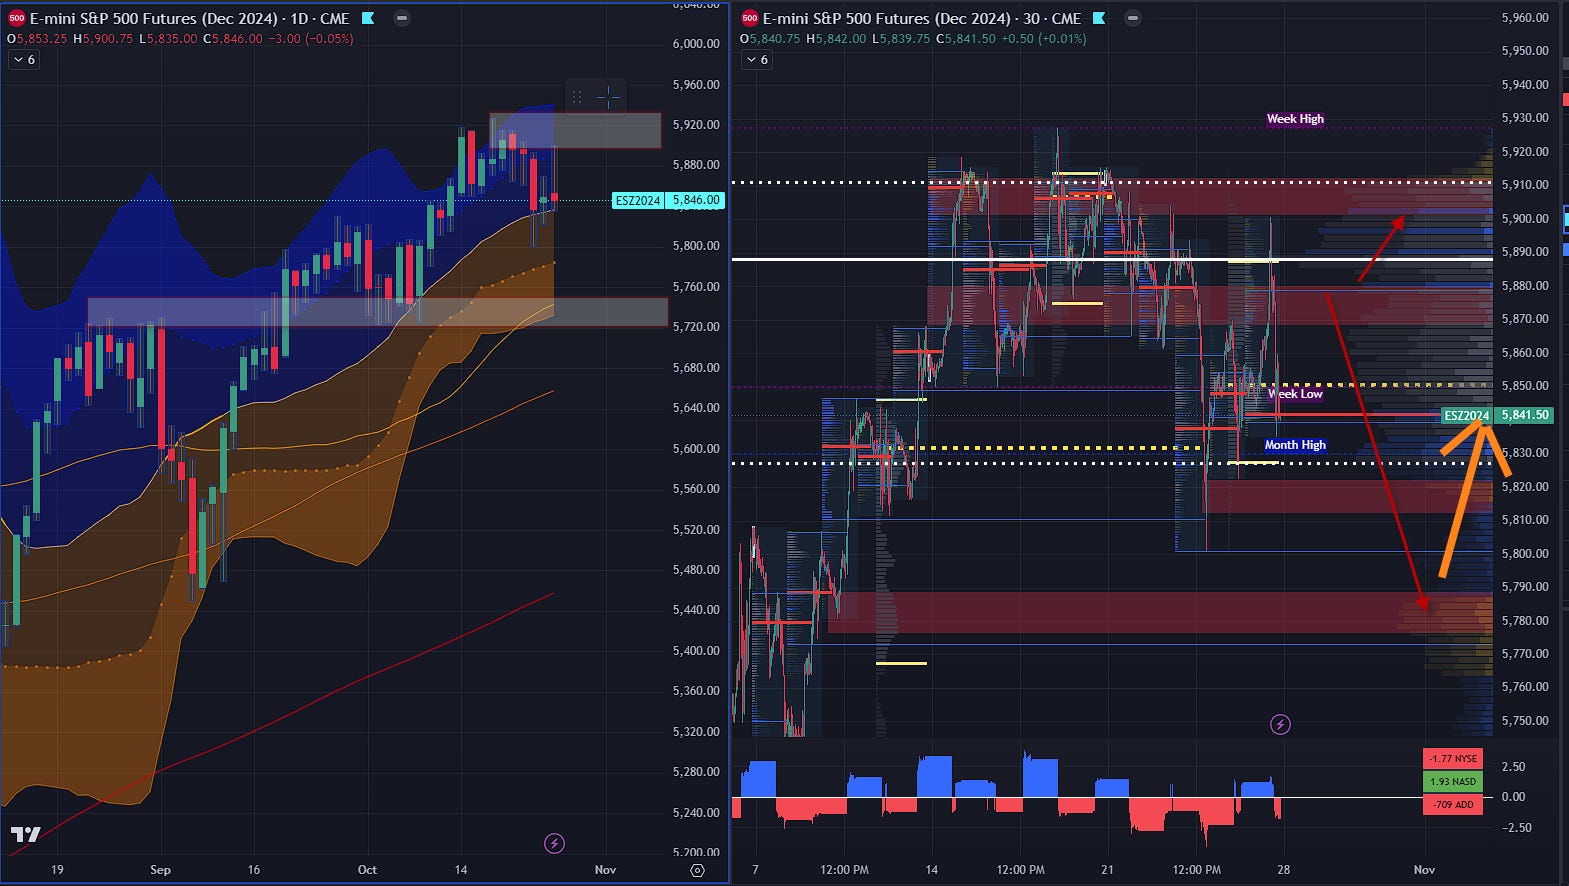
The S&P 500 is wrapping up its first down week after seven consecutive gains, with rising bond yields prompting profit-taking. Initially “slightly bullish,” my outlook shifted as bond yields pushed higher, driven by strong economic data and expectations of increased Treasury issuance. The 10-year yield settled at 4.23% while the 2-year rose to 4.10%, putting pressure on stocks and adding uncertainty to the Fed’s next steps.
Earnings So Far: Out of the 183 S&P 500 companies that have reported, revenue growth averaged 3.88% and earnings 3.59%. While these numbers are solid, expectations for future quarters remain high, with FactSet projecting 14% EPS growth in Q4 and 15.1% for 2025. The IMF also raised its U.S. growth forecast for 2024 to 2.8%, signaling continued economic strength, though this adds some complexity to rate-cut expectations.
Market Breadth: Participation narrowed further this week, with only 42-56% of stocks in major indices (S&P 500, MidCap, SmallCap, and Nasdaq) trading above their 20-day EMAs, signaling weakening momentum across the board. The S&P 500 large-cap and MidCap segments each sit around 42%, indicating limited strength in these typically leading segments. Small-caps are weaker at 36.17%, likely impacted by rising yields, while the Nasdaq shows relative strength at 56%, driven by tech resilience. This concentrated strength in tech and large-cap names suggests potential vulnerability: if these leaders falter, the broader market could see further declines. With key economic data and election uncertainty ahead, this contraction in breadth supports a cautious approach for the coming week.
Updated Outlook for Next Week
Fundamentals First: With major economic reports like GDP, Core PCE, and NFP due, along with Election Day and the Fed’s rate announcement in the following weeks, I’ll be closely monitoring core economic indicators to stay grounded in fundamentals. These events will provide critical context on the economy’s strength and inflation trajectory, impacting everything from rate outlook to market sentiment. In a market driven by a few outperforming sectors, I’m sticking to a fundamentals-driven approach, especially when broader participation is thinning.
Contrarian Perspective: Market sentiment has swung to cautious territory, but I'm prepared to consider contrarian moves if the fundamentals align. For instance, Tesla’s recent earnings highlight a promising 2025 growth trajectory, making it a potential contrarian long play if the broader market pulls back. Also watch DJT as a proxy for TSLA.
Risk/Reward Discipline: Below 5870 on S&P 500 futures, I’ll keep a short bias with active hedge algorithms, demanding a favorable risk/reward setup. If we break above 5870, I’ll reassess the short bias, particularly if mega-cap earnings come in strong or yields ease. Given the narrowing market breadth and volatility risks, maintaining a disciplined focus on entries with a favorable risk/reward ratio will be key. Assuming 5790 is where buyers may show up.
Upcoming Market Events (All times EST):
Wednesday, Oct 30 (8:30 am): GDP – Essential for gauging economic resilience.
Thursday, Oct 31 (8:30 am): Core PCE – A critical inflation measure.
Friday, Nov 01 (8:30 am): NFP – Offers insight into labor market strength.
Tuesday, Nov 05: Election Day – Political uncertainty could add volatility.
Thursday, Nov 07 (2:00 pm): Fed Rate Announcement – A major influence on rate expectations.
In summary, I’m adopting a “cautiously contrarian” stance. With Tesla as a selective long lotto plays and active hedges on broader indices, it’s a week to stay disciplined, watch the fundamentals closely, and demand a strong risk/reward setup before making any moves.
Have a nice week.