

The S&P 500 (SPX) pushed into fresh all-time highs again, briefly touching the 6,100 area before backing off slightly into the end of the week. The index finished Friday near 6,090, up roughly 1% on the week. The advance maintained its “melt-up” character, supported by a favorable macro backdrop and stable to lower Treasury yields. While the index’s rally slowed a bit as it approached critical option-related thresholds, underlying market structure remains supportive.
What moved the markets?
Steady Macro Data: U.S. economic indicators continued to reflect resilience. Slightly mixed employment data, strong construction spending, and healthy job openings underscored a growth picture that investors remain comfortable with. Market participants also noted Europe’s upcoming industrial production data as a global growth indicator.
Option Market Dynamics: The SPX’s flirtation with the 6,100 “call wall” illustrated how key option strikes can guide price action. This interplay offered both a target and a cap, suggesting an environment where large options positions influence short-term trends.
QQQ Strength & Risk Appetite: The Nasdaq-100 and QQQ maintained relative outperformance, reflecting ongoing investor interest in mega-cap tech and growth names. Meanwhile, pockets of speculative interest persisted—e.g., specific names highlighted as overbought or oversold, and the continued appetite for thematic areas like AI and crypto.
What’s On Deck This Week?
Market Structure & Seasonality in Focus:
With the SPX still near significant option-related levels, keep an eye on how prices react to key strikes. Seasonal tailwinds, persistent inflows, and subdued volatility all argue for continued support, but watch for any catalysts that might stir temporary consolidation.
Macro Events to Watch:
U.S. Inflation Data (CPI on Wednesday, PPI on Thursday): These prints arrive just a week before the Fed’s policy decision. Softer readings may reinforce expectations for a rate cut, while hotter numbers could muddy the outlook.
European Industrial Production: A fresh look at Europe’s economy may offer global context. With U.S. markets near all-time highs, any notable European strength or weakness could influence global capital flows.
Treasury Auctions & Yields: The 10-year auction mid-week may affect bond yields. If yields rise unexpectedly, we might see some risk assets pausing or consolidating.
Potential Inflection Points:
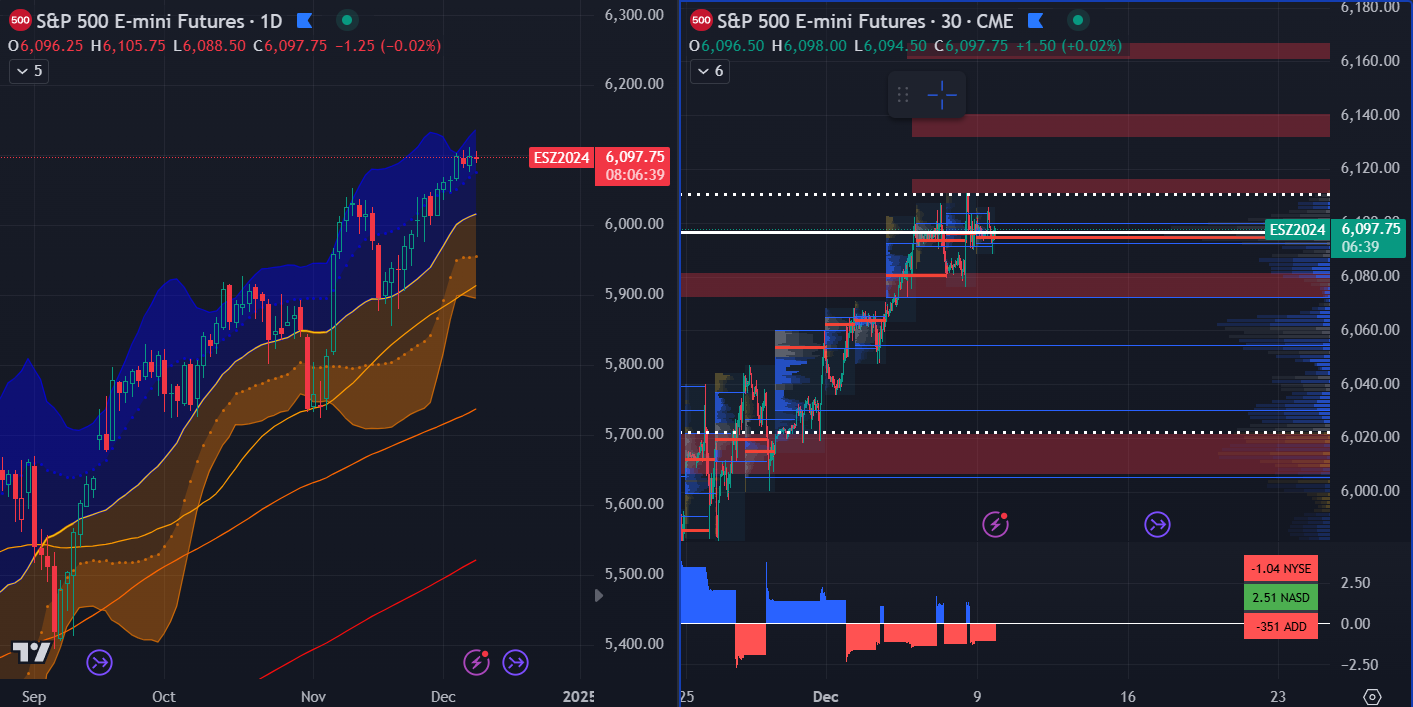
Key suport (~6,045–6,055): Should the market slip below these levels, expect some near-term volatility.
Call & Put Walls: The SPX remains “sandwiched” between heavy call interest near 6,100 and sturdy put positions around 5,800. A break above the call wall could spur additional upside, while drifting toward the volatility trigger area might encourage tactical selling.
Tactical Levels to Watch (ES Futures)
We remain in a low-volatility regime with defined option levels, suggesting a stable-to-positive short-term bias unless yields or data unexpectedly shift sentiment
Breadth & Participation
Although breadth slightly narrowed, with fewer stocks above their 200-day SMAs, participation remains sufficiently broad. While the rally may be getting more selective, it’s not signaling imminent deterioration. Most sectors and size segments still show enough strength to keep the overall trend intact.
Stocks and Themes to Keep an Eye On
Earnings & Corporate Developments:
This Week’s Highlights:
Monday (12/9): Oracle (ORCL), Toll Brothers (TOL), Casey’s (CASY)
Tuesday (12/10): AutoZone (AZO), Ferguson (FERG), GameStop (GME), Ollie’s (OLLI), Academy Sports (ASO)
Wednesday (12/11): Adobe (ADBE)
Thursday (12/12): Broadcom (AVGO), Costco (COST), Ciena (CIEN)
Oracle’s report may highlight cloud momentum and AI-driven software demand, while Broadcom’s results could showcase ongoing AI-related tailwinds. Costco’s performance will be scrutinized for holiday spending insights, and Adobe’s numbers may reflect enterprise IT budgets as we head into year-end.
IPO & Dividend Activity:
ServiceTitan (TTAN) is on deck to price its IPO, adding a new name to the public markets. On the dividends front, watch for changes from companies like Alphabet (GOOG, GOOGL), UnitedHealth (UNH), FedEx (FDX), Travelers (TRV), HP (HPQ), Walmart (WMT), and expected dividend hikes from American Eagle (AEO), Broadcom (AVGO), and Abbott Labs (ABT).Investor Conferences & Sector Insights:
Events hosted by major financial institutions feature big names like American Express (AXP), Coinbase (COIN), Blackstone (BX), JPMorgan (JPM), and others, potentially shedding light on financial sector health, fintech adoption, and broader macro views. Similarly, the Barclays Global Tech Conference includes top tech names such as Salesforce (CRM), Twilio (TWLO), Uber (UBER), and Zscaler (ZS), offering a window into next-gen tech trends.
From the Flow Desk
ETF & Index Flows: Steady inflows into passive equity products persist, reinforcing a baseline of demand that supports prices. This backdrop suggests dips may remain shallow.
Volatility Considerations: While volatility hasn’t collapsed completely, it remains low. Traders are not rushing to sell premium aggressively, yet no immediate signs of panic demand for protection have emerged either.
Where’s the Action?
Small and Mid Caps: Slightly softer participation, but still within a supportive framework. Renewed broadening could push these segments higher once again.
Mega-Cap Tech & Growth: Continues to provide leadership. As long as these names remain strong, the broader market should find reasons to hold up.
Macro Picture: With U.S. markets near record highs, stable growth, and a likely Fed rate cut in the offing, the backdrop remains constructive. International data, inflation prints, and policy signals remain secondary considerations at this point but can still nudge sentiment.
Risks:
A surprise inflation spike or yield jump could challenge the current risk-on narrative.
Failure to break above the 6,100 call wall might spark near-term volatility as traders reposition.
Any shift in corporate or consumer sentiment signaled by upcoming earnings or conference commentary could alter the outlook.
Final Thoughts
As we head into mid-December, the S&P 500 remains well-positioned. Seasonality, robust flows, and supportive market structure keep the rally intact, even as it brushes against well-defined option thresholds. Key earnings reports, inflation data, and yield dynamics may add some wrinkles, but the underlying bias leans bullish. Unless fundamental or macro surprises emerge, the incremental buyer still appears ready to step in on minor dips.