

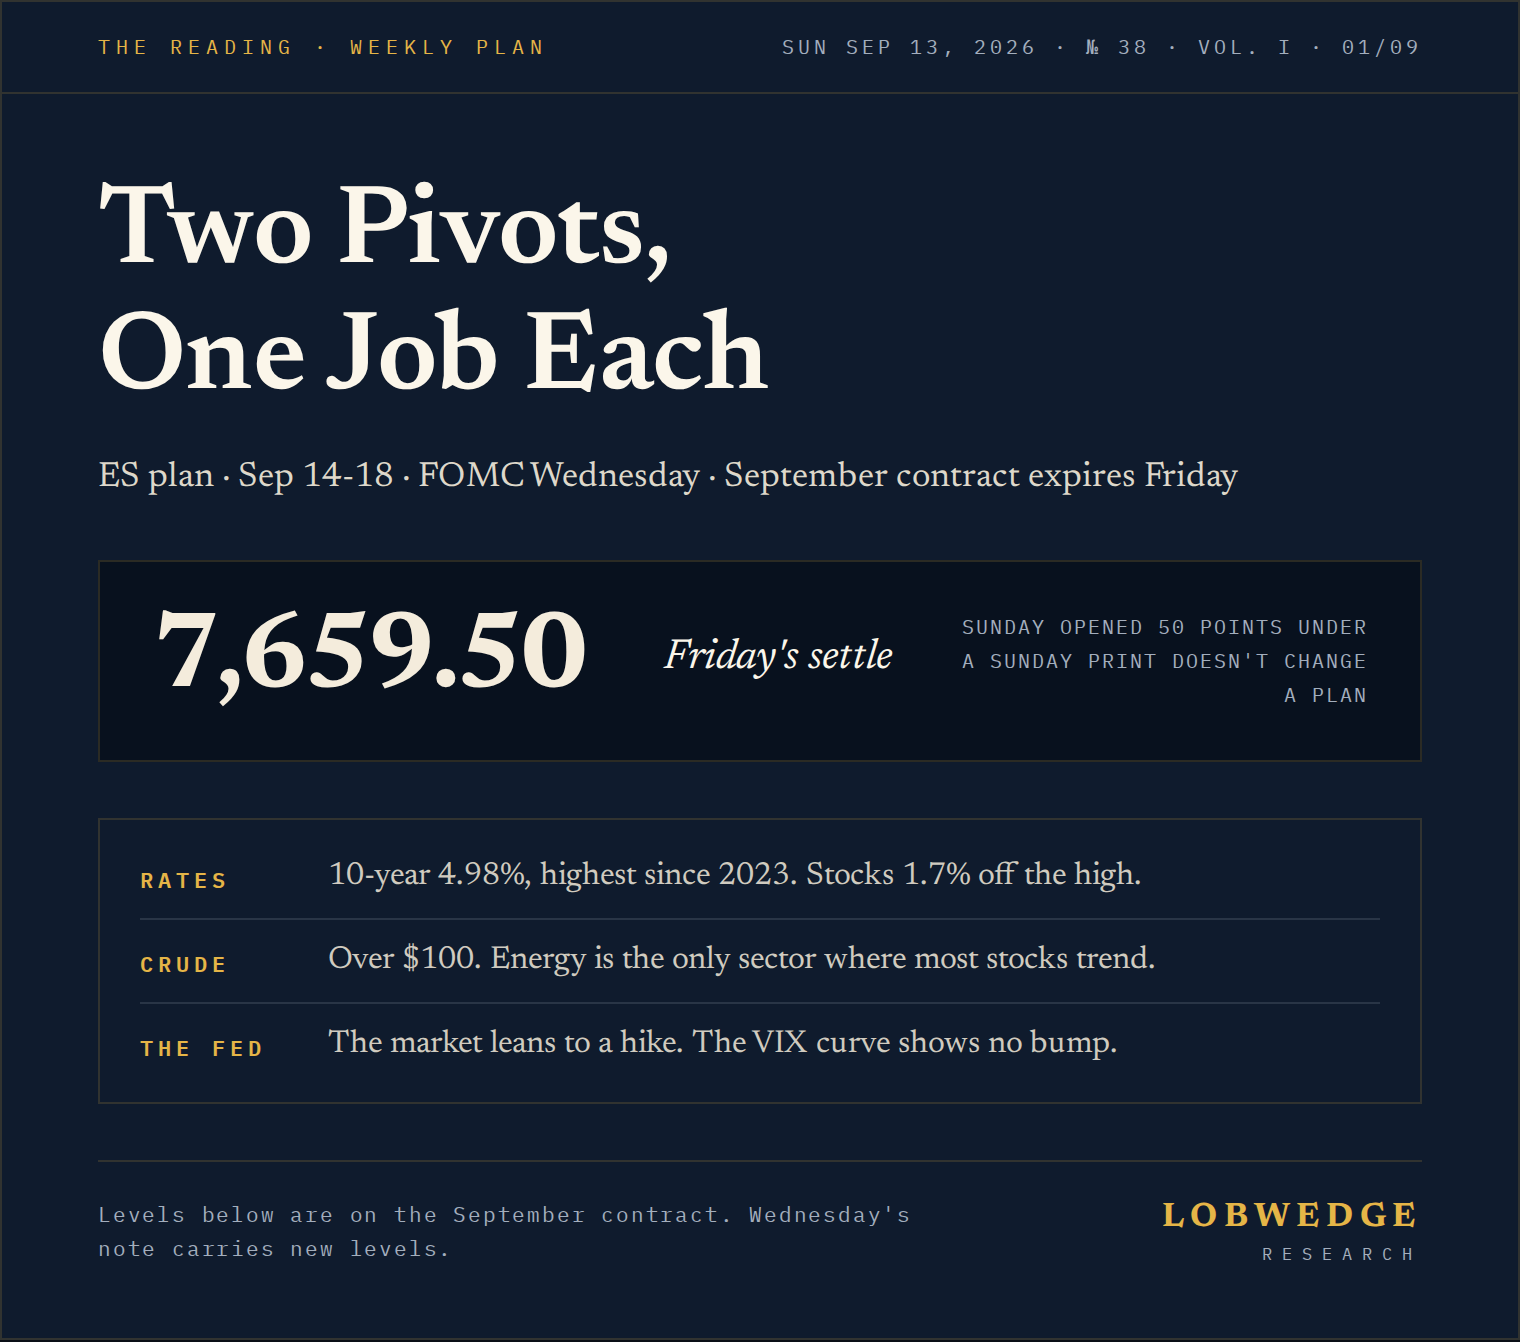
A note on the prices first. Every level below is on the September ES contract, which stops trading Friday morning. The December contract is already the active one and trades about 68 points higher. Wednesday’s note will carry a new set of levels on December. Until then, don’t mix the two. Check your contract before you check the level.
Five things worth knowing about this market before Wednesday.
The 10-year yield touched 4.98% on Friday, its highest since 2023, and the S&P closed the week 1.7% off its high. Yields at a three-year high and stocks that close to their high don’t usually sit together for long. One of them is wrong. You’ll know which by Wednesday.
Crude is up 23% in a month and over $100. Energy is the only group where most stocks are in an uptrend: 7 in 10 energy names are above their own trend line, against 1 in 6 industrials. The index looks calm because the biggest names are holding it up. Underneath, barely a quarter of the S&P 500 is trending higher.
The market is leaning toward a rate hike Wednesday, and the volatility market hasn’t marked it. The VIX closed at 15.8 and the futures curve shows no bump at all for the Fed meeting. Either the market is sure about the outcome, or the September VIX contract expiring that same morning is hiding it.
Friday’s ES volume was the largest in months, and a good part of that was the roll into December rather than a change of heart. Don’t read the volume bar as capitulation. Nothing in the fear gauges moved. Not one.
Sunday night futures opened 50 points under Friday’s settle on no news I can point to. A Sunday print doesn’t change a plan. A daily close does, and the two closes that matter this week are below the line.
Last week’s published lean lost. The scorecard is below, in full. No excuses in it.
The regime, the seven levels, the lean, the rotation board, and the week’s calendar are below the line.
