

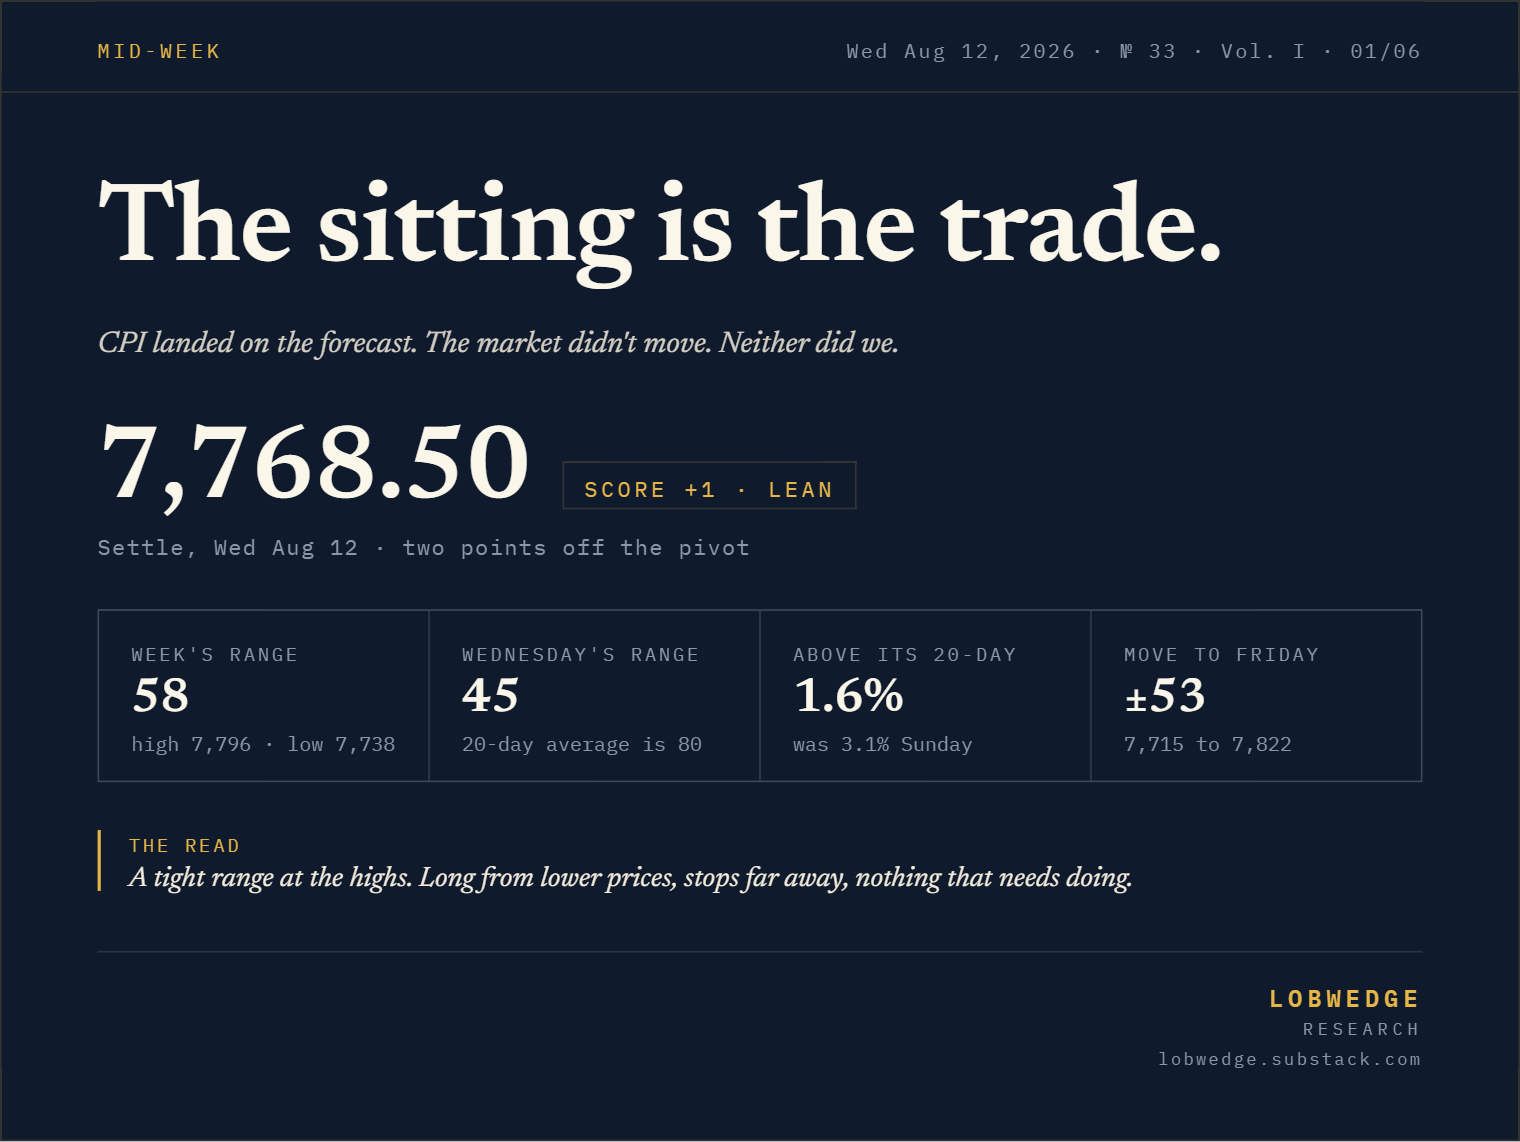
Wednesday’s inflation number was the one print this week that could settle Friday’s argument, and it settled nothing. Up 0.1% on the month, 3.4% on the year, core at 2.5%. Every figure on the forecast. September hike odds barely moved, around 44%, right where Friday’s jobs report left them. The index added a quarter percent and settled at 7,768.50, almost exactly where it started the week.
Look at what the week is instead of what it isn’t. The whole range so far is 58 points, Wednesday traded 45 against a 20-day average of 80, and volume has declined every session. That’s consolidation, two weeks into a 6.7% run, a few points under a record. Sunday called this a visit-and-decide week: price would probably tag the pivot early and Wednesday’s number would pick the direction. It tagged the pivot Monday. Wednesday didn’t pick a direction.
So the decision rolls forward, and the discipline this creates is the oldest one in the book. Jesse Livermore said it a century ago: “It never was my thinking that made the big money for me. It always was my sitting.” We came into this week long from lower prices with the stops far away. When the market goes quiet at the highs, the amateur urge is to make something happen. The position that’s working doesn’t need help. It needs to be left alone.
Below: the scorecard, the two prices that matter into Friday, where the money is actually placed after CPI, and the names earning entries while the index sits still.
