

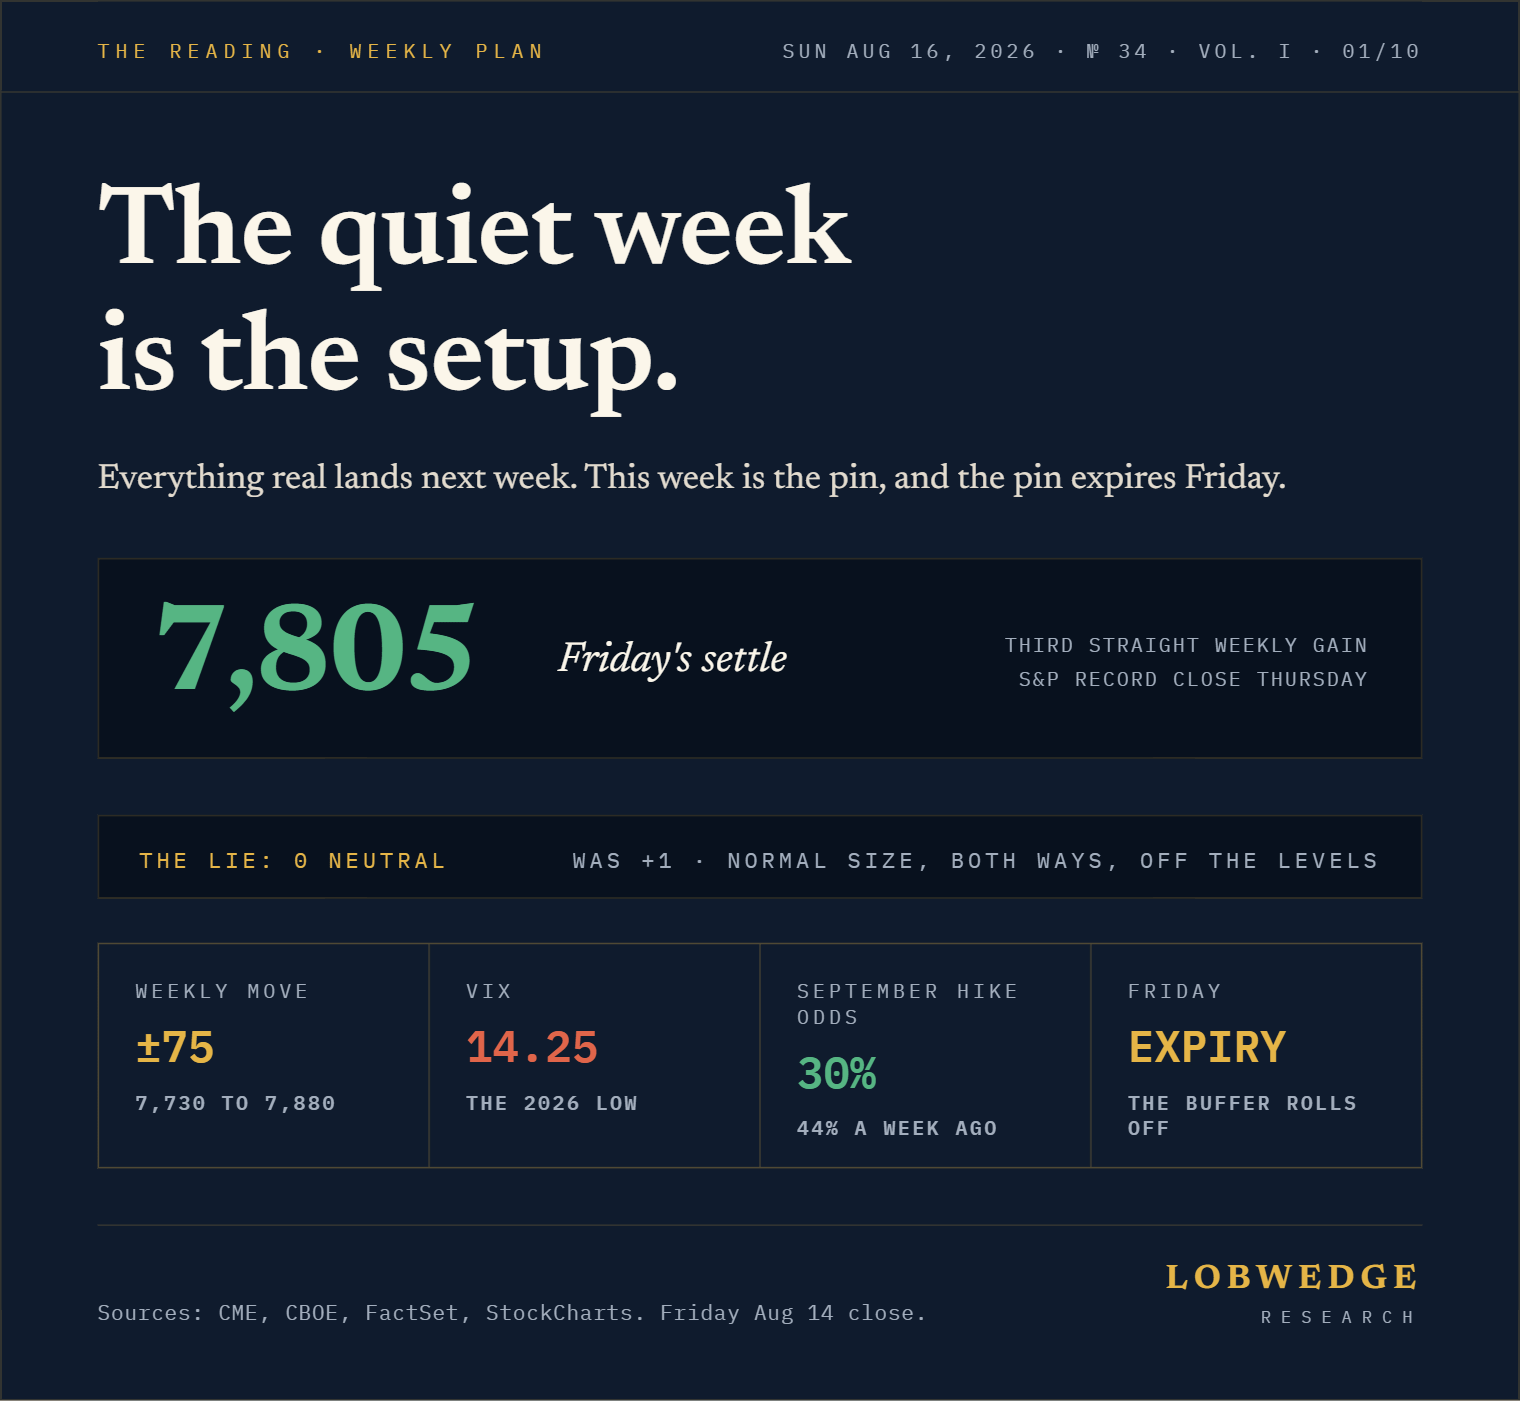
Last Sunday we priced the week as a tight hold around the pivot, and that’s what printed: five sessions inside a 100-point band, a record close Thursday, and a Friday settle at 7,805, up 25 on the week.
The bigger picture, so one week doesn’t get read in isolation: the index is up more than a fifth from its April low, it’s climbed three straight weeks since the start-of-August breakout, and for two weeks running the deep buys on our maps never filled because price never came back for them. Strong trend, shallow dips.
Now what makes this week different. NVIDIA (NVDA) reports Wednesday the 26th. The Fed’s Jackson Hole meeting, the new chair’s first, runs the 27th through the 29th. Both land next week. This week carries a retail earnings parade, the Fed’s July minutes, and Friday’s monthly options expiration, the day the positions that have been absorbing every dip since early August roll off the board.
The trend going into a monthly expiration reverses coming out of it about two weeks in three. We’ve been rallying into this one for three straight.
The economy underneath isn’t confirming the price. July payrolls printed minus 23,000 with 103,000 of downward revisions behind them. Retail sales fell 0.6%, the biggest drop in more than a year. Friday’s consumer sentiment survey collapsed to 51. And none of it moved the bond market the way weak data should: the 30-year sat at 5.27% Friday, a level last seen in 2007, after an auction that priced at the highest yield in 25 years. Soft data, hard yields. Whoever is selling long bonds isn’t reading the economic calendar, and that’s the tension the new chair inherits at Jackson Hole.
September hike odds sit near 30%, down from 44% a week ago on two cool inflation prints. The direction of risk is still a raise, not a cut.
Everything below is for paying subscribers: the score, the map, the one order we’re working, the protection trade, and four names off the filings pass.
