

Happy Father’s Day. It’s a good Sunday to be off the screens: Wyndham Clark takes a six-shot lead into the final round of the US Open this afternoon, with the World Cup on in the background. Watch Clark and you’ll catch the week’s lesson. With a lead that big, the winning play isn’t a hero shot, it’s not handing it back. That’s our setup too. We came in with a constructive call and the market near its highs, so the job is to protect it, not force it. The hardest discipline in this game is sitting still. When the odds are a coin flip, the pros wait for the right setup instead of manufacturing a trade, and this week the right setup isn’t up here at the highs. It’s the dip.
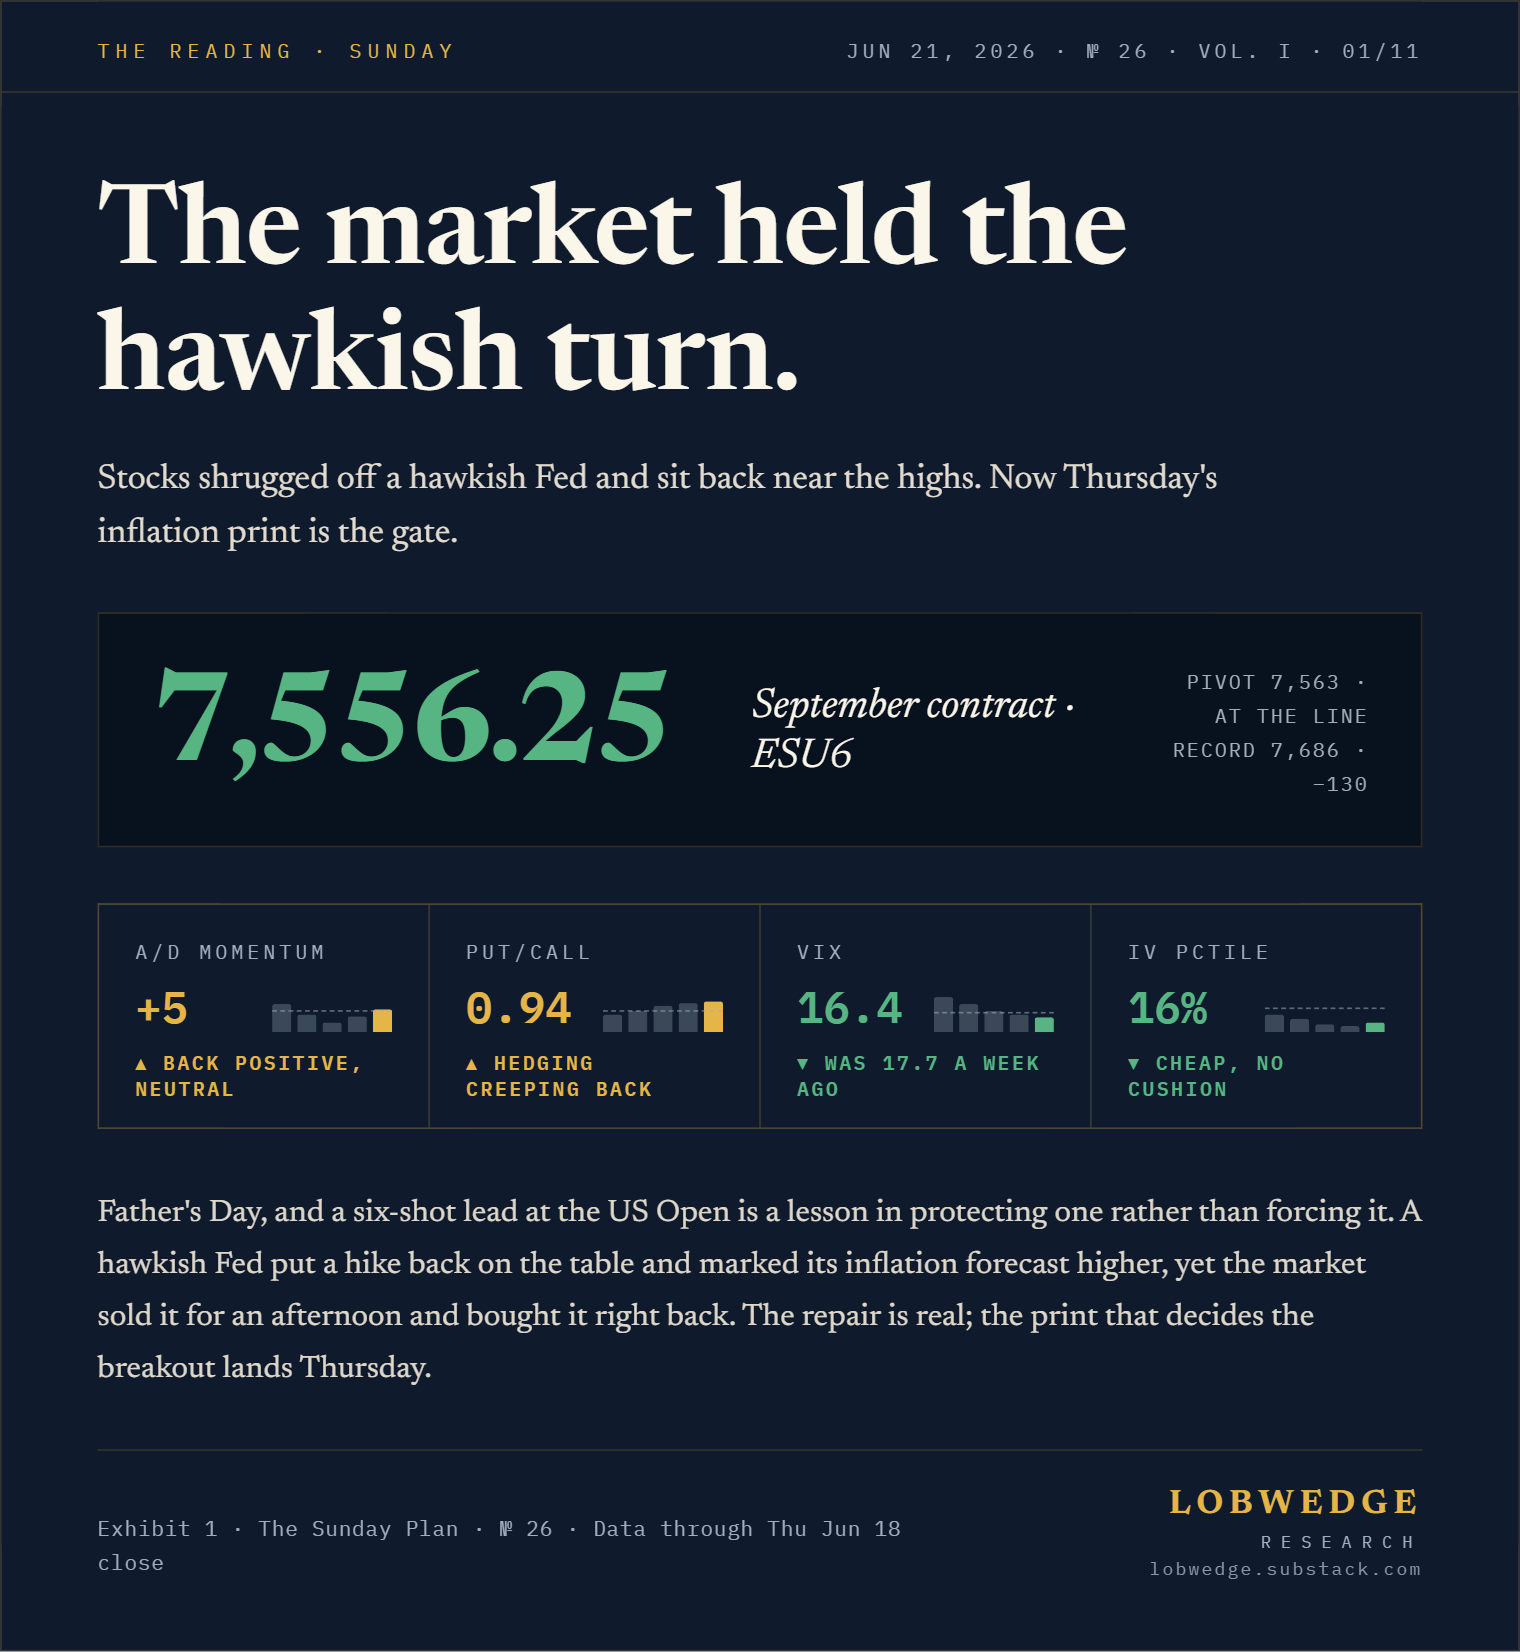
Last week we said to buy the dip at support and not chase into the Fed, and that’s exactly how it played. The market’s one real dip came on Wednesday’s FOMC selloff, and it bottomed within five points of the line we’d drawn, held, and reclaimed it by the close. The map nailed the low. What it didn’t do was break out: Monday tagged a fresh record near 7,648, got sold, and the week balanced under the highs while the Fed reset the board.
What changed: the Fed turned hawkish. Warsh’s first meeting held rates, but the projections flipped, the median policymaker now sees a hike this year, not a cut, and the inflation forecast got marked up to 3.6% from 2.7%. The market sold it for an afternoon, then bought it right back. That resilience is the constructive read, and it raises the stakes on one number.
That number is Thursday. Core PCE, the Fed’s preferred inflation gauge, lands June 25, the first reading since a Fed that just told you it’s worried. A soft print and the hawkish dots look stale. A hot one validates them and catches the market leaning the wrong way.
Three things sit underneath the price. First, leadership rotated back to where the year’s gains live: the chip complex, with memory and storage out front, and Micron reports Wednesday. Second, volatility went back to sleep, the VIX at 16.4 and premiums near the year’s low, cheap but no cushion. Third, the Iran calm wobbled, with Tehran declaring the Strait of Hormuz shut again Saturday even as tankers kept sailing through it. Oil is broken, but the tail that relights inflation is back on the table.
Constructive, then, but the breakout waits on Thursday.
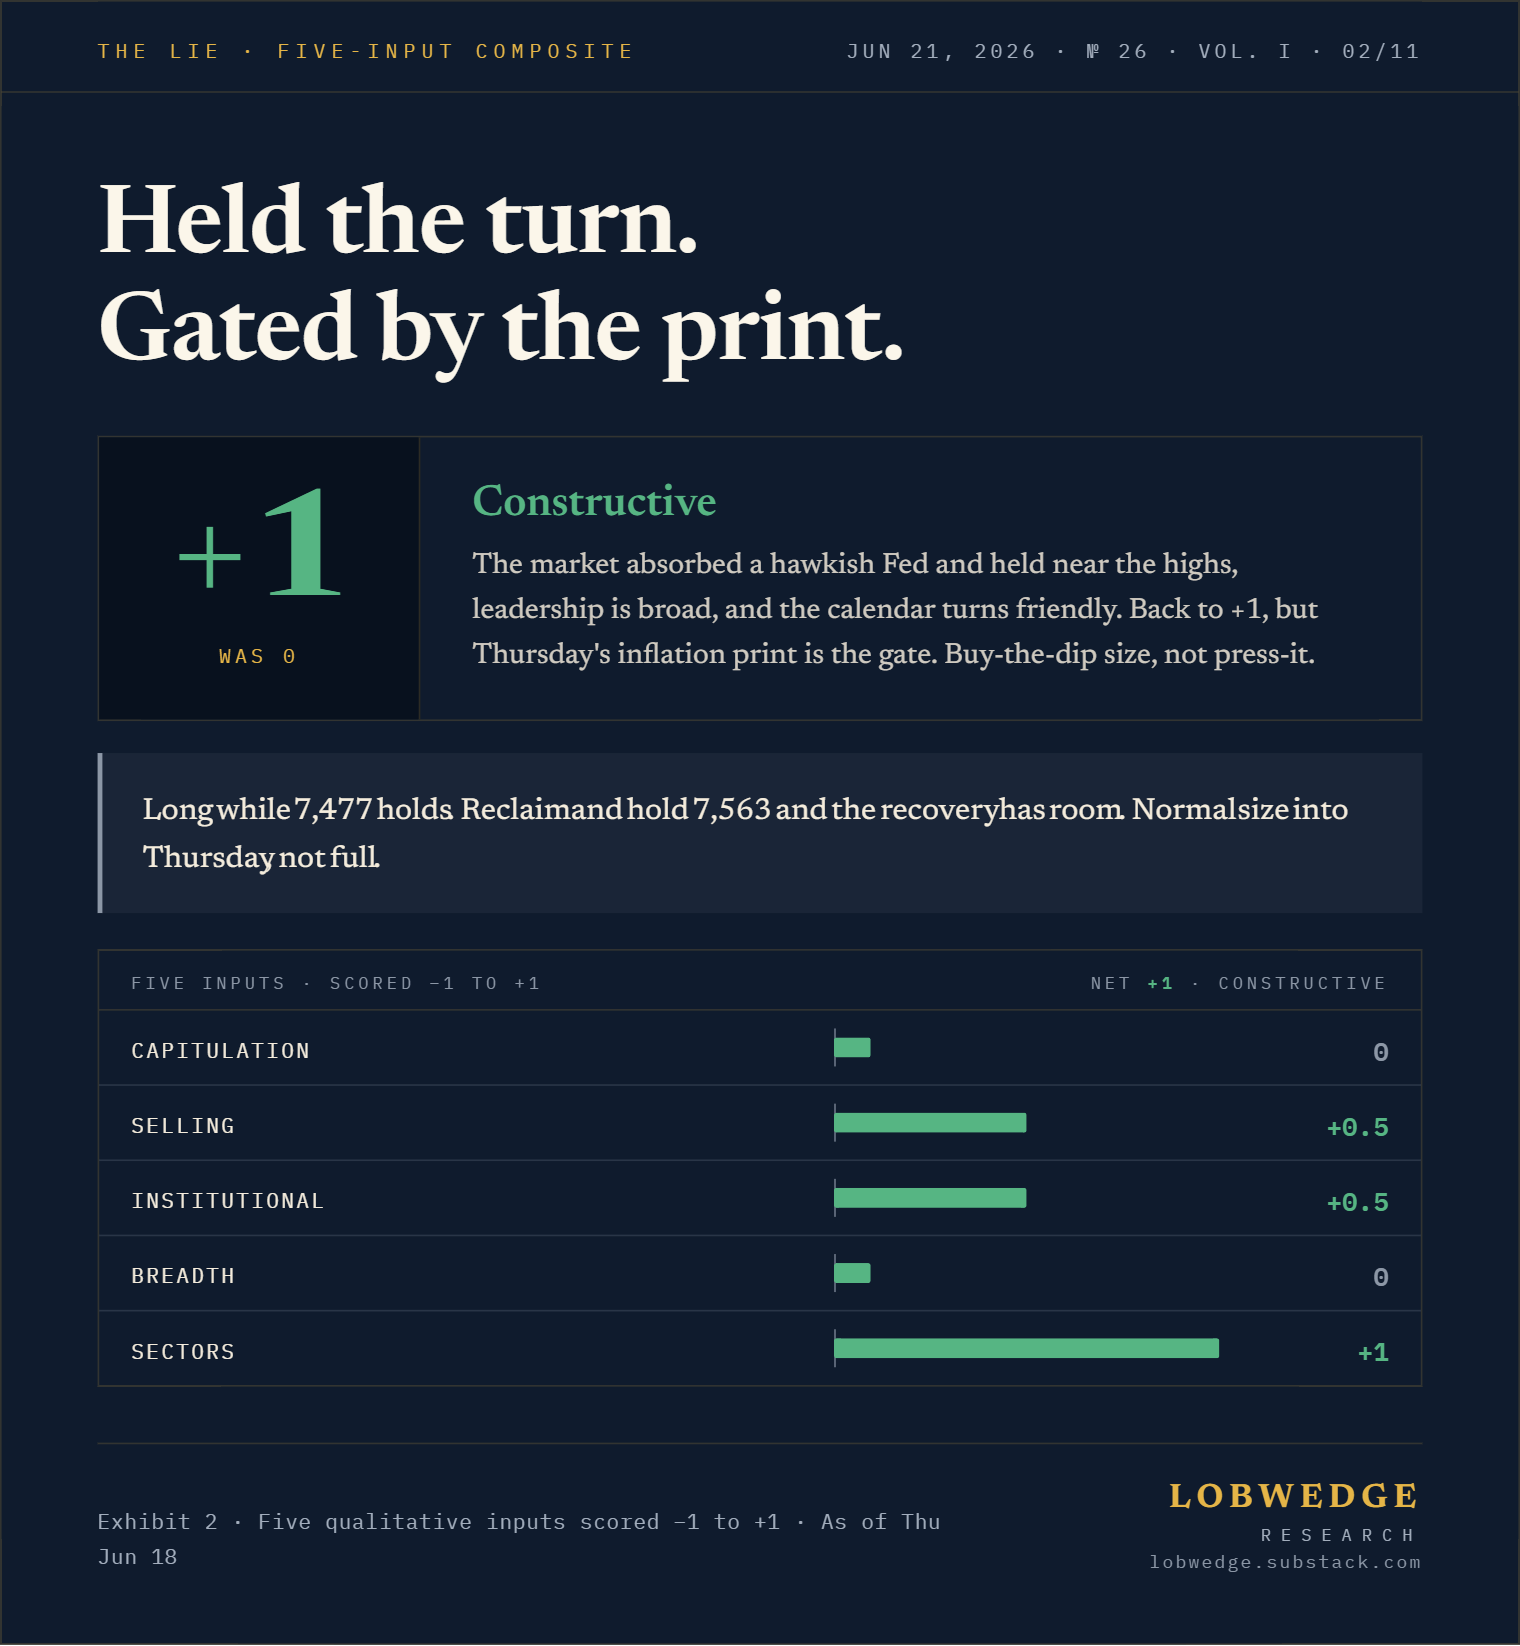
The Lie: +1 CONSTRUCTIVE. Was 0 neutral at the Fed, +1 the Sunday before. The market held the hawkish turn, leadership is broad, and the calendar turns friendly. The size stays measured into Thursday’s print.
One thing reframes the week. The groups in front aren’t the defensive names you see near a top, they’re the engines of the bull market: semiconductors, memory, power. A market putting those back in the lead right after a hawkish Fed isn’t bracing for the worst. The catch is that it all hangs on one number, and the crowd isn’t hedged for the wrong answer.
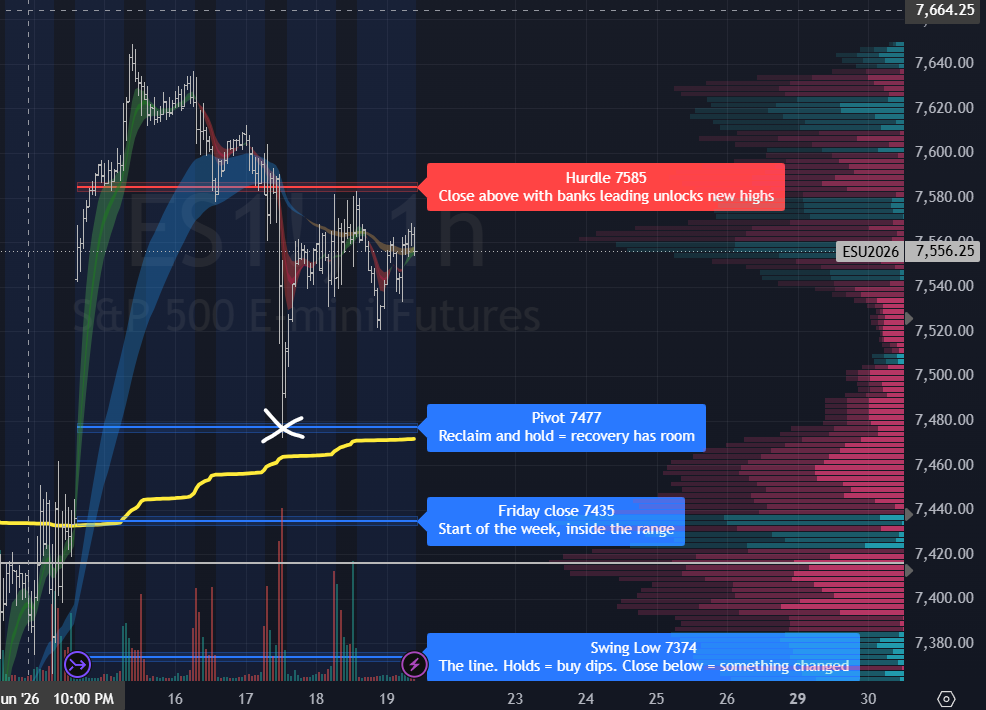
Below the fold: the level by level scorecard, the six levels that matter, the two trades we’re putting on, the model portfolio we’re introducing this week, and why the calendar finally works in our favor.
