

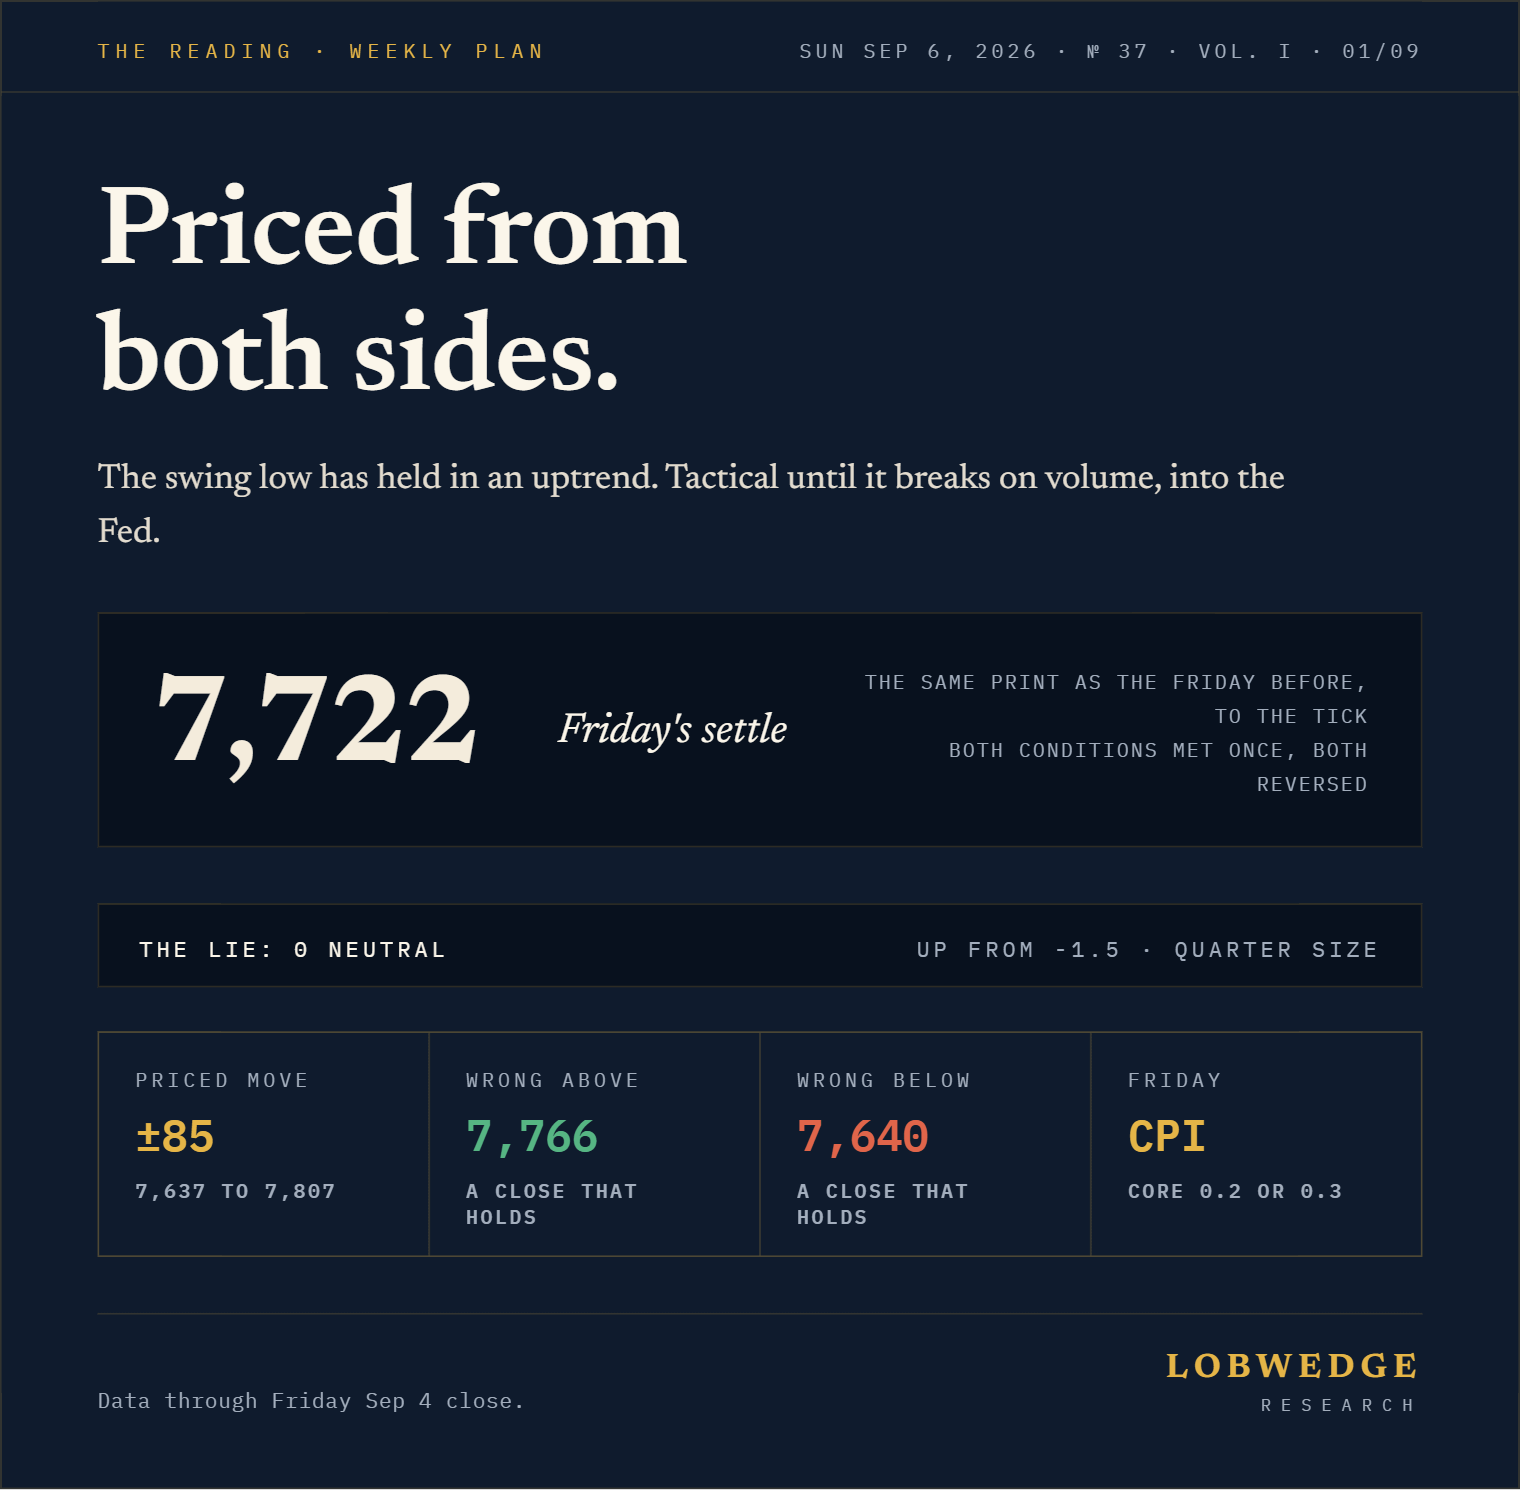
Both conditions we published for the week before the holiday were met, once each, and both reversed the next session. The score held at minus one and a half through both. The week settled at 7,722.00, the same print as the Friday before, to the tick. Holding was right.
Two rules change because of it. A score now needs two closes, or one close with room to spare that survives the next session, before it moves. And any entry that turns on with a close now carries a maximum fill price, because the midweek idea turned on at a close that had already run past both of its targets. That idea is void.
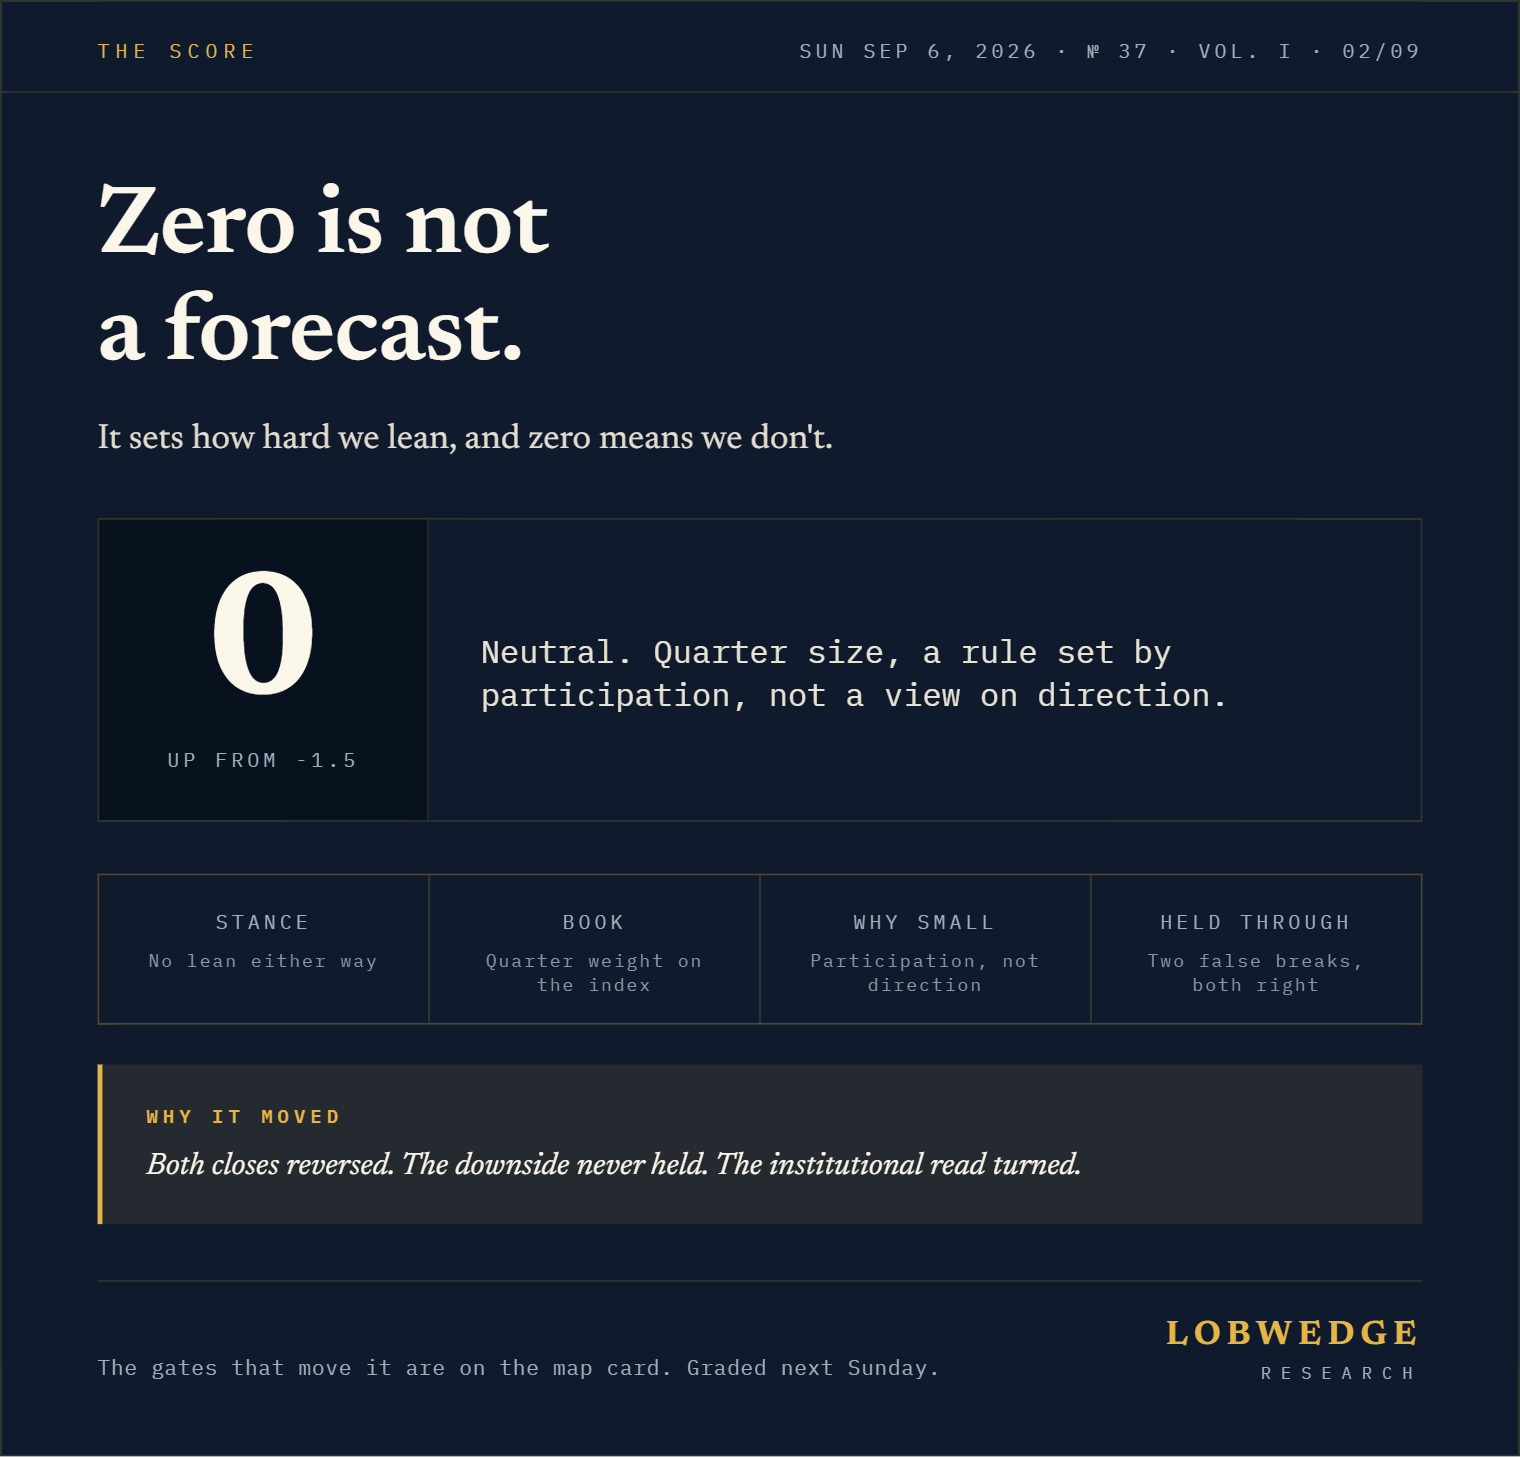
The Lie moves to 0 NEUTRAL, up from minus one and a half. Both closes reversed, the downside never held, and the institutional read turned. Zero isn’t a forecast. It sets how hard we lean, and zero means we don’t.
The read in one line. The swing low has held in an uptrend, twice. Until it breaks on volume, the week is tactical: a channel with an upward lean, traded at the edges, into the Fed on the 16th, the Bank of Japan on the 17th, the buyback blackout, and an IPO calendar that includes an Anthropic listing when it files.
Why the index is priced from both sides. Retail option traders are complacent: the equity put/call is 0.58, well under the line where hedging stops. Professionals are the opposite: more than three puts for every call on the futures chain, and hedge fund net exposure at its lowest in a year (sell-side prime data). When the sellers have already hedged, a bad headline finds no seller. When the unhedged group is retail, the first red session is fast and the recovery faster. A week with a strait attack, a global bond selloff and a payroll beat went nowhere.
What the last few weeks bought us. Eight of the thirteen levels we published were tested and all eight behaved as drawn, fourteen weeks running. The midweek call that the first support under the pivot would hold as Friday’s payroll floor held to within eight points. The score stayed put through two false breaks and was right both times. The three Sunday passes were right too. The rules did the work: quarter size set by participation, no pre-set orders at the edges, out on a close and never on a wick.
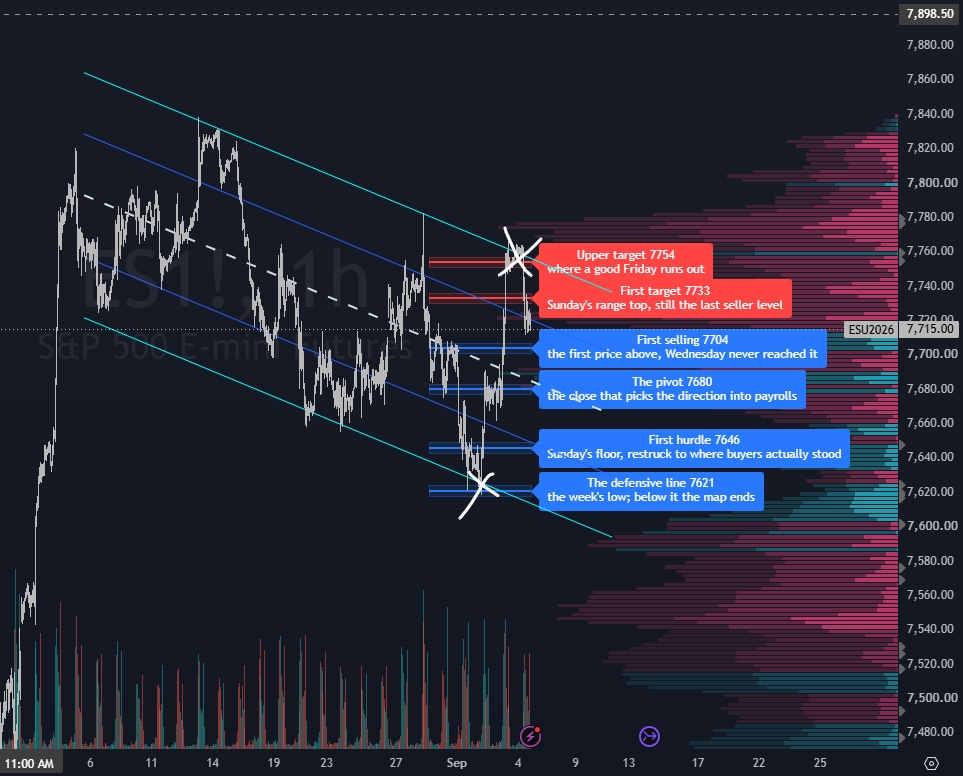
Below the fold, top down: the backdrop and the trends that outlast this week, what the crowd and the options market are set up for, the seven prices and the pivot, the one index lean we publish and why it prints under our own bar, two setups, the calendar, and what we do at Friday’s inflation print.
