

ES broke out of its range Monday and never closed back inside it. Tuesday ran to 7,897.50 and the S&P 500 printed its first record close since August. Thursday dipped on the 30-year auction and was bought before the close. Friday settled 7,866, up 90 on the week.
The 10-year touched its highest yield since 2002 midweek, then eased to about 5.24% after a strong auction. Stocks shrugged it off for the second week in a row. That’s the market telling you 5% yields are a headline now, not a reason to sell.
The crowd still isn’t chasing. AAII bears fell to 39% from 46.5%, but put buying hasn’t dried up and VIX closed at 14.84. Hedge funds aren’t in it either. Fundamental long/short funds are running about 46% net long, their lowest since the April 2025 lows, while the S&P sits at a record. A rally this many people doubt still has buyers waiting on the sidelines. This week’s catalysts each answer one question. The banks report Tuesday and tell us whether the rally can broaden. CPI on Wednesday is a vote on December’s hike. TSMC (TSM) on Thursday is a vote on the AI buildout.
The plan’s simple: stay long, ride the trend, and buy the dip at the line instead of chasing the open.
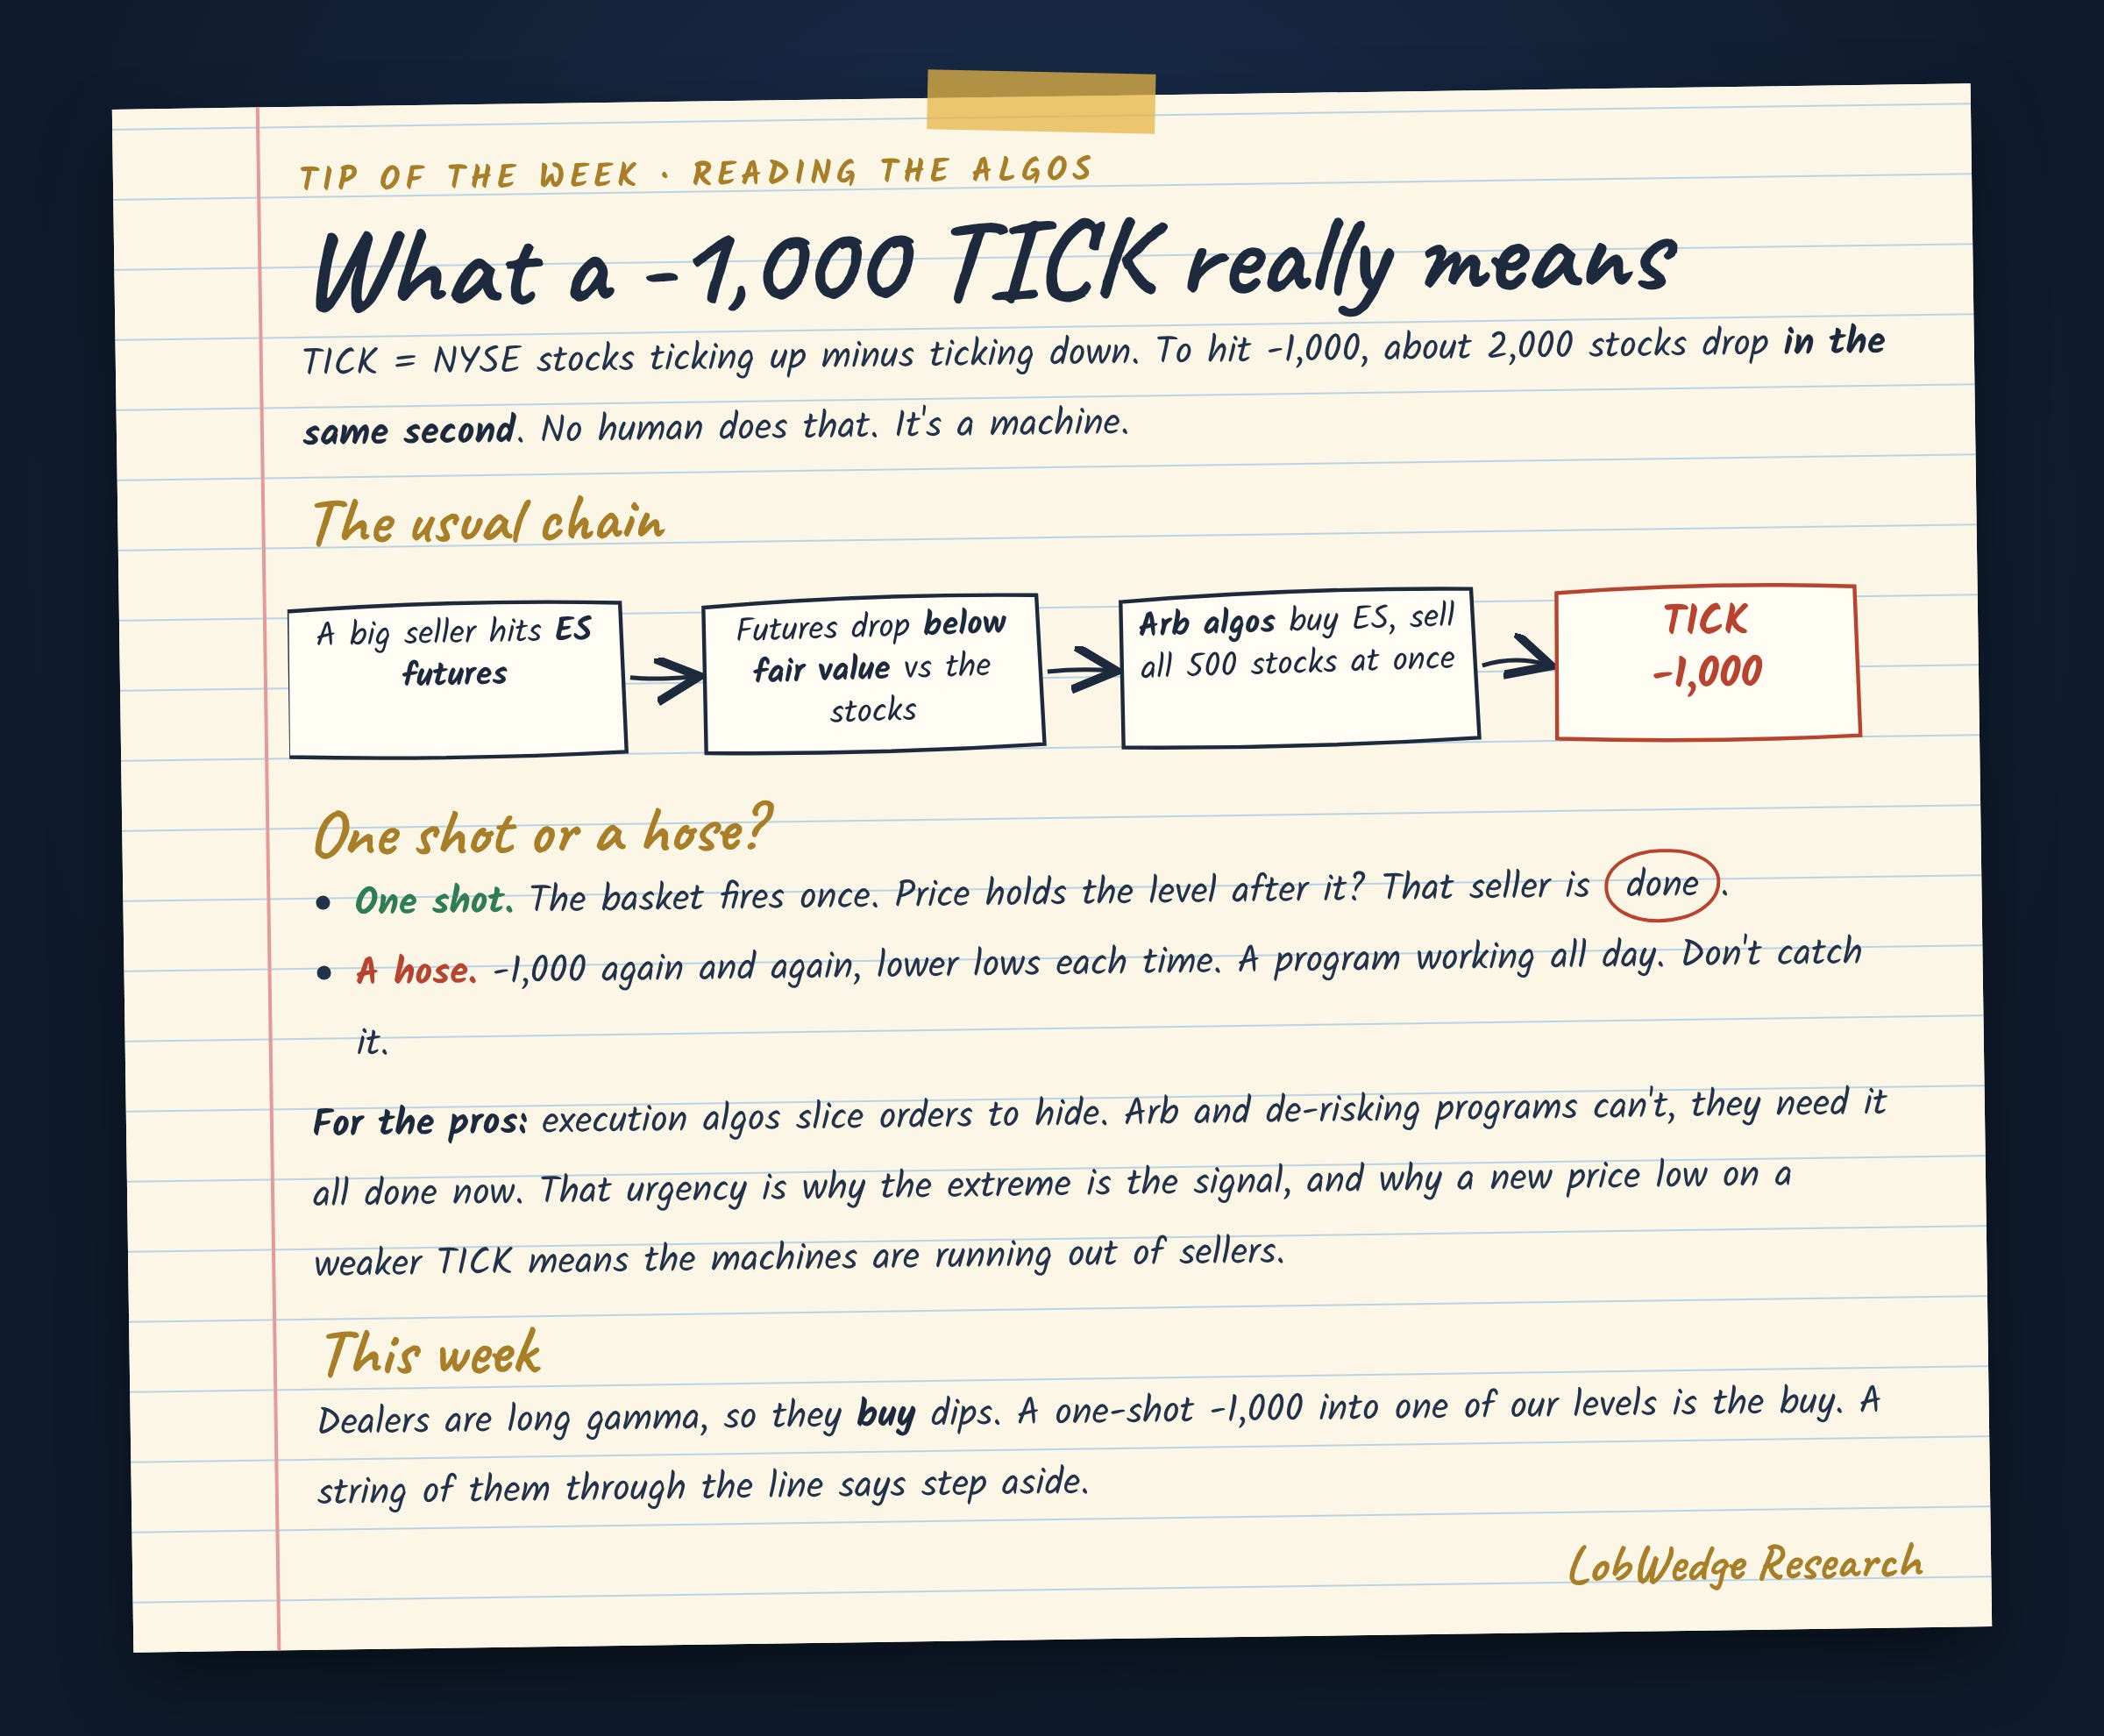
Free tip of the week: reading the algos. A -1,000 on the NYSE TICK is a machine’s fingerprint. Here’s which machine, and what to do when you see it.
Below the line: last week graded on the map, the big picture into the midterms, this week’s levels and odds, the plan, the setups, and what each catalyst means for your book.
