

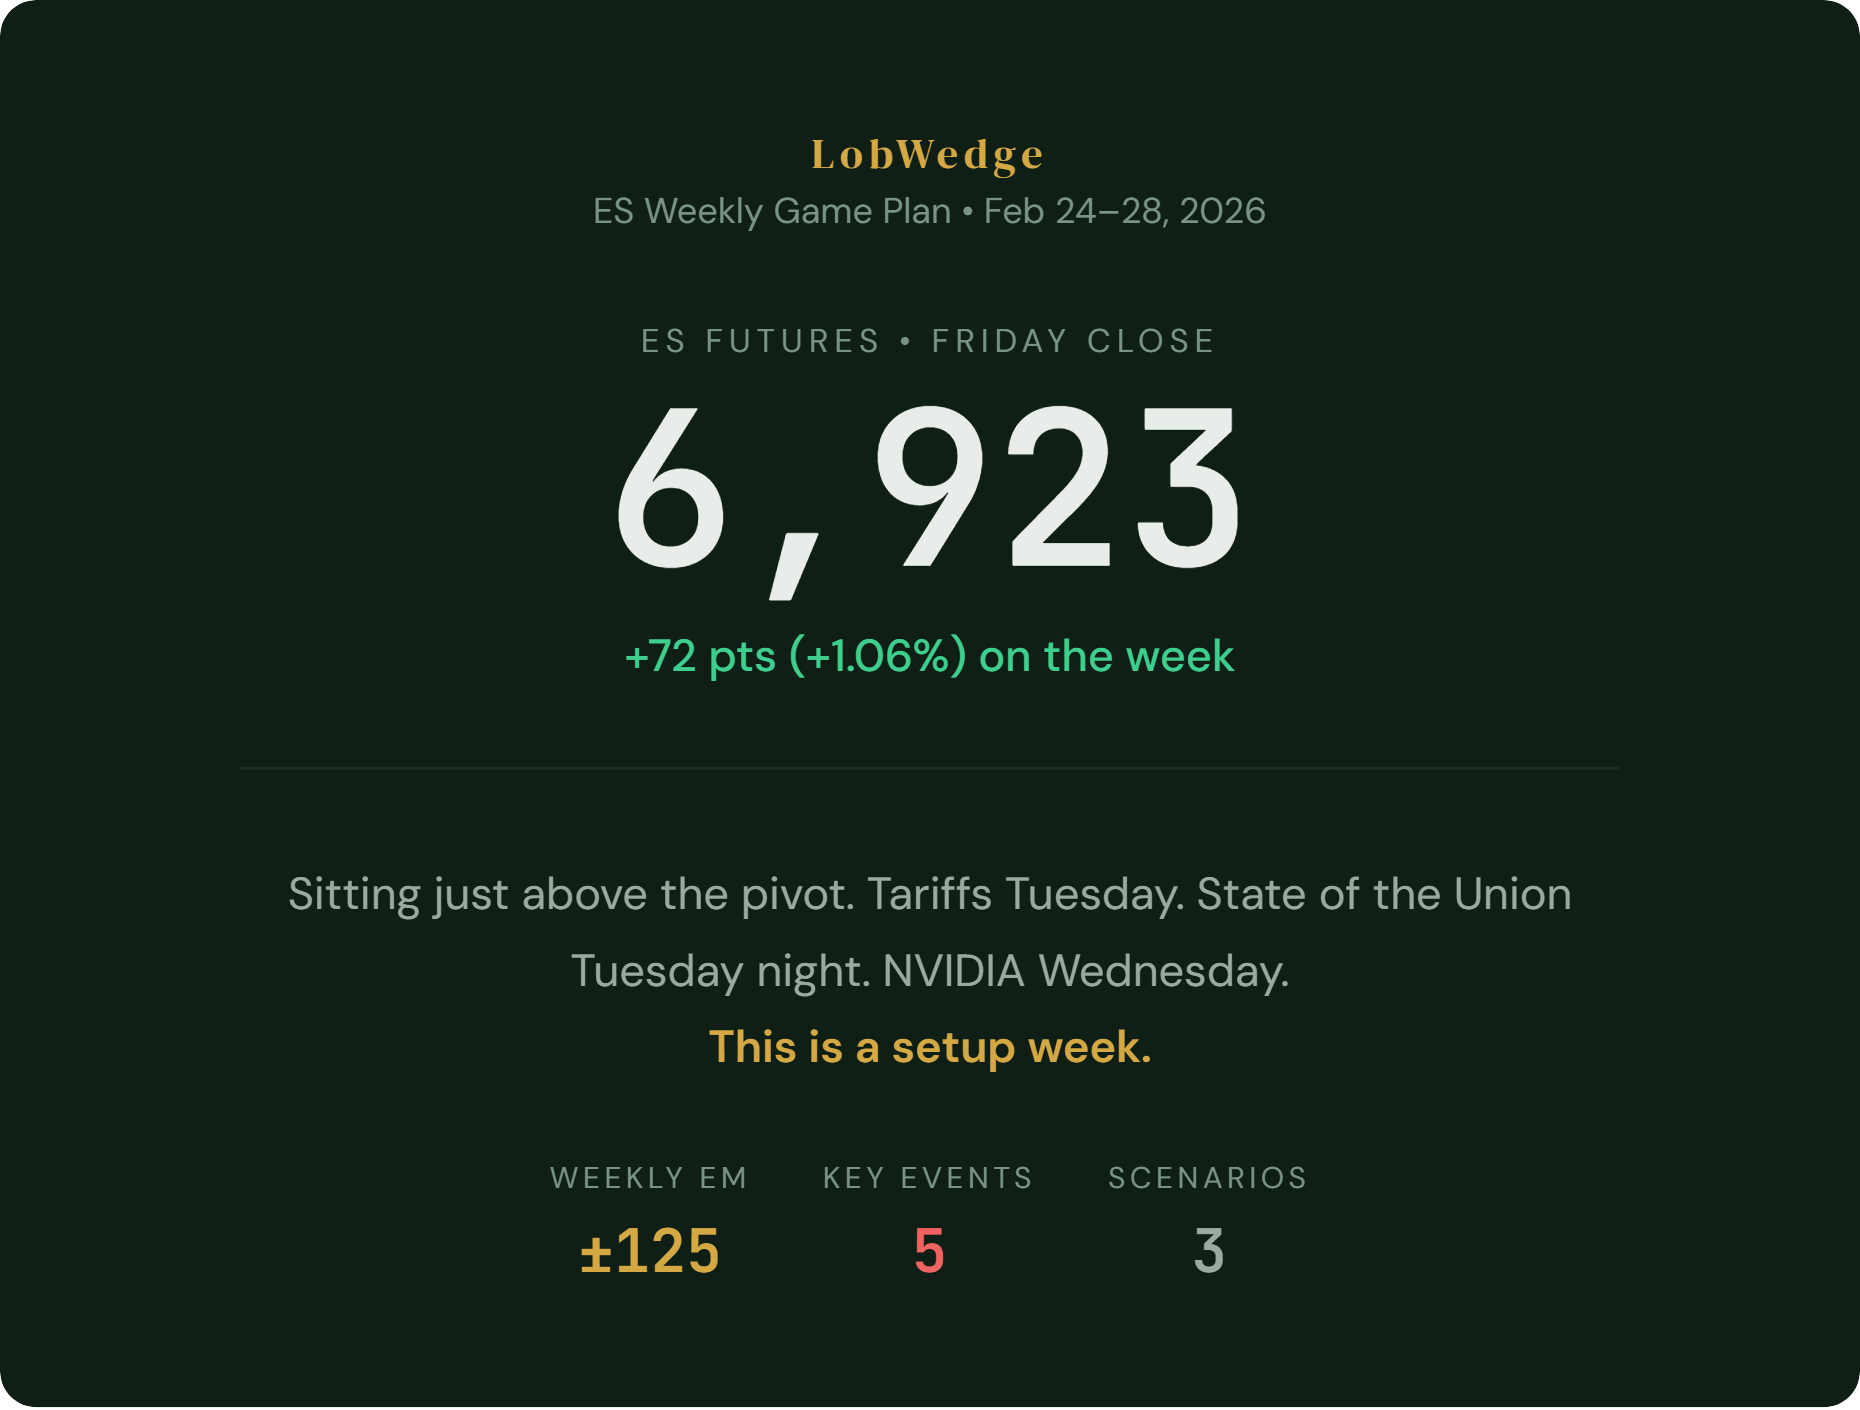
Last week’s plan worked.
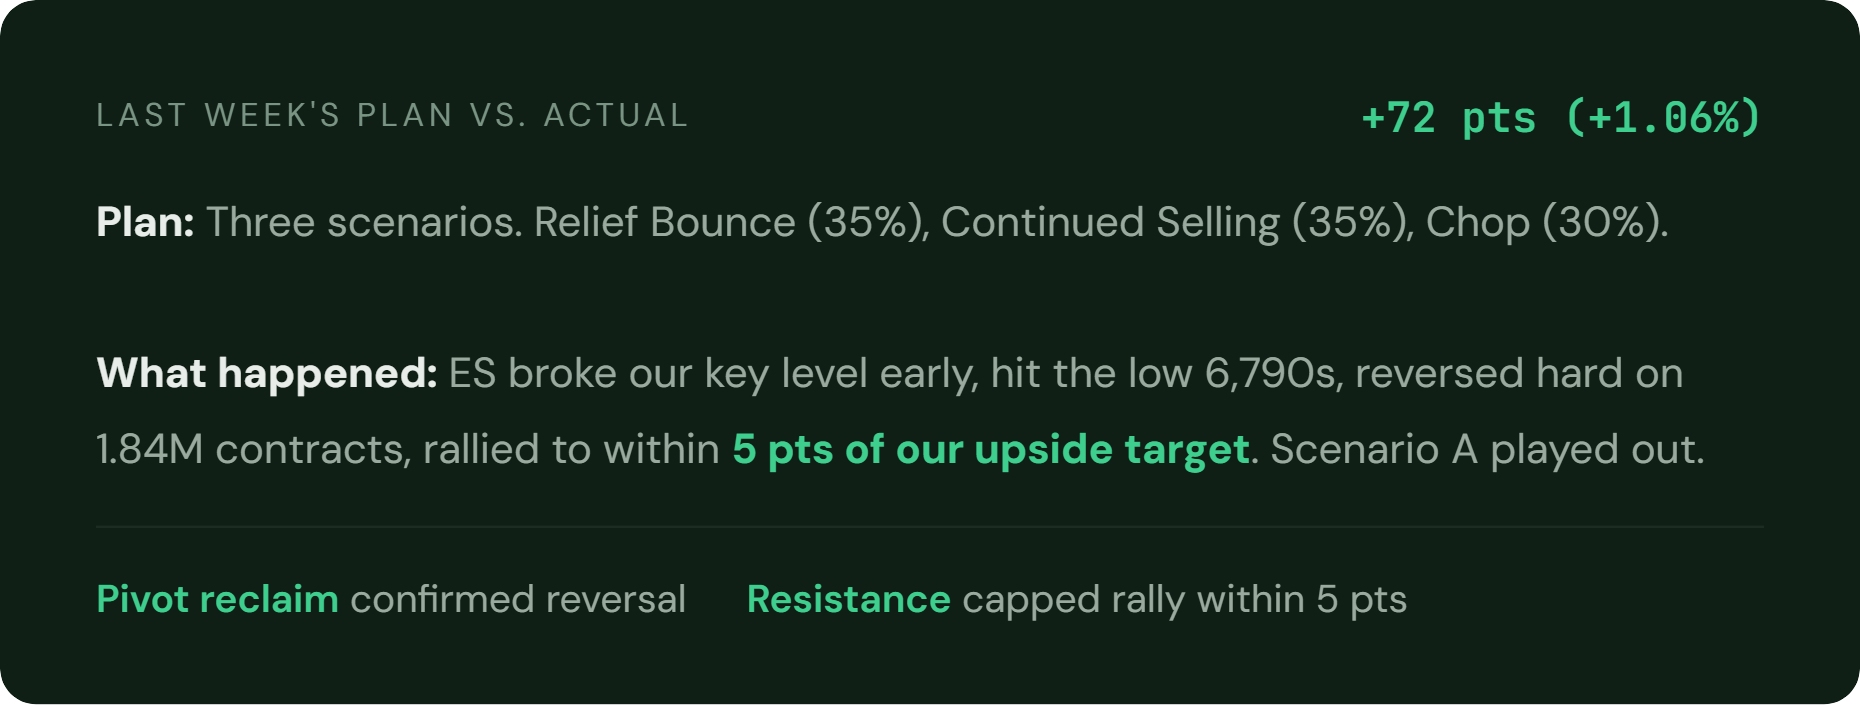
We laid out three scenarios last Sunday. ES broke our key level early in the week, hit the low 6,790s, then reversed hard on 1.84 million contracts and rallied straight to within 5 points of our upside target. Scenario A played out exactly as mapped.
The levels worked. The framework worked. Now let’s do it again.
Calm surface, chaos underneath
The S&P 500 is up less than 1% this year. The spread between its YTD high and low is just 2.7%, the tightest start to a year since 1966.
Sounds like nothing is happening. Look closer.
Stock-to-stock correlation just hit 0.13, near record lows. Massive moves everywhere. They’re just canceling each other out at the index level. The S&P looks flat because it’s a tug-of-war, not because nothing is moving.
This week’s plan maps where the opportunities and the risks actually are.
The full game plan: key levels, three scenarios with trades, NVIDIA setup, SOTU breakdown, expected moves, options setups, and positioning analysis. All below for paid subscribers.
Where is ES right now?
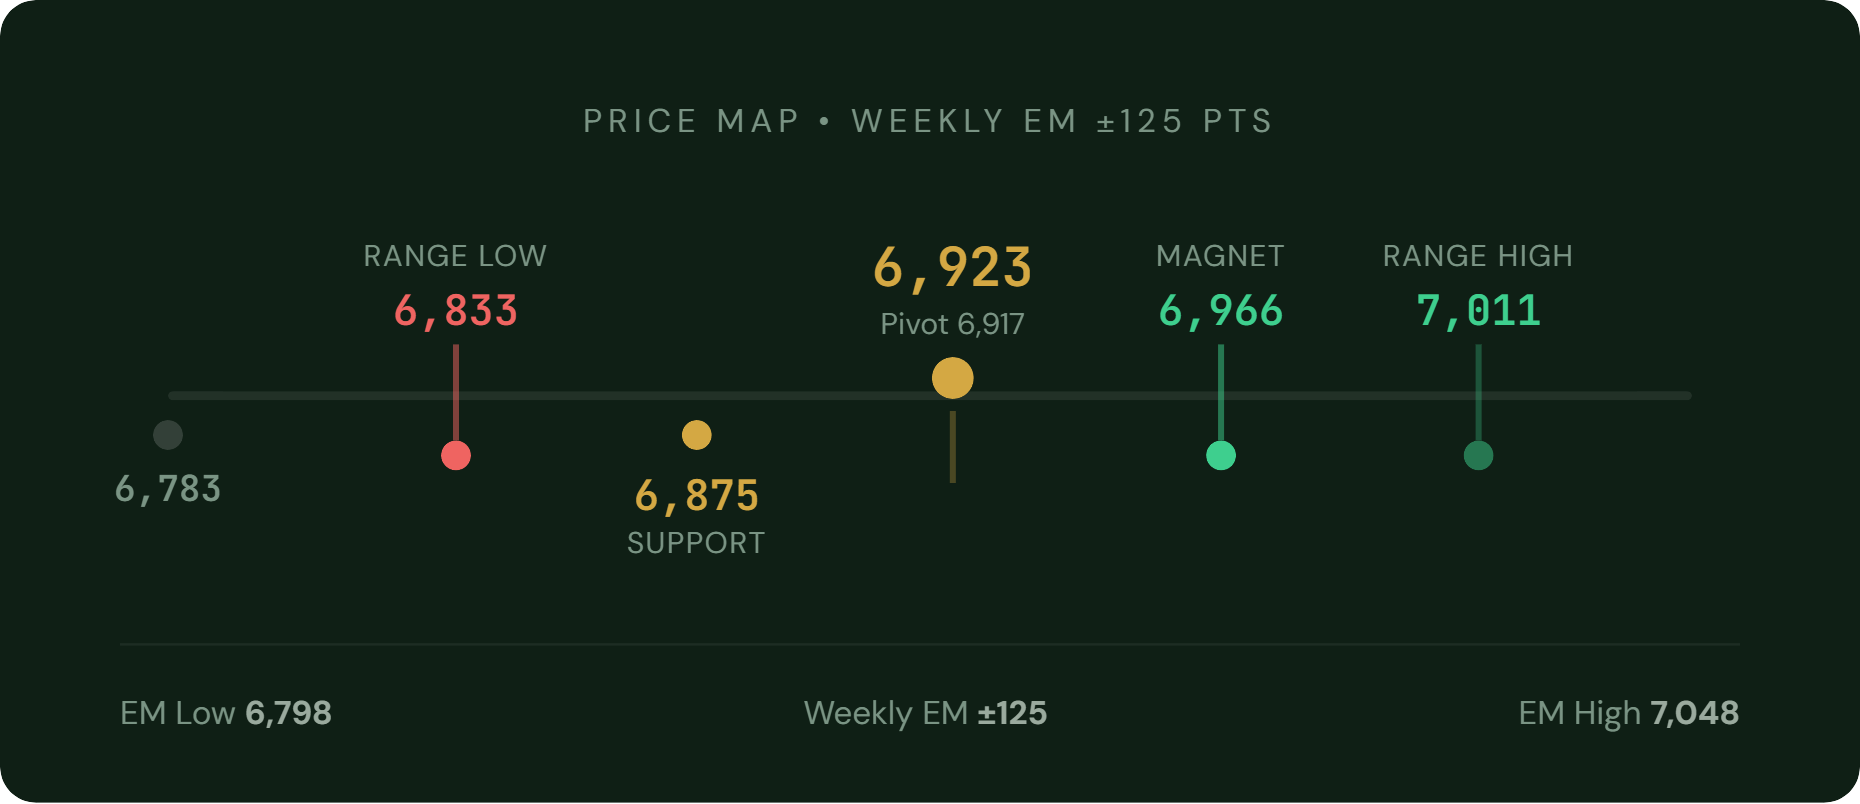
ES at 6,923 is sitting just above the week’s pivot. The magnet is above. The line in the sand is below. The weekly expected move is ±125 points, giving a range of 6,798 to 7,048.
Six levels define the week. They’re all in the price map and the levels table below.
The structure: coiled spring meets catalyst week
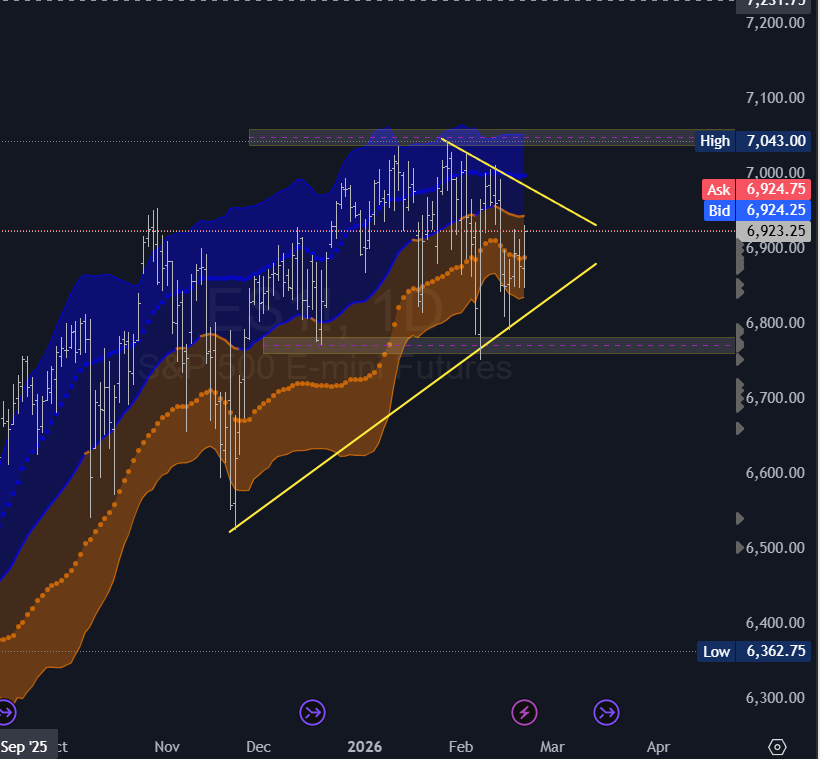
This is the chart heading into the week.
Price is being squeezed. There’s a descending resistance line off the 7,043 February high pressing down, and a rising support line off the December low pushing up. That wedge is narrowing every day. Something has to give. And three catalysts in 48 hours is probably what gives it.
The volume structure (where the most trading has happened over the past several weeks) is concentrated in the 6,900-7,000 zone. That’s the magnet. Price keeps getting pulled back to this area like gravity. Our 6,966 fair value level sits right in the heart of it.
Below, the 6,800 zone is clearly defended. That horizontal support band lines up with the rising trendline from December and with our 6,833 range low. If both of those break on the same day, it’s a different market. But so far buyers have shown up every single time price has tested that area.
ES is coiled. The breakout will be violent because the compression has been building for weeks. Tariffs Tuesday morning, SOTU Tuesday night, NVDA Wednesday. Don’t predict. Let the levels tell you.
The tariff situation: what actually happened
Here’s the short version. SCOTUS struck down the IEEPA tariffs Friday afternoon. Within hours, the administration pivoted to Section 122 of the Trade Act of 1974 and announced a 10% global tariff. By Saturday, that was raised to 15%, the legal maximum under that authority. These new tariffs take effect Tuesday at 12:01am ET.
The net effect? Peak tariff rates actually came down. Under IEEPA, rates ranged from 10% to 50% depending on the country. The new 15% flat rate is lower than what most imports were facing. There are exemptions too (certain minerals, pharma, vehicles, electronics), so it’s not quite as “global” as the headline suggests.
But here’s the thing. This is all weekend news. Futures reopen Sunday evening. Monday’s session is the first time markets get to react. Gap risk is real.
If ES holds above the pivot Monday, the magnet level is in play. If it fades below, we’re looking at support and the bear scenario starts building. Don’t be a hero in the first 30 minutes.
Tuesday night: State of the Union is bigger than usual
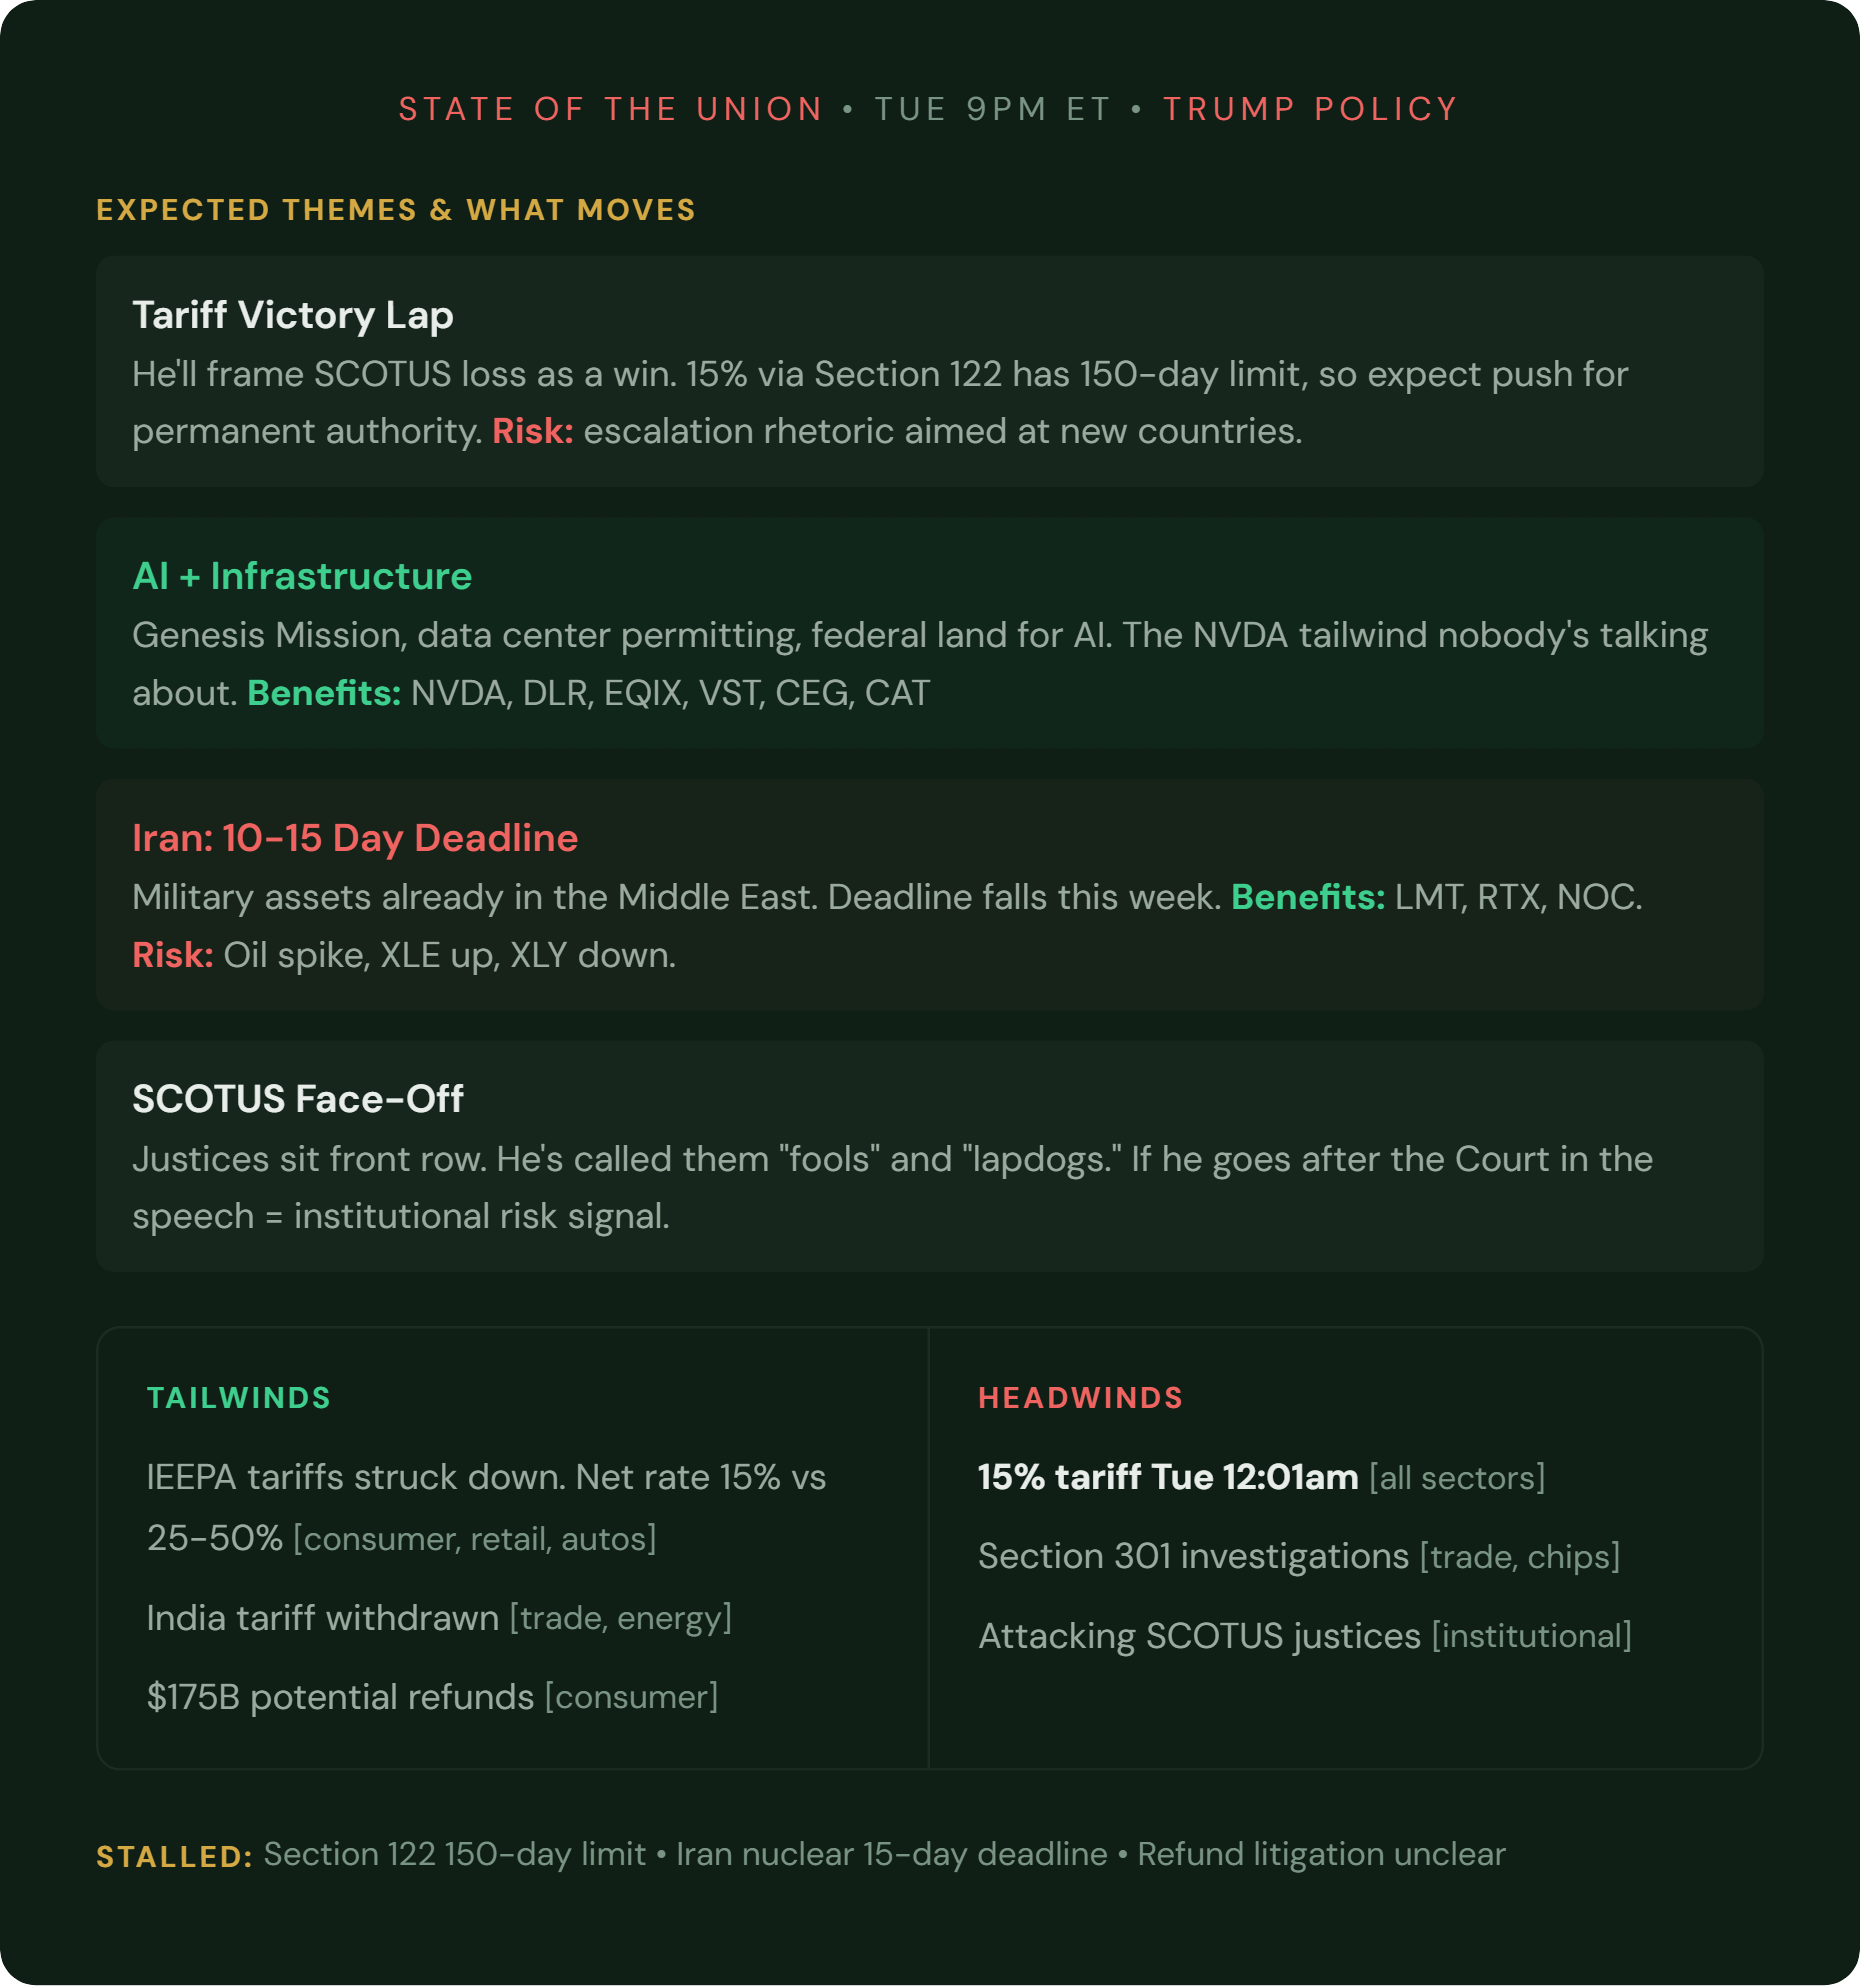
This isn’t a normal SOTU. It lands after the SCOTUS tariff ruling, ahead of NVIDIA, with 60% disapproval and midterms in November. Trump has every reason to go big.
Expected themes and what moves:
Tariff victory lap. He’ll frame the SCOTUS loss as a win. “We got tariffs through a better legal path, and they’re lower for consumers.” Section 122 is temporary with a 150-day limit, so expect him to push Congress for permanent authority. Watch for escalation rhetoric aimed at specific countries. If he signals broader tariffs or new targets beyond 15%, risk-off. If he frames 15% as the ceiling, relief.
AI and infrastructure. His administration has been aggressively pro-AI. The Genesis Mission, data center permitting on federal lands, preempting state AI regulations. Expect him to tout AI investment and American energy powering data centers. This is the NVDA tailwind nobody is talking about. If he announces new AI infrastructure commitments Tuesday night, NVDA reports into a friendlier narrative Wednesday. Benefits: NVDA, data center REITs (DLR, EQIX), energy/utilities (VST, CEG, NRG), infrastructure (CAT, URI).
Iran. He said the world will know in “10 to 15 days” whether he orders strikes. That deadline falls this week. Military assets are already in the Middle East. If he escalates rhetoric Tuesday night, defense names move Wednesday morning. Benefits: LMT, RTX, NOC, GD. Risk: Energy prices spike, which pressures consumer discretionary.
Immigration and DOGE. Red meat for the base, but unlikely to move markets unless he drops something on government spending or labor that nobody saw coming. File this under “watch, don’t trade.”
What to watch for: The SCOTUS justices will be sitting front and center. Trump has already called them “fools” and “lapdogs.” If he goes after the Court directly in the speech, that’s an institutional risk signal. Markets don’t like uncertainty about the rule of law. Watch for any hint of non-compliance with the ruling.
Three scenarios for the week
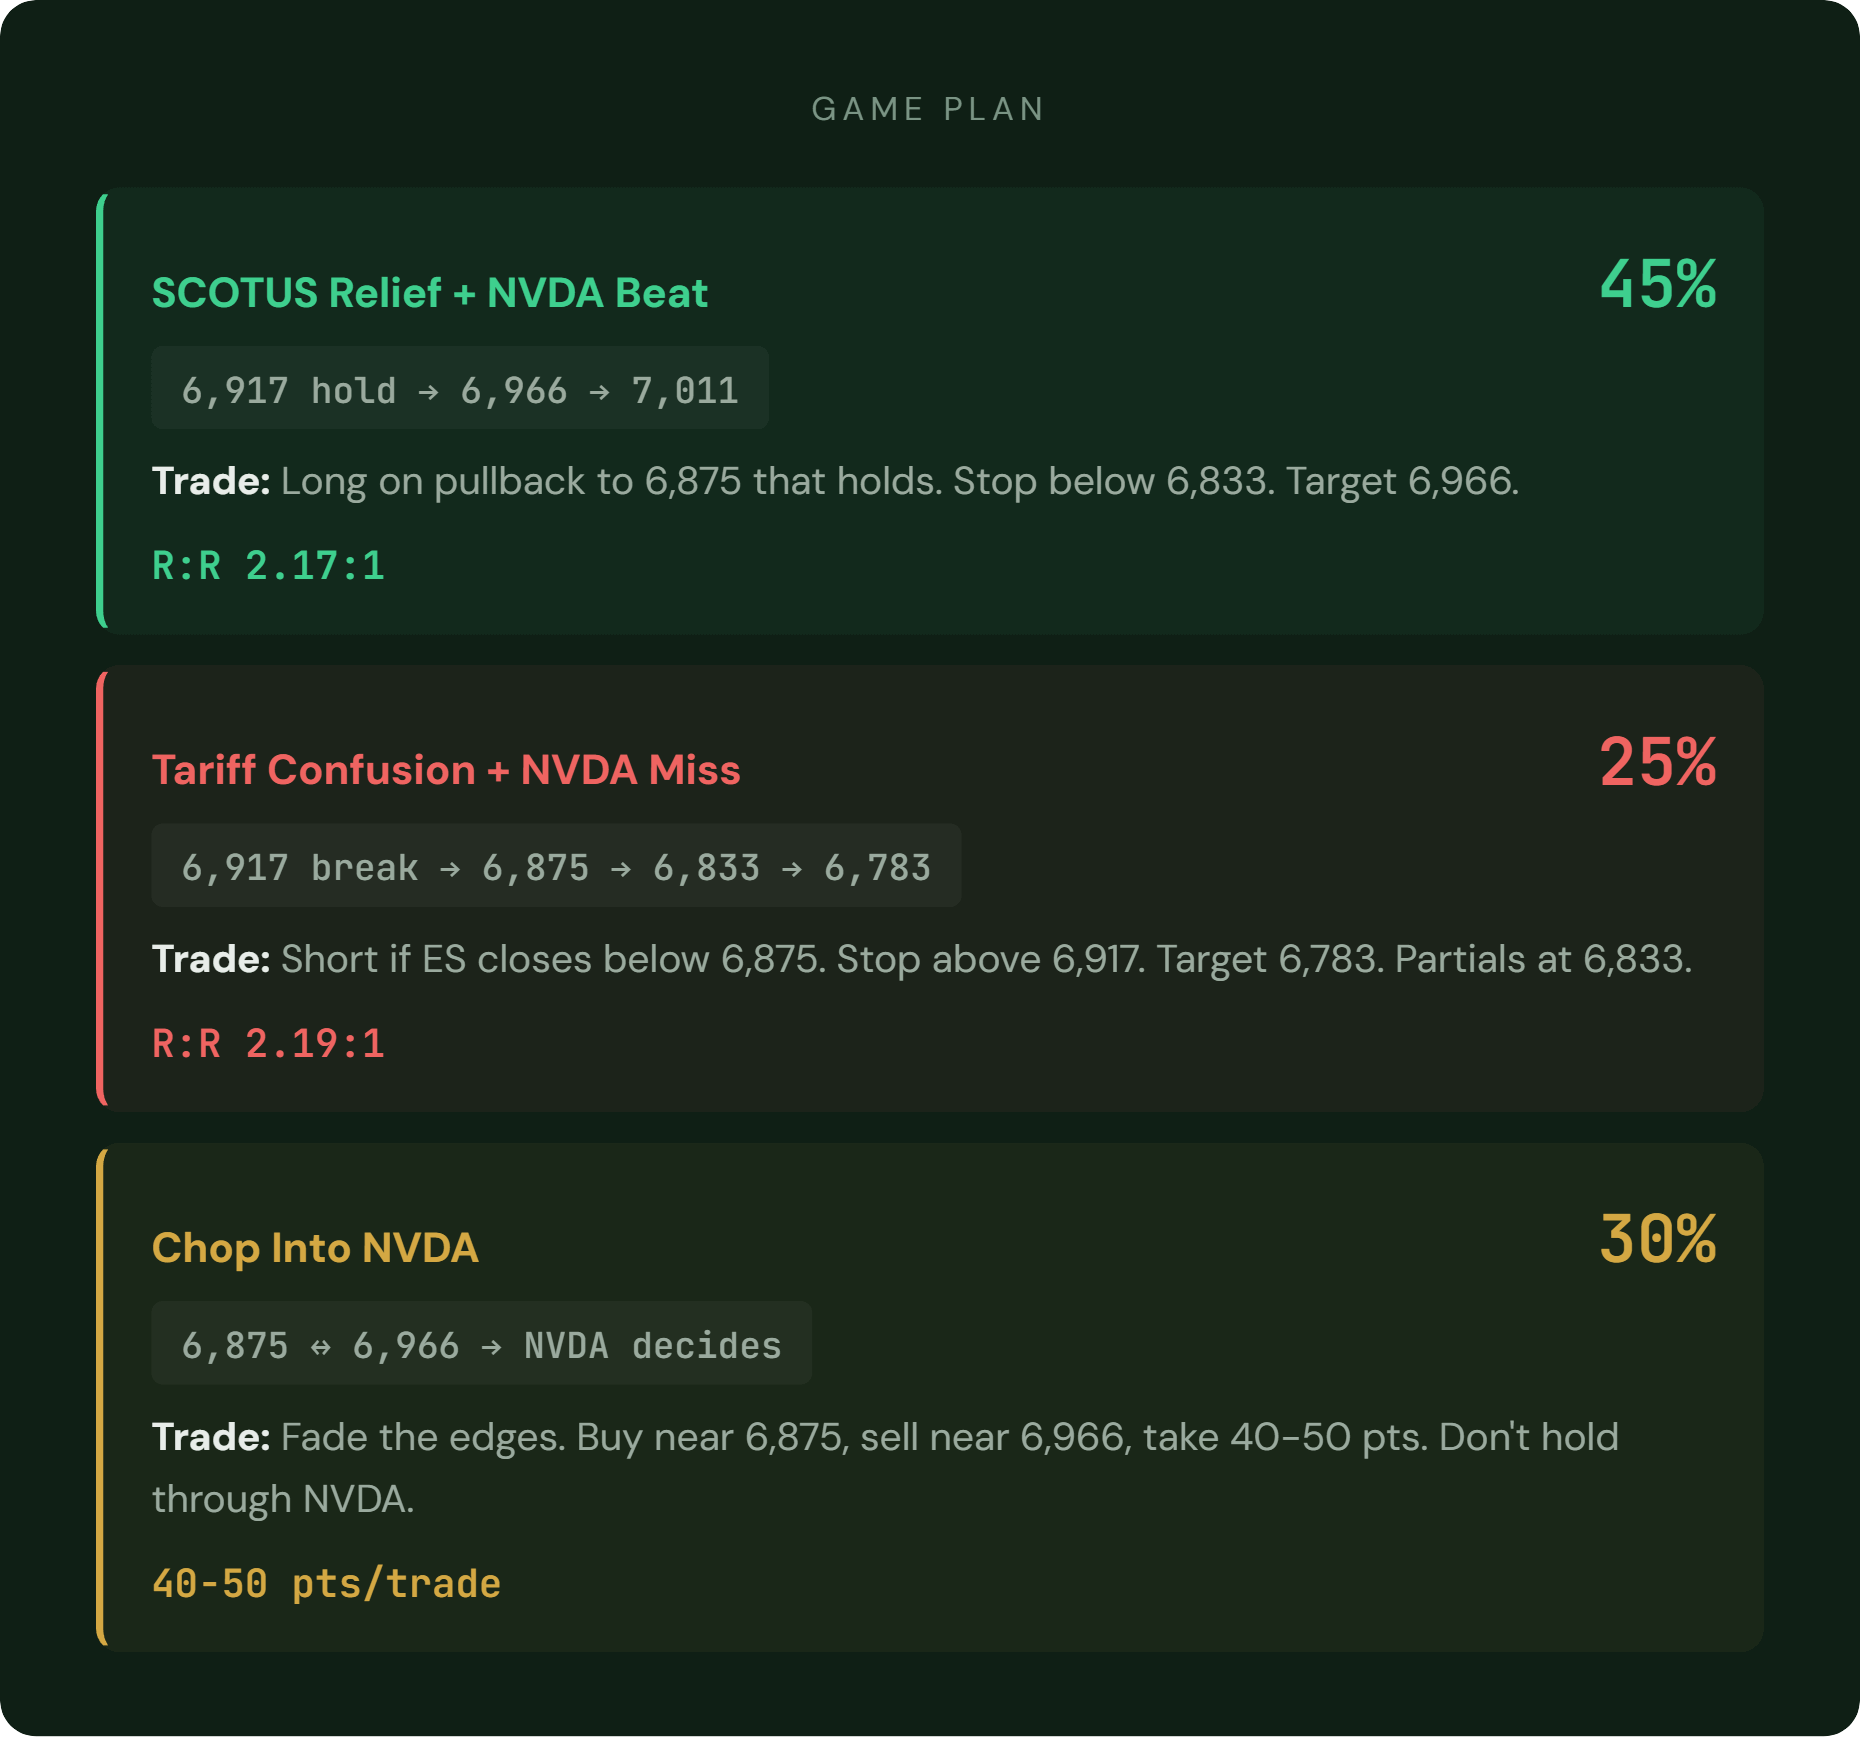
Scenario A: SCOTUS Relief + NVDA Beat (45%) The wedge breaks up. Market treats lower tariff rate as net positive. ES holds above the pivot into Wednesday. NVDA beats, Huang talks Blackwell demand. Post-NVDA gap pulls to the magnet level.
Trade: Long on pullback to support that holds. Stop below the range low. Target the magnet. R:R 2.17:1. Stretch to the range high if the magnet clears.
Clues: Higher lows Mon/Tue. Dips bought at the pivot. Monday gap holds. Descending trendline from 7,043 gives way.
Scenario B: Tariff Confusion + NVDA Miss (25%) The wedge breaks down. Monday gap down on tariff reality. SOTU escalates rhetoric or threatens new tariffs. NVDA disappoints or guides weak on chip exports. The rising trendline from December breaks.
Trade: Short if ES closes below support. Stop above pivot. Target lower support. Partials at range low. R:R 2.19:1.
Clues: Lower highs Mon/Tue. Monday gap not filled. Bounces sold. Rising support trendline snaps.
Scenario C: Chop Into NVDA (30%) The wedge holds. Market digests headlines but can’t commit. ES chops between support and the magnet Mon through Wed morning. Everyone waits for Jensen.
Trade: Fade the edges. Buy near support, sell near the magnet, take 40-50 pts. Don’t hold through NVDA. Seriously. Don’t.
Clues: Failed breakouts both ways. Time near pivot. Volume dries up ahead of Wednesday.
Key levels
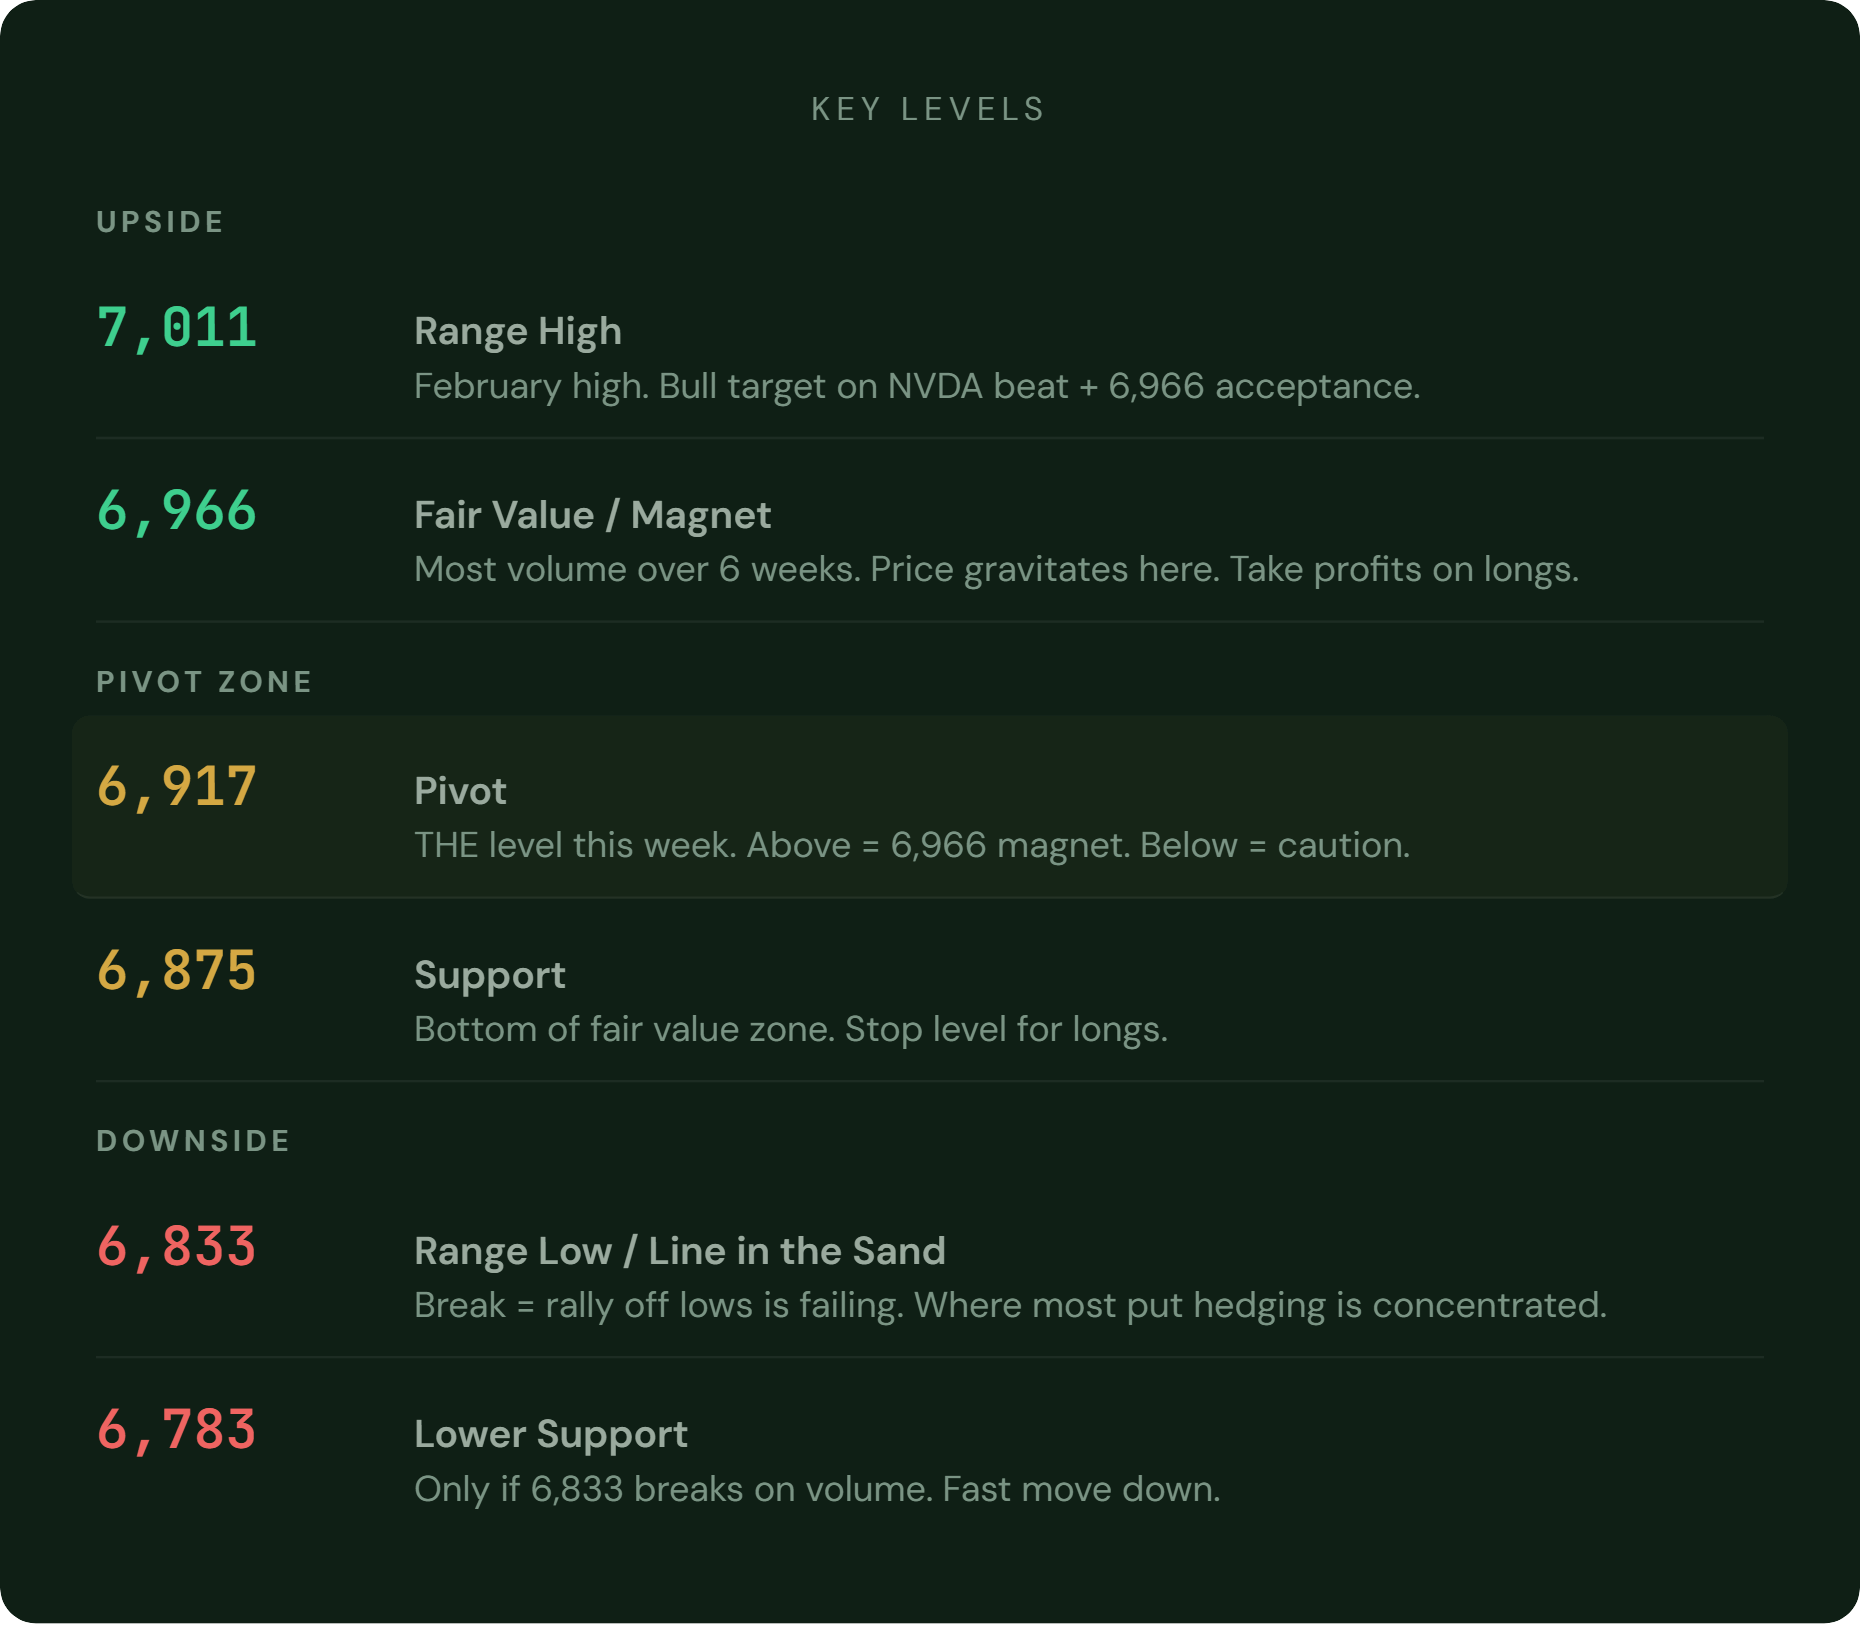
All six levels with names, conviction ratings, and how to trade each one. These are the numbers that matter this week. Export them to TradingView using the string at the bottom of this post.
Expected move + positioning: the spring is loaded
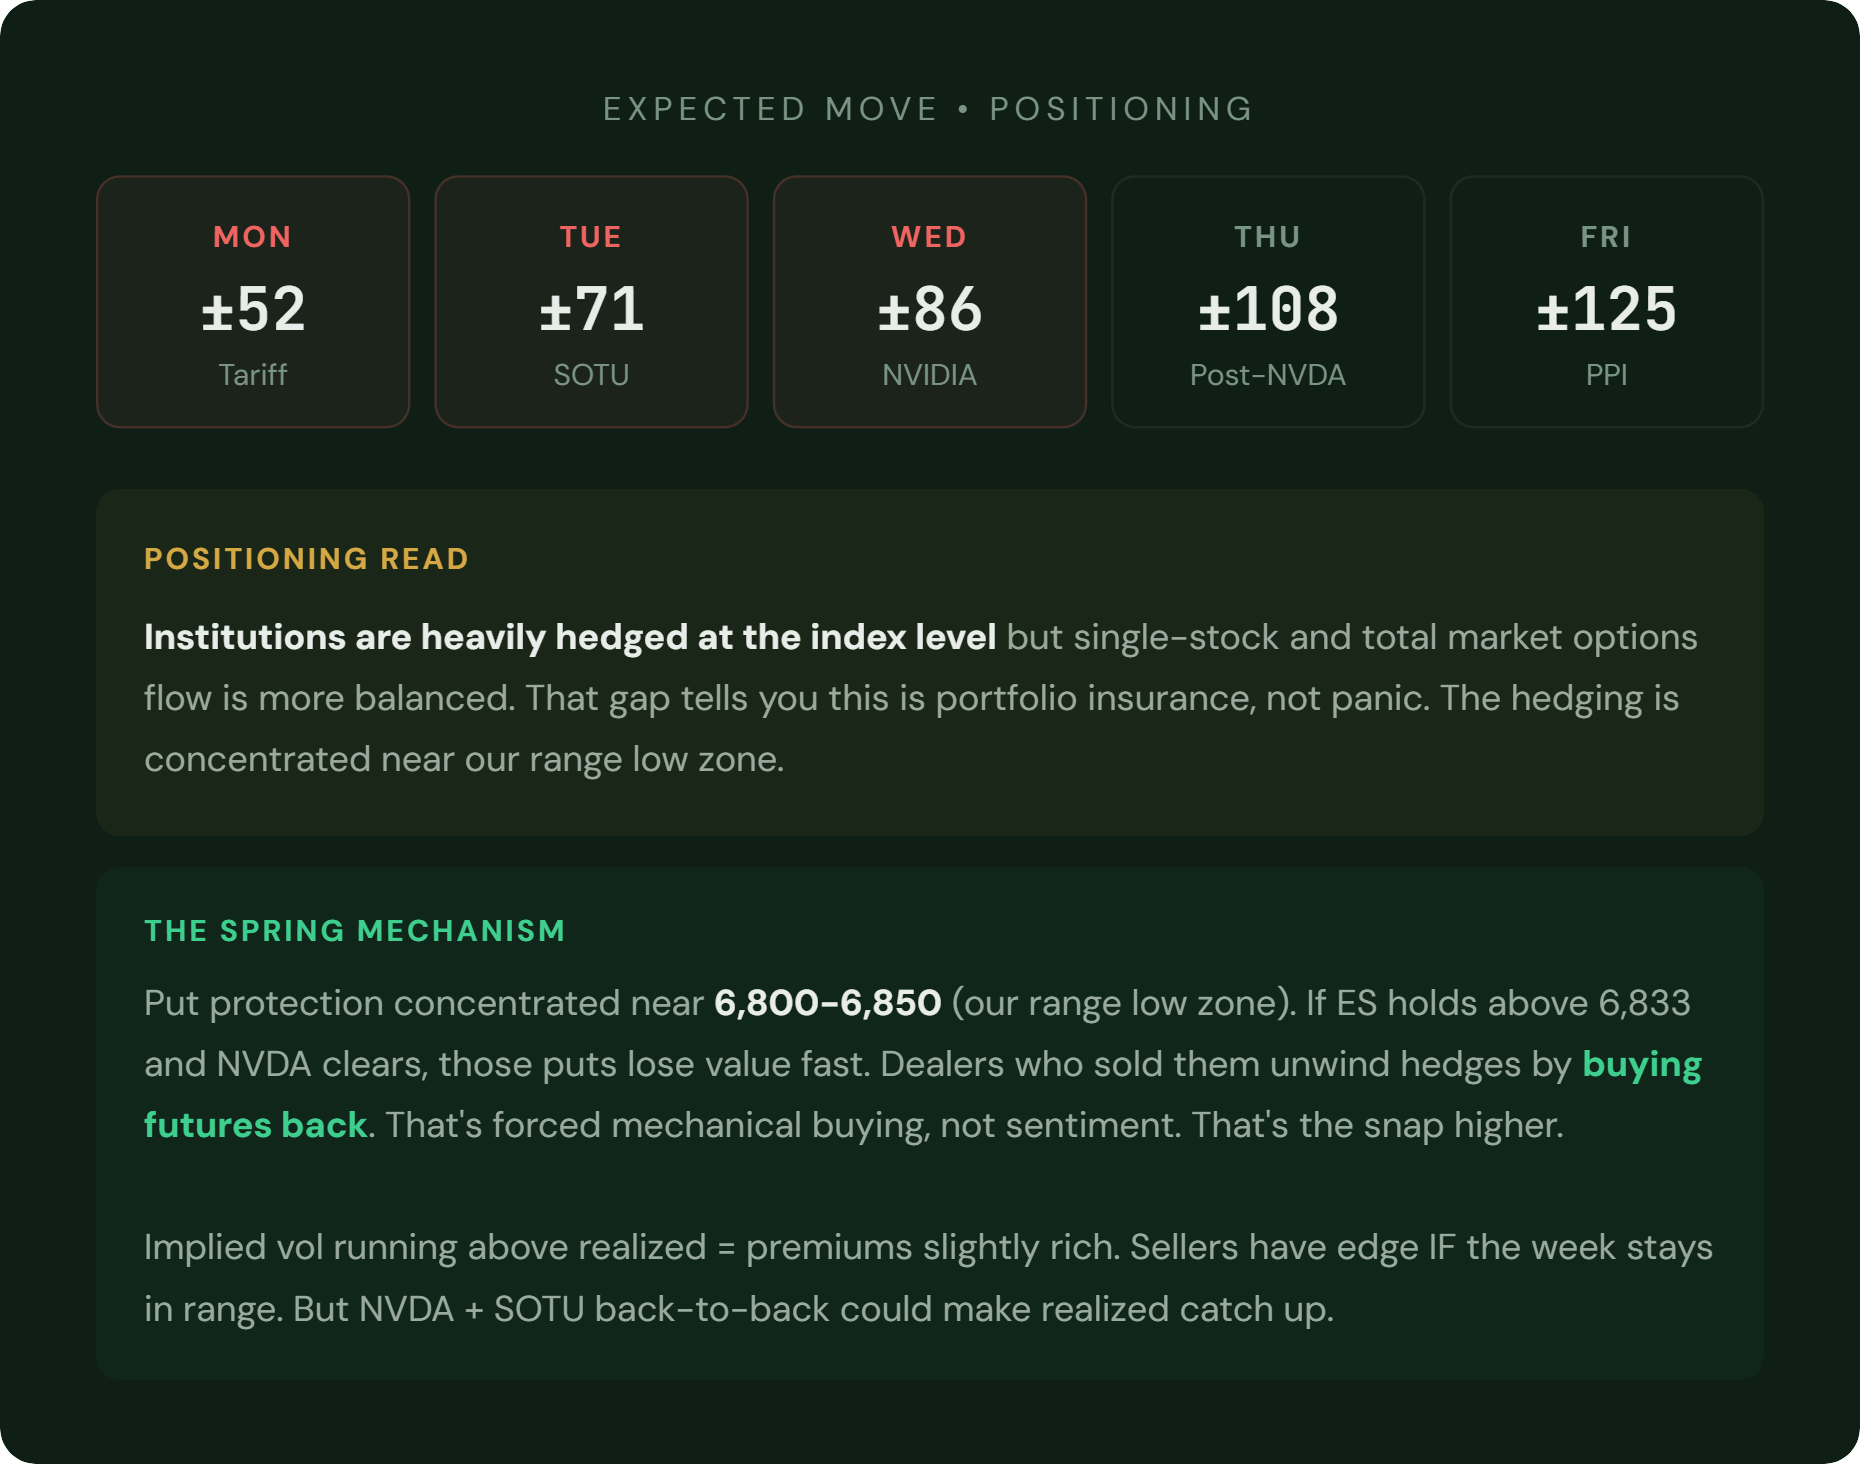
The expected moves ramp through the week:
Monday ±52 (tariff gap risk), Tuesday ±71 (SOTU), Wednesday ±86 (NVIDIA), Thursday ±108 (post-NVDA reaction), Friday ±125 (PPI).
What matters more than the expected move numbers is the positioning underneath.
Where the puts are: Institutions are heavily hedged at the index level. Put/call ratios on the S&P are well above normal. But total market options flow is more balanced. That gap means this is portfolio insurance, not panic. The bulk of this protection is concentrated in the 6,800-6,850 strike range on SPX-equivalent terms, right around our range low at 6,833. That’s the same zone where the rising trendline and horizontal support converge on the chart. Structural and options support stacked at the same price.
Why that matters: If ES holds above 6,833 this week and NVDA clears, those puts start losing value fast. Dealers who sold those puts are short gamma. They’ve been selling futures into weakness and buying into strength, amplifying moves in both directions. As the puts decay, dealers unwind those hedges by buying futures back. That’s the mechanical “snap higher.” Not sentiment. Forced buying from hedge unwinds. And with the wedge compression already in place, the move has extra energy behind it.
IV vs realized: Implied vol is running above realized. Premiums are slightly rich, which means options sellers have an edge if the week stays in range. But with NVDA and SOTU back-to-back, realized could catch up in a hurry.
This week’s catalysts
Monday. Markets react to weekend tariff news. Durable Goods 8:30am. Earnings: Domino’s, Keysight, Diamondback Energy.
Tuesday. 15% global tariff officially takes effect 12:01am. Consumer Confidence 10am (already below the 80 recession threshold, so another drop adds pressure). State of the Union 9pm ET (see SOTU breakdown above). Earnings: Home Depot (before), Workday, First Solar, HP, Axon (after).
Wednesday. THE day. Before: TJX. After: NVIDIA (~$65.5B expected, Blackwell demand commentary matters more than the number), Salesforce, Snowflake, Synopsys.
Thursday. GDP revision (Q4 2nd estimate after Q1 came in at 1.4% vs 3% expected). Initial Claims. Earnings: Dell, Vistra, Intuit, Autodesk, Block.
Friday. PPI 8:30am (PCE ran hot at +0.4%, so another hot read pushes rate cuts further out). Chicago PMI 9:45am.
S&P 500 leaders this week: follow the money
The names leading the S&P 500 right now tell you where capital is actually flowing.
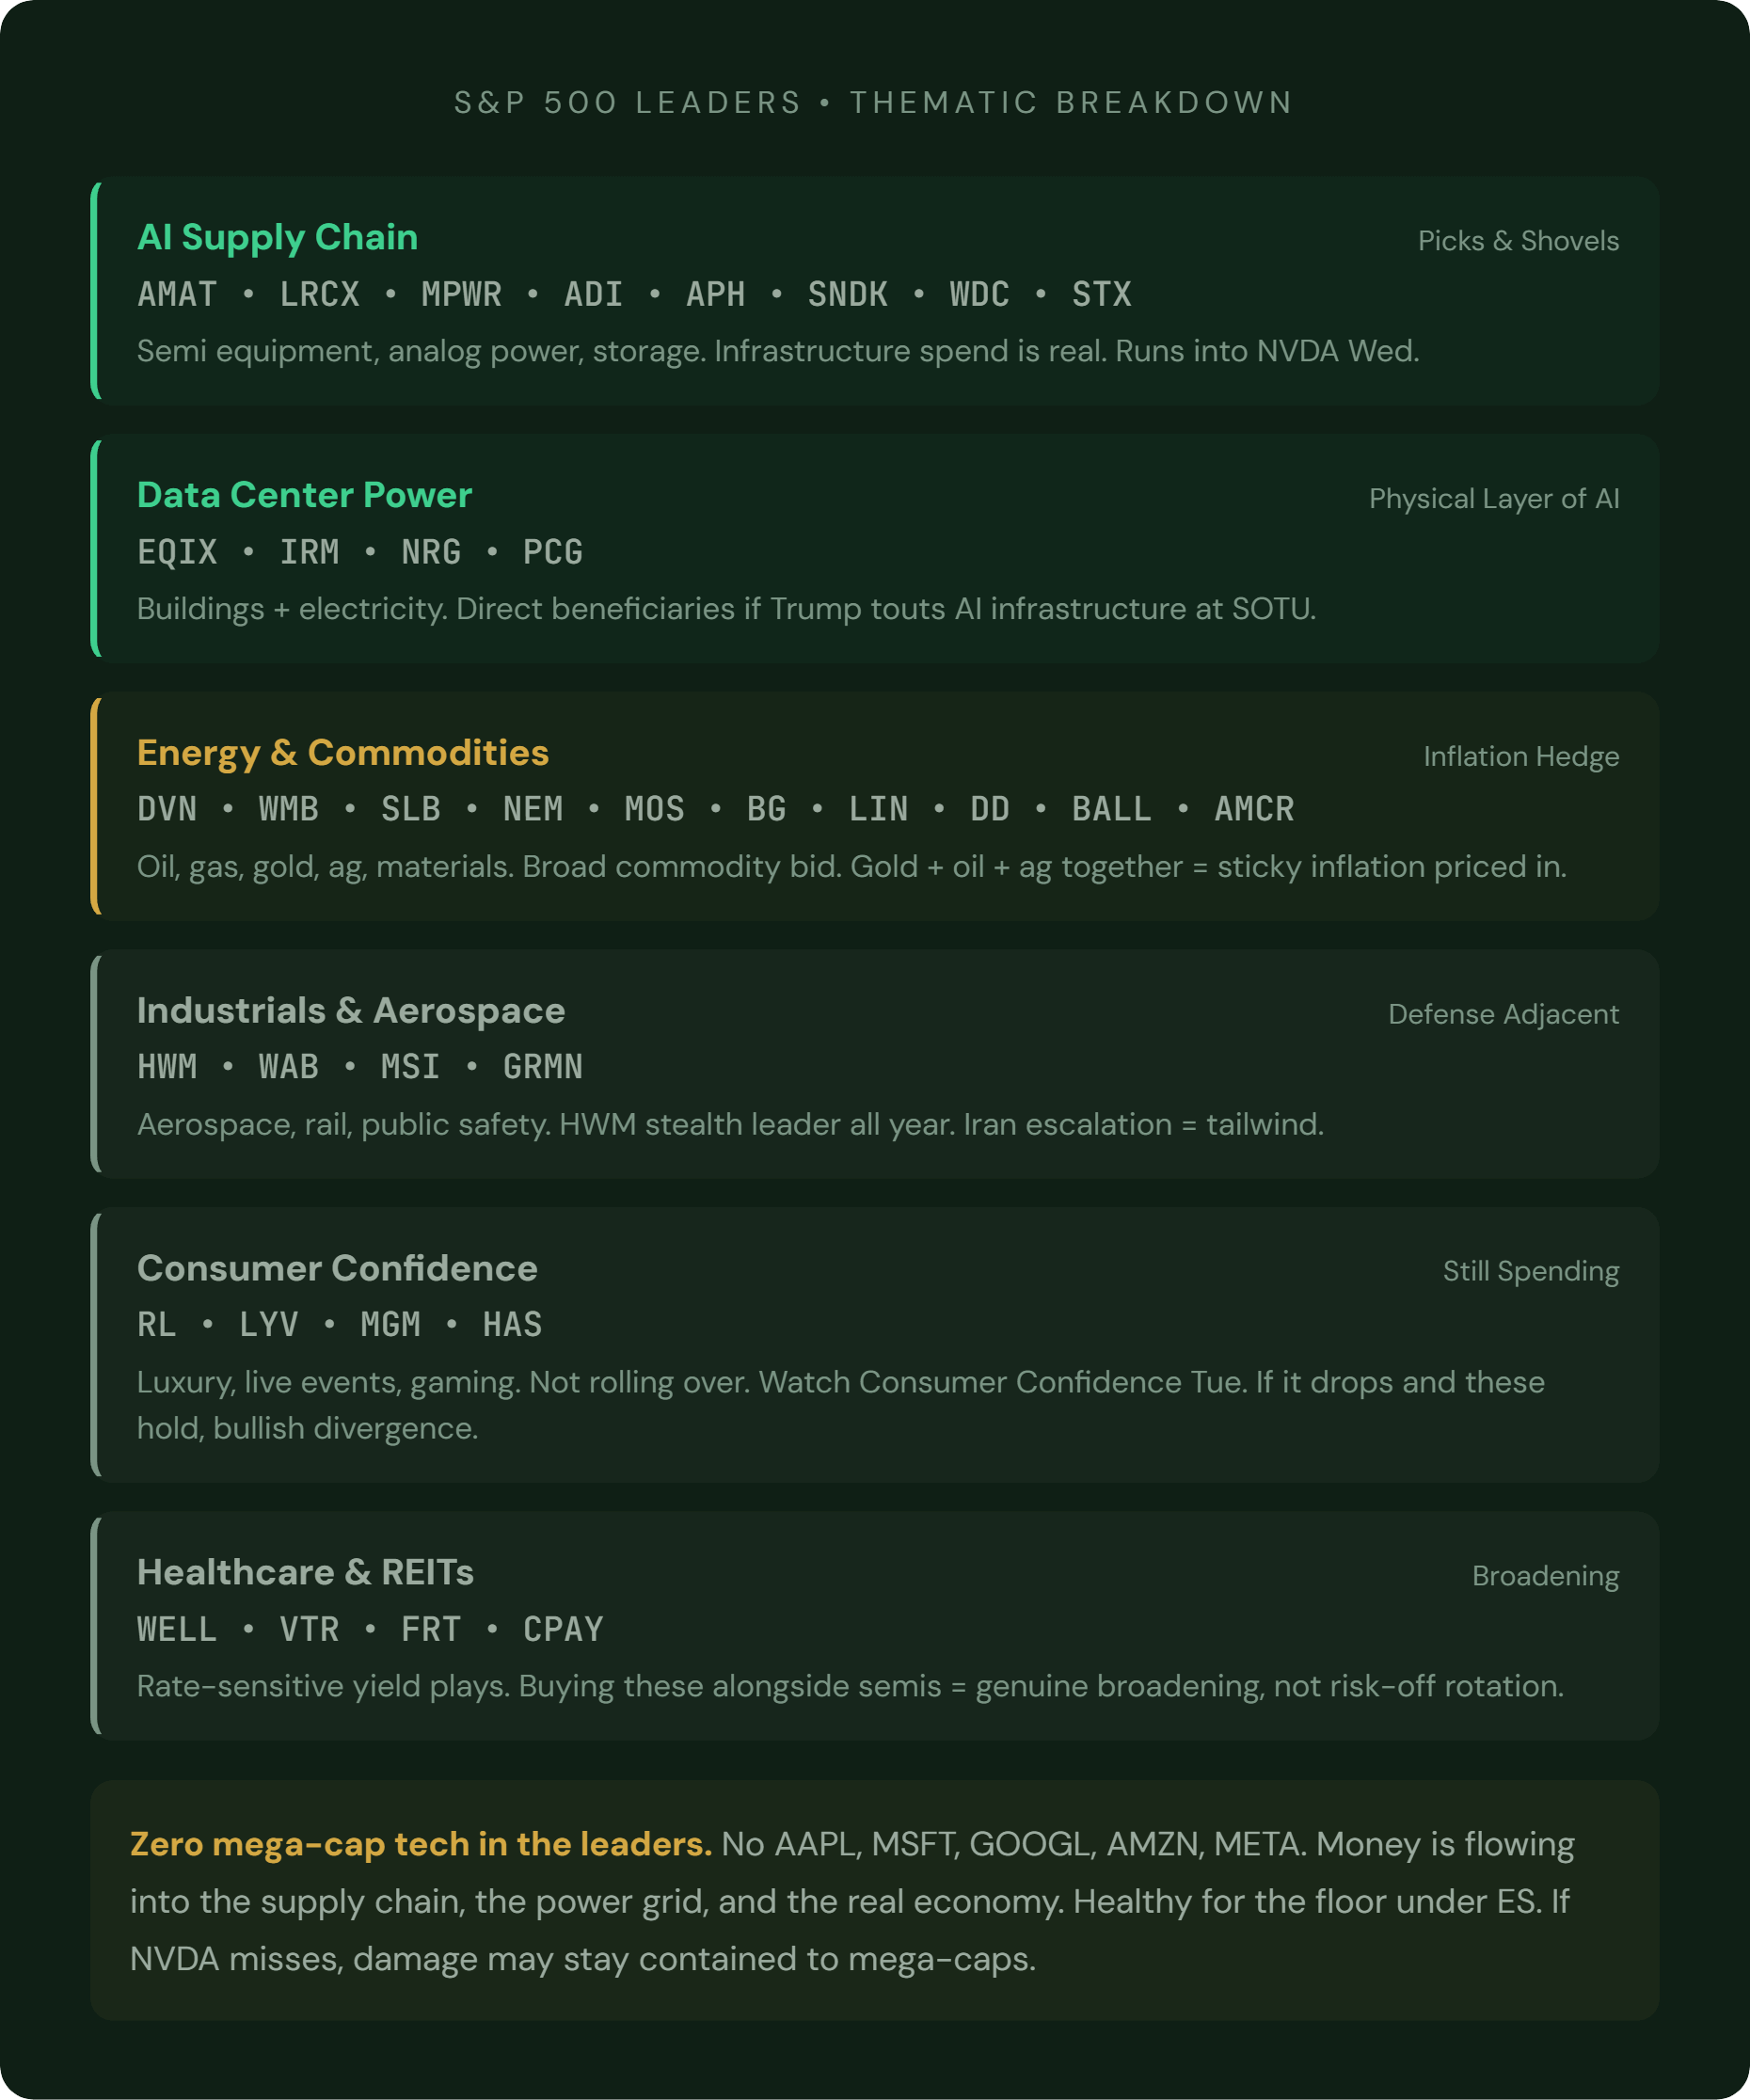
AI supply chain. Not the obvious names. AMAT, LRCX, MPWR, ADI, APH on the semi equipment and analog side. SNDK, WDC, STX on storage. These are the picks and shovels of the AI buildout. When the companies building the chips and the memory are leading, the infrastructure spend is real. This group runs into NVDA Wednesday. If Huang confirms Blackwell demand, these names have room to extend.
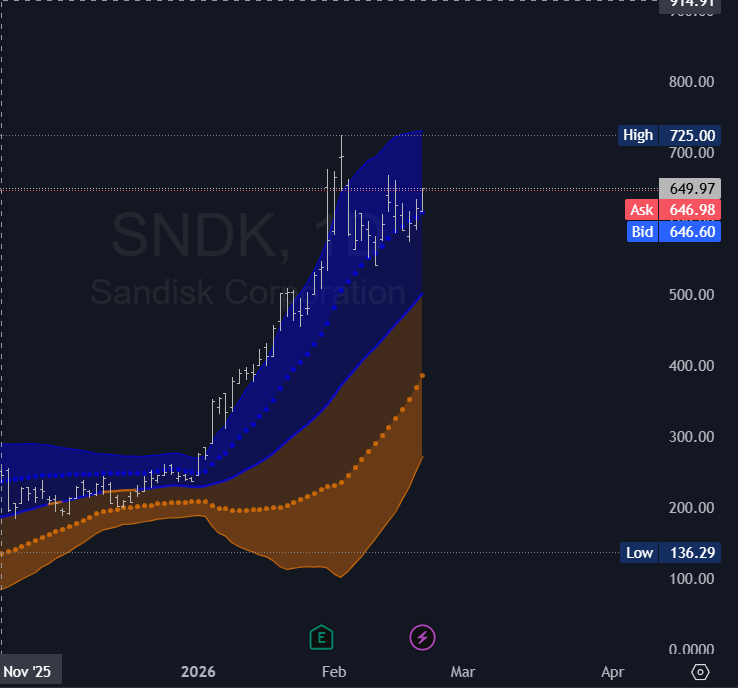
setup/tells examples (coiled at highs):
Data center power. EQIX, IRM for the buildings. NRG, PCG for the electricity. This is the physical layer of AI. When Trump talks AI infrastructure Tuesday night, these are the direct beneficiaries.
Energy and commodities. DVN, WMB, SLB on the energy side. NEM for gold. MOS, BG for agriculture. LIN, DD for industrial materials. BALL, AMCR for packaging. Broad commodity bid. Part inflation hedge, part real demand. Gold strength (NEM) alongside oil (DVN) and ag (MOS) says the market is pricing in sticky inflation.
Industrials and aerospace. HWM (Howmet Aerospace), WAB (rail), MSI (Motorola Solutions), GRMN. Defense-adjacent and infrastructure plays. HWM has been a stealth monster all year. If Trump talks Iran Tuesday night, this group wakes up Wednesday.
Consumer confidence. RL, LYV, MGM, HAS. Ralph Lauren, Live Nation, MGM Resorts, Hasbro. Luxury spending, live events, and gaming are leading. That’s not what you’d expect if the consumer was rolling over. Watch Consumer Confidence Tuesday morning. If it drops again and these names still hold, the divergence is bullish.
Healthcare REITs. WELL, VTR, FRT. Rate-sensitive yield plays broadening out. If the market is buying these alongside semis, it’s not a risk-off rotation. It’s genuine broadening.
The takeaway: Not a single mega-cap tech name in this list. The broadening we flagged in the market context (RSP outperforming, average stock at 17x vs 22x cap-weighted) is showing up in real leadership. Money is flowing into the supply chain, the power grid, and the real economy. That’s healthy for the floor under ES. It also means if NVDA misses Wednesday, the damage may stay contained to mega-caps rather than taking the whole index down.
We’ll have more specific stock setups later this week tied to these themes.
Options setups
Bull: If ES holds the pivot into Wednesday and NVDA beats, call spreads targeting the magnet. Monday acceptance above pivot is your green light.
Bear: If ES closes below support before Wednesday, put spreads targeting the range low. A close below support is the trigger. Not an intraday wick. Closes matter.
Patience: Don’t size into NVDA. Thursday’s open reaction matters more than the number.
Weekend risk: Iran + tariff headlines are still live. Flat or light by Friday close. Gaps don’t care about your stop loss.
The bottom line
ES at 6,923, just above the 6,917 pivot. The wedge is compressing into Wednesday. Monday’s reaction to tariff news sets the tone. Hold above the pivot and the 6,966 magnet is the target. Lose it and you’re looking at 6,875 support, then 6,833 range low where the trendline and options support converge. NVIDIA Wednesday resolves the compression. Range is 6,833 to 7,011. Flat or light by Friday close. Preparation over prediction. That’s the whole game.
A quick note. LobWedge is still early. The fact that you’re here means a lot. If you’re finding the weekly levels and scenarios useful, the best way to help is to share a post with someone who’d get value from it, or forward this email to a trading buddy. Word of mouth is how we grow. And if you’re working on something in the trading or investing space and want to collaborate, just reply to this email. Always open to connecting with good people doing good work.
Disclaimer: LobWedge Research provides market analysis and educational content only. Nothing in this publication constitutes investment advice, a recommendation to buy or sell any security, or a solicitation of any kind. All trading involves risk and you can lose more than your initial investment. Past performance of any levels, scenarios, or analysis does not guarantee future results. The information presented is based on sources believed to be reliable but accuracy is not guaranteed. Always do your own research and consult a licensed financial advisor before making any trading or investment decisions. The author may hold positions in securities mentioned in this publication
New format ..lmk!
Lots to chew on. Much appreciated.