

Rating: Buy
Target Price (12–24 months): $145 to $160
Bull Case (2027): $168+
Fair Value Floor: $125
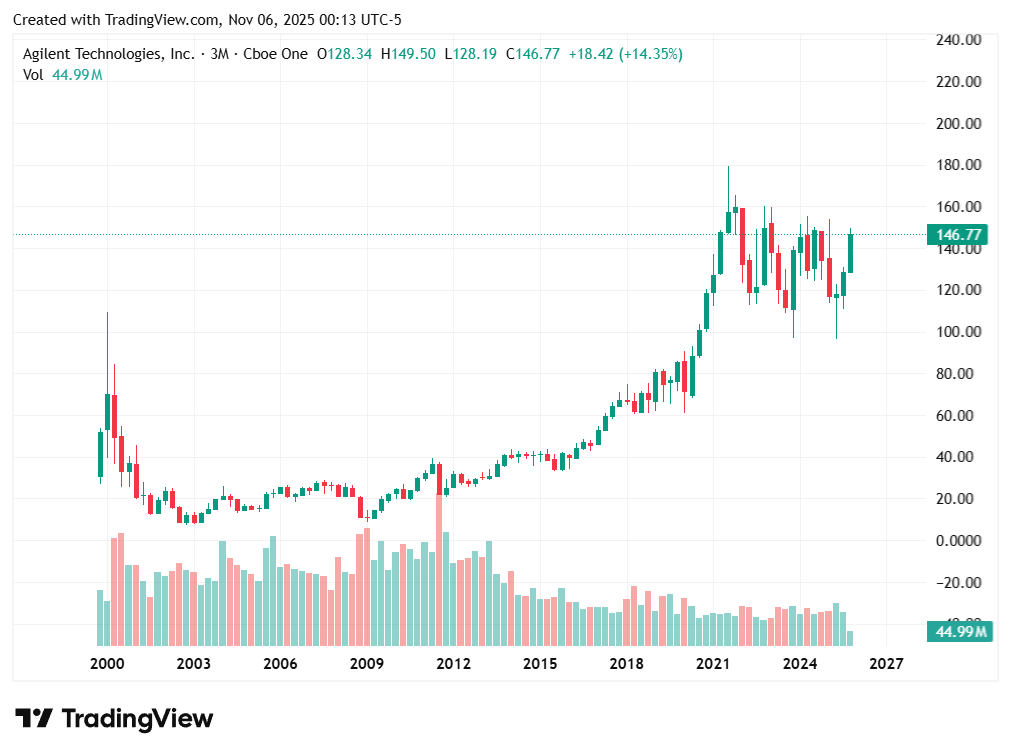
Entry Price (as of Nov 5, 2025): $146.77
Catalyst: Q4 earnings, November 24, 2025
Optionality: Jan 2027 $160 calls
Investment Horizon: 12 to 36 months
Three durable trends are converging across life sciences, manufacturing, and diagnostics.
1. AI Functionality is Embedded Inside Instruments
Agilent’s newest platforms, like the Infinity III HPLC and 8850 GC, are not just tools. They integrate predictive diagnostics, cloud synchronization, and real-time analytics.
“We can now predict when failures will arrive. You can imagine in a refinery, knowing that in advance makes a big difference.”
— Padraig McDonnell, CEO, BofA Global Healthcare Conference, Sept 2025
2. Automation is Being Built Into Labs From Day One
Pharmaceutical reshoring and semiconductor fab expansions are fueling a wave of greenfield lab builds. Agilent is often brought in before construction begins to advise on layout, equipment integration, and workflow planning.
“Labs are planned in these sites, then we’re brought in to set up the lab… make it an effective lab with our equipment.”
— Agilent Q3 2025 Earnings Call
3. Recurring Digital and Service Revenues Are Expanding
Agilent now generates over $1 billion annually in digital revenue. This includes analytics software, diagnostics subscriptions, CRM integrations, and cloud-based performance platforms.
These are not traditional product sales. They represent a platform shift to lab-wide services, offering margin upside and client lock-in.
Real-World Use Cases
To understand the transformation, consider how customers are using Agilent’s new capabilities:
Automated Drug Screening:
Biopharma labs using Agilent HPLC systems can process thousands of samples daily with minimal human input. This accelerates time-to-insight and reduces compliance risk. (Agilent product briefs, 2025)Refinery Safety Monitoring:
AI-enhanced gas chromatography platforms detect gas composition anomalies, allowing for predictive maintenance and reduced downtime. (CEO comments, BofA Conference 2025)New Lab Construction:
In India and the U.S., Agilent has helped design labs for CDMO and semiconductor clients, including full instrumentation, calibration, and ongoing support contracts. (Company commentary, Q3 2025)Remote Quality Assurance:
Cloud-connected instruments send real-time performance and compliance data to corporate dashboards across multiple sites.
These examples go beyond instrumentation. Agilent is now a mission-critical infrastructure provider.
Execution Highlights
The shift is not theoretical. Agilent is executing on multiple fronts:
Over 1,100 legacy LC systems are being replaced with AI-enabled, backward-compatible platforms
New systems deliver up to 20 percent productivity gains and 30 percent energy efficiency improvements
The Ignite digital transformation is generating $1 billion in annual digital revenue
CDMO operations (including NASD and BioVectra) are fully booked into 2026, aligned with GLP-1 drug production and sterile fill-finish needs
This is a business with a strong base, now layering on higher-margin growth engines.
The Financial Setup
Agilent offers a rare combination of quality, consistency, and long-term upside:
Forward P/E is approximately 24.4 times, consistent with historical averages
Free cash flow yield is 2.6 percent, supported by strong operational execution
Gross margin is over 52.5 percent, reflecting pricing strength and product mix
Return on invested capital (ROIC) is 13.4 percent, indicating solid capital efficiency
The business is undergoing a structural shift. A growing share of revenue now comes from digital tools, consumables, and enterprise services. Despite this evolution, the market continues to value Agilent like a legacy equipment supplier rather than a next-generation infrastructure platform. That creates an opportunity for multiple expansion as the business model continues to modernize.
Valuation Scenarios
Agilent’s current valuation still reflects a traditional tools business. But with rising earnings power and a shifting revenue mix, the setup looks increasingly asymmetric.
Using 2026 EPS estimates:
Fair Value Floor: $4.60 EPS × 27 = $124
Base Case: $5.40 EPS × 27 = $145.80
Bull Case: $5.60 EPS × 30 = $168
Even without multiple expansion, projected earnings growth supports a 12 to 18 percent return over the next 12 to 24 months. The real upside comes from structural changes. There is embedded optionality in:
Margin expansion in the CDMO segment
Greater monetization of $1 billion in digital revenue
Continued rollout of AI-native lab platforms
The valuation reflects consistency. The story offers transformation.
Technical Setup
The stock is building strength:
Relative Strength Index is around 63
The stock has cleared its 200-day moving average
Momentum is positive but not stretched
Price is consolidating just under a key breakout level at $148
This is a constructive setup into a likely catalyst with Q4 earnings on deck.
Competitive Landscape
Agilent is not the only name in lab infrastructure, but it may be the most efficient operator at the platform level:
Thermo Fisher (TMO) is diversified but slower to transition to digital-first systems
Danaher (DHR) is restructuring, with strong bioproduction but less integrated AI presence
Waters (WAT) is focused on chromatography but lacks scale in services
Mettler Toledo (MTD) and Bruker (BRKR) are niche players, with limited software leverage
Agilent has the cleanest combination of installed base, product refresh tailwind, digital revenue, and consultative lab services.
Bottom Line
This is not a cyclical trade. It is a structural story with margin expansion, service monetization, and long-term platform potential. Agilent is building the backbone of tomorrow’s labs across industries where accuracy, uptime, and compliance are mission-critical.
The transformation is underway, execution is visible, and the market has not yet re-rated the business model.
Disclaimer
This article is for informational and educational purposes only. It does not constitute investment advice, an offer to buy or sell any securities, or a recommendation for any particular security, strategy, or investment product. The views expressed are those of the author based on publicly available information and are subject to change without notice. While efforts are made to ensure accuracy, no representations or warranties are made as to the completeness or reliability of the content. Investors should conduct their own due diligence or consult with a licensed financial advisor before making any investment decisions. Positions may be held in some of the securities mentioned.